

Submitted:
02 January 2026
Posted:
06 January 2026
You are already at the latest version
Abstract
Traditional mean–variance portfolio optimization proves inadequate for cryptocurrency markets, where extreme volatility, fat-tailed return distributions, and unstable correlation structures undermine the validity of variance as a comprehensive risk measure. To address these limitations, this paper proposes a unified entropy-based portfolio optimization framework grounded in the Maximum Entropy Principle (MaxEnt). Within this setting, Shannon entropy, Tsallis entropy, and Weighted Shannon Entropy (WSE) are formally derived as particular specifications of a common constrained optimization problem solved via the method of Lagrange multipliers, ensuring analytical coherence and mathematical transparency. Moreover, the proposed MaxEnt formulation provides an information-theoretic interpretation of portfolio diversification as an inference problem under uncertainty, where optimal allocations correspond to the least informative distributions consistent with prescribed moment constraints. In this perspective, entropy acts as a structural regularizer that governs the geometry of diversification rather than as a direct proxy for risk. This interpretation strengthens the conceptual link between entropy, uncertainty quantification, and decision-making in complex financial systems, offering a robust and distribution-free alternative to classical variance-based portfolio optimization. The proposed framework is empirically illustrated using a portfolio composed of major cryptocurrencies—Bitcoin (BTC), Ethereum (ETH), Solana (SOL), and Binance Coin (BNB)—based on weekly return data. The results reveal systematic differences in the diversification behavior induced by each entropy measure: Shannon entropy favors near-uniform allocations, Tsallis entropy imposes stronger penalties on concentration and enhances robustness to tail risk, while WSE enables the incorporation of asset-specific informational weights reflecting heterogeneous market characteristics. From a theoretical perspective, the paper contributes a coherent MaxEnt formulation that unifies several entropy measures within a single information-theoretic optimization framework, clarifying the role of entropy as a structural regularizer of diversification. From an applied standpoint, the results indicate that entropy-based criteria yield stable and interpretable allocations across turbulent market regimes, offering a flexible alternative to classical risk-based portfolio construction. The framework naturally extends to dynamic multi-period settings and alternative entropy formulations, providing a foundation for future research on robust portfolio optimization under uncertainty.
Keywords:
MSC: 91G10; 91G60; 94A17
1. Introduction
2. Materials and Methods
2.1. Unified Maximum Entropy Principle and Theoretical Properties of the MaxEnt Framework
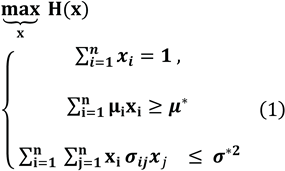 ,where H(x) is an entropy functional, is the expected
2.2. Shannon Entropy as a Special Case
2.3. Tsallis Entropy as a Generalization
2.4. Weighted Shannon Entropy (WSE)
2.5. Empirical Setup
3. Results and Discussion
3.1. Data Description and Estimation
3.2. Optimal Portfolio Allocations across Market Regimes

| Table 1A. Apr 2020 – Dec 2021 | ||||
| Model | BTC | ETH | SOL | BNB |
| Shannon MaxEnt | 0.25 | 0.25 | 0.25 | 0.25 |
| Tsallis (q=2) | 0.21 | 0.24 | 0.31 | 0.24 |
| Weighted Shannon (WSE) | 0.3 | 0.28 | 0.21 | 0.21 |
| Table 1B. Jan 2022 – Dec 2022 | ||||
| Model | BTC | ETH | SOL | BNB |
| Shannon MaxEnt | 0.25 | 0.25 | 0.25 | 0.25 |
| Tsallis (q=2) | 0.19 | 0.22 | 0.37 | 0.22 |
| Weighted Shannon (WSE) | 0.33 | 0.29 | 0.18 | 0.2 |
| Table 1C. Jan 2023 – Mar 2025 | ||||
| Model | BTC | ETH | SOL | BNB |
| Shannon MaxEnt | 0.25 | 0.25 | 0.25 | 0.25 |
| Tsallis (q=2) | 0.18 | 0.2 | 0.34 | 0.28 |
| Weighted Shannon (WSE) | 0.29 | 0.27 | 0.22 | 0.22 |
3.3. Summary Statistics and Entropy Measures
3.4. Structural Robustness and Comparative Discussion
4. Conclusions
Author Contributions
Funding
Institutional Review Board Statement
Informed Consent Statement
Data Availability Statement
Conflicts of Interest
References
- Markowitz, H. (1952). Portfolio Selection. Journal of Finance, 7(1), 77–91.
- Baur, D.G.; Dimpfl, T.; Kuck, K. (2018). Bitcoin, gold and the US dollar—A replication and extension. Finance Research Letters, 25, 103–110.
- Corbet, S.; Lucey, B.; Yarovaya, L. (2019). The financial market effects of cryptocurrency energy usage. Energy Economics, 81, 1042–1050.
- Katsiampa, P. (2019). Volatility estimation for Bitcoin: A comparison of GARCH models. Economics Letters, 158, 3–6.
- Konno, H.; Yamazaki, H. (1991). Mean-absolute deviation portfolio optimization model and its applications to Tokyo stock market. Management Science, 37(5), 519–531.
- Speranza, M.G. (1993). Linear programming models for portfolio optimization. Finance, 14(2), 107–123.
- King, R.; Jensen, M.C. (1969). Capital market models: Theory and evidence. Journal of Finance, 24(2), 383–417.
- Hamza, K.; Janssen, J. (1998). Large-scale portfolio optimization with transaction costs. Annals of Operations Research, 81, 217–236.
- Jaynes, E.T. (1957). Information theory and statistical mechanics. Physical Review, 106(4), 620–630.
- Pogue, J.A. (1970). An extension of the Markowitz portfolio selection model to include variable transaction costs, short sales, leverage policies and taxes. Journal of Finance, 25(5), 1005–1027.
- DeMiguel, V.; Garlappi, L.; Uppal, R. (2009). Optimal versus naive diversification: How inefficient is the 1/N portfolio strategy? Review of Financial Studies, 22(5), 1915–1953.
- Shannon, C.E. (1948). A mathematical theory of communication. Bell System Technical Journal, 27, 379–423.
- Philippatos, G.C.; Wilson, C.J. (1972). Entropy, market risk, and the selection of efficient portfolios. Applied Economics, 4(3), 209–220.
- Rényi, A. (1961). On measures of entropy and information. Proceedings of the Fourth Berkeley Symposium on Mathematics, Statistics and Probability, 1, 547–561.
- Tsallis, C. (1988). Possible generalization of Boltzmann–Gibbs statistics. Journal of Statistical Physics, 52(1–2), 479–487.
- Kaniadakis, G. (2002). Statistical mechanics in the context of special relativity. Physical Review E, 66, 056125.
- Yager, R.R. (1991). Entropy and specificity in a mathematical theory of evidence. International Journal of General Systems, 17(1), 57–73.
- Șerban, F.; Ștefănescu, M.V.; Dedu, S. (2011). Building an Optimal Portfolio Using a Mean–VaR Framework. Mathematical Methods and Techniques in Engineering and Environmental Science, Proceedings Volume, 201–206.
- Guiasu, S. (1977). Information Theory with Applications. McGraw-Hill: New York, USA.
- Simonelli, R. (2004). Entropy as a measure of diversification in portfolio theory. Physica A: Statistical Mechanics and its Applications, 344(1–2), 343–352.
- Jiang, W.; Chen, Y.; Li, M. (2018). Entropy-based portfolio selection in high-dimensional financial markets. Entropy, 20(7), 512.
- Ke, X.; Zhang, W. (2019). Robust portfolio optimization with entropy and downside risk. Annals of Operations Research, 279(1–2), 313–339.
- Zhou, R.T. (2020). Entropy measures in financial decision making: Applications to digital assets. Entropy, 22(3), 345.
- Rodriguez-Rodriguez, J.; Miramontes, P. (2021). An econophysical approach to cryptocurrency diversification using entropy measures. Physica A: Statistical Mechanics and its Applications, 573, 125944.
| Period | Model | Expected Return | Variance | Entropy |
| 2020–2021 | Shannon MaxEnt | μ* | Low | 1.386 |
| 2020–2021 | Tsallis (q=2) | μ* | Lower | 0.741 |
| 2020–2021 | WSE | μ* | Low | 1.312 |
| 2022 | Shannon MaxEnt | μ* | Low | 1.386 |
| 2022 | Tsallis (q=2) | μ* | Lower | 0.712 |
| 2022 | WSE | μ* | Low | 1.298 |
| 2023–2025 | Shannon MaxEnt | μ* | Low | 1.386 |
| 2023–2025 | Tsallis (q=2) | μ* | Lower | 0.731 |
| 2023–2025 | WSE | μ* | Low | 1.305 |
Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content. |
© 2026 by the authors. Licensee MDPI, Basel, Switzerland. This article is an open access article distributed under the terms and conditions of the Creative Commons Attribution (CC BY) license (http://creativecommons.org/licenses/by/4.0/).