

Submitted:
22 December 2025
Posted:
22 December 2025
You are already at the latest version
Abstract
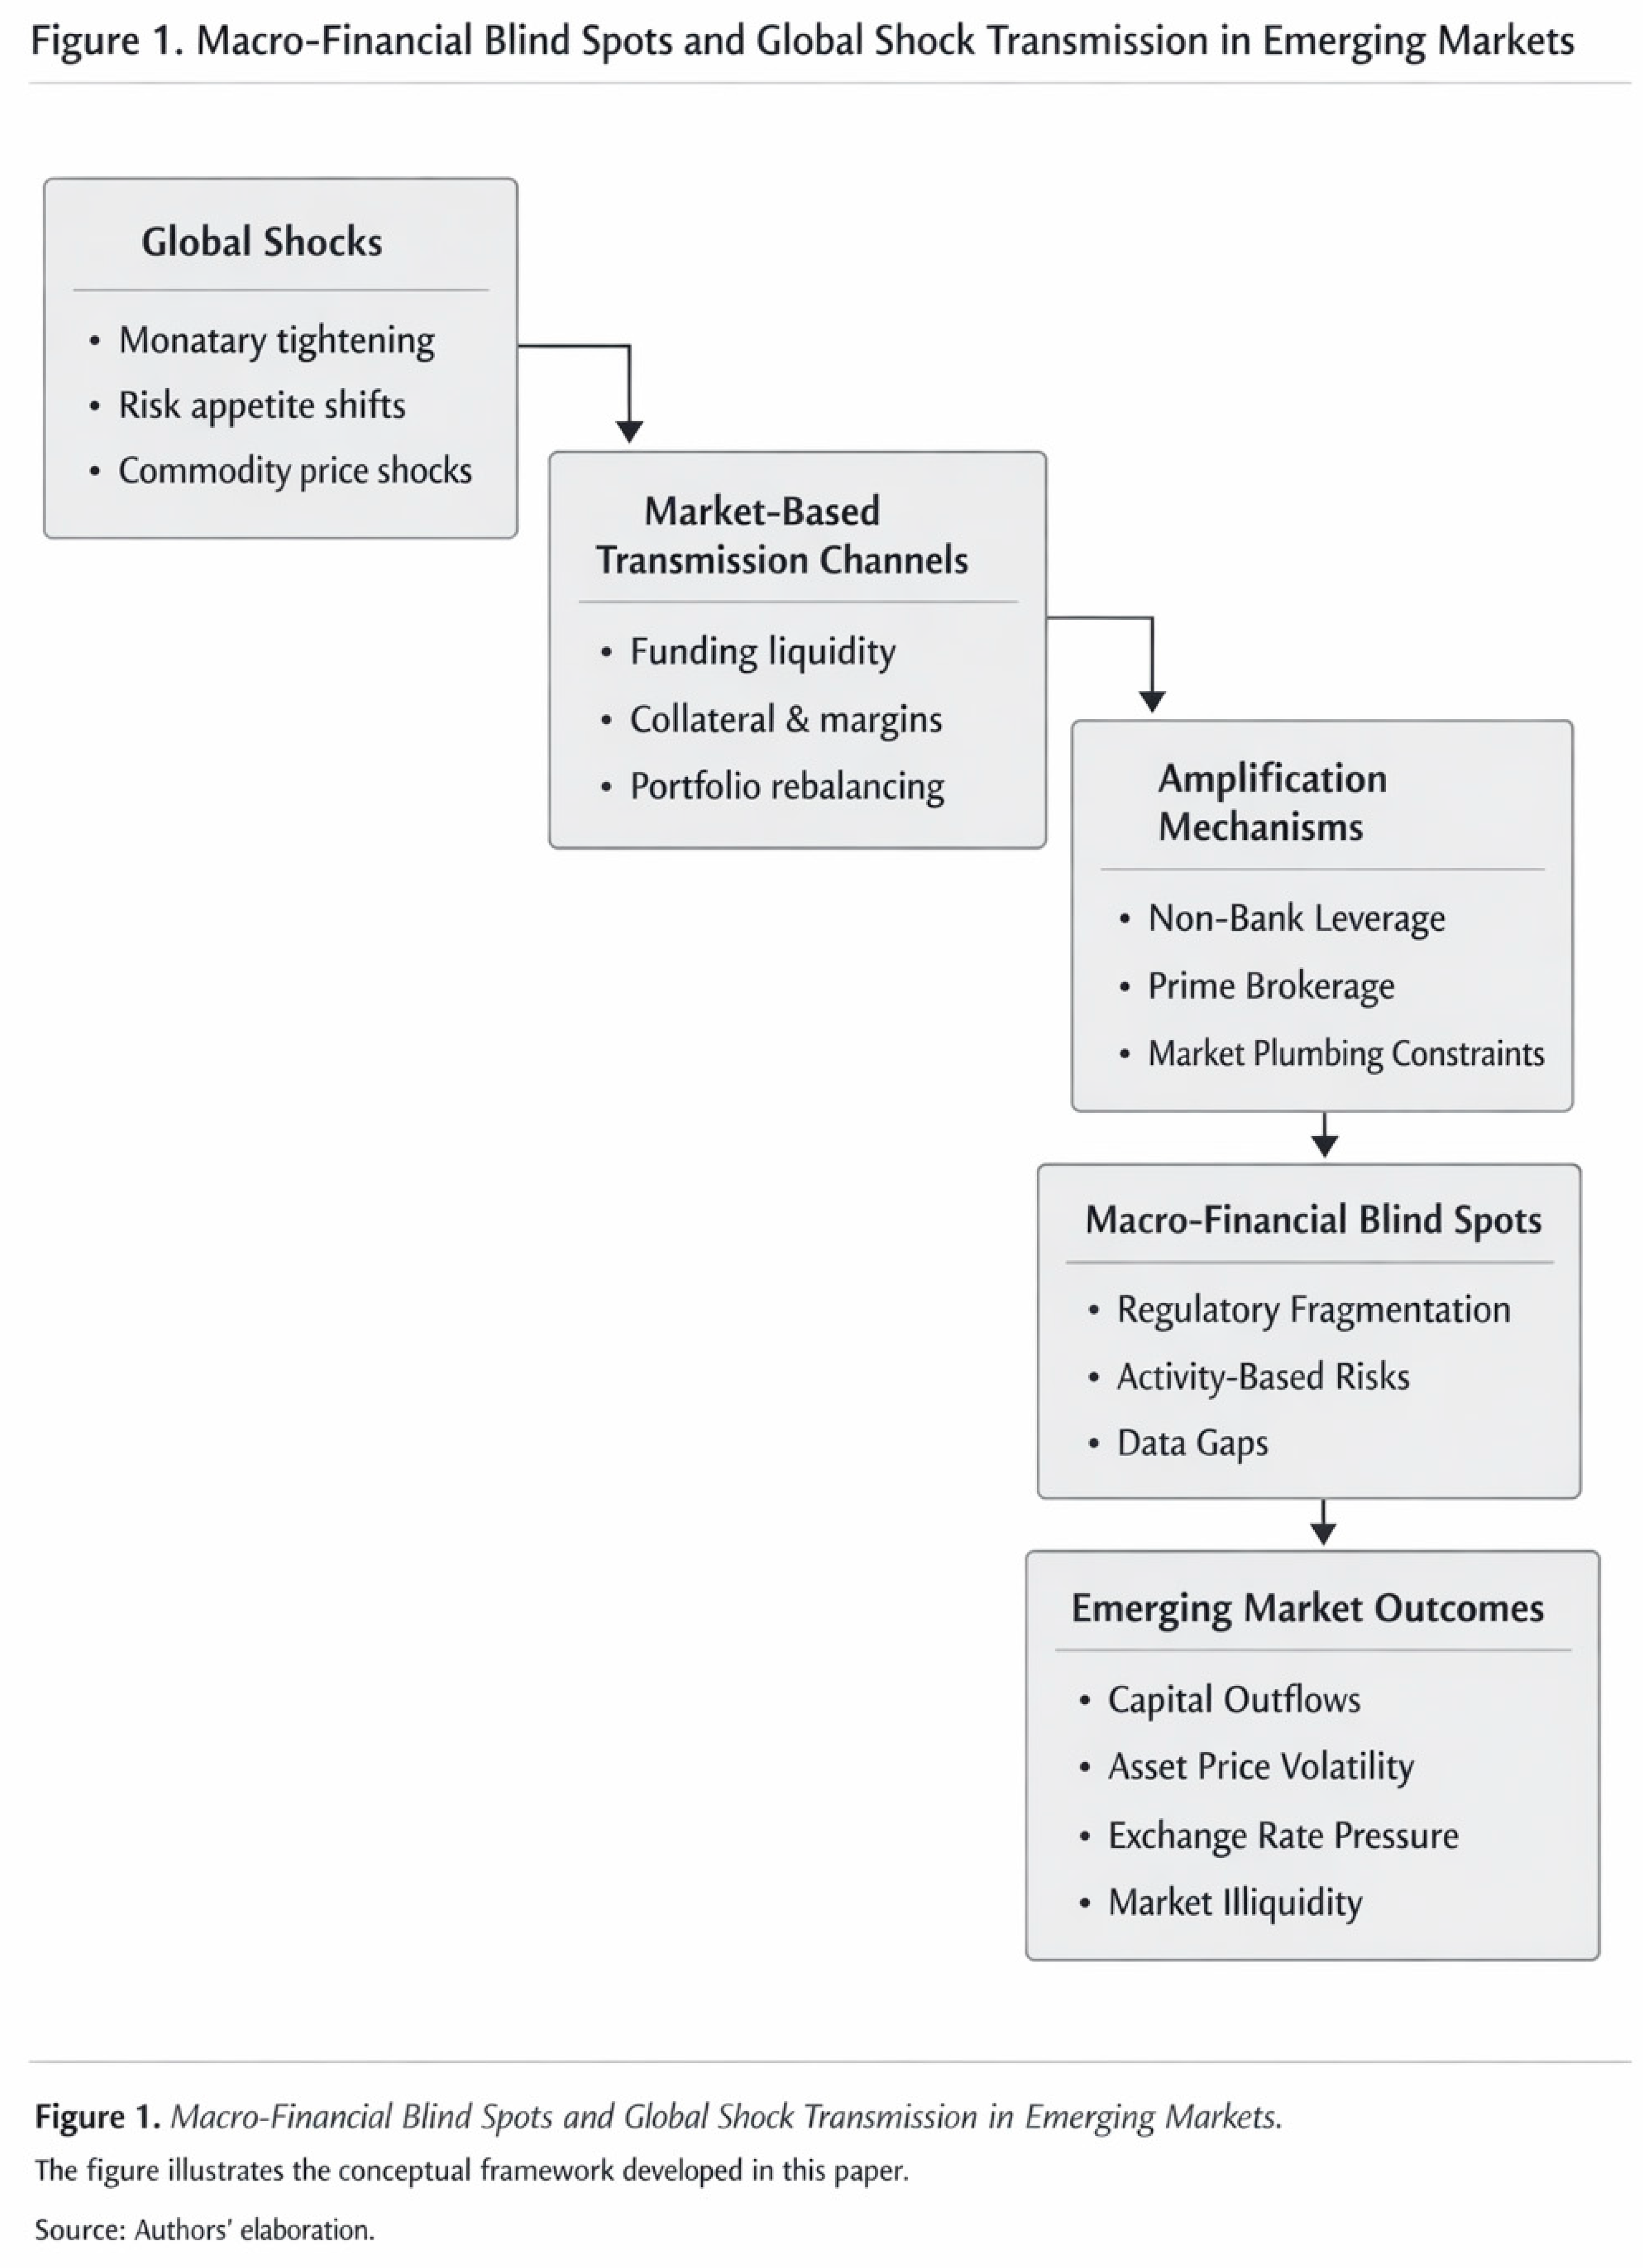
Despite significant advances in bank regulation and the widespread adoption of macroprudential frameworks, emerging market economies remain persistently vulnerable to global financial shocks. Episodes such as the Global Financial Crisis, the COVID-19 market turmoil, and recent monetary tightening cycles reveal that financial stress originating in core markets continues to transmit rapidly and forcefully to emerging economies. This paper argues that such vulnerability reflects structural features of contemporary financial systems rather than deficiencies in domestic banking regulation alone. Adopting a conceptual and analytical approach, the article develops an integrated framework of macro-financial blind spots that links global financial cycles, non-bank financial intermediation, and regulatory fragmentation. The analysis highlights how funding liquidity, collateral valuation, margin dynamics, and market-based leverage amplify global shocks through channels that lie largely outside traditional, bank-centric macroprudential frameworks. As market-based finance expands, systemic risk increasingly originates in activities rather than institutions, limiting the effectiveness of entity-based regulation and reinforcing emerging markets’ role as price-takers in global portfolios. The paper contributes to the literature by synthesizing insights from macroprudential policy, market liquidity, and non-bank finance to explain the persistence of emerging market vulnerability in an era of globalized funding. It further derives policy implications for macro-financial governance, emphasizing the need for system-wide, activity-based approaches, improved data and transparency, and stronger domestic and international regulatory coordination. These findings are relevant for policymakers seeking to reconcile financial integration with systemic resilience in emerging markets.
Keywords:
1. Introduction
2. Macroprudential Policy, Financial Cycles, and Structural Limits
3. Market-Based Finance, Non-Bank Intermediation, and Liquidity Fragility
4. Global Financial Cycles, Commodity Dynamics, and Emerging Market Vulnerability
5. Macro-Financial Blind Spots: An Integrated Framework and Policy Implications
6. Conclusion
Conflicts of Interest
References
- Aiyar, S., Calomiris, C. W., & Wieladek, T. (2014). Does macro-prudential regulation leak? Evidence from a UK policy experiment. Journal of Money, Credit and Banking, 46(1), 181–214. [CrossRef]
- Aramonte, S., Schrimpf, A., & Shin, H. S. (2021). Non-bank financial intermediaries and financial stability. BIS Working Papers, No. 972. Bank for International Settlements.
- Bank for International Settlements. (2025). BIS quarterly review: International banking and financial market developments (December). BIS.
- Brunnermeier, M. K., & Pedersen, L. H. (2009). Market liquidity and funding liquidity. Review of Financial Studies, 22(6), 2201–2238. [CrossRef]
- Calvo, G. A. (1998). Capital flows and capital-market crises: The simple economics of sudden stops. Journal of Applied Economics, 1(1), 35–54.
- Claessens, S., Ratnovski, L., & Singh, M. (2021). Macroprudential policies and non-bank financial intermediation. International Journal of Central Banking, 17(2), 1–45.
- Crockett, A. (2000). Marrying the micro- and macro-prudential dimensions of financial stability. BIS Speeches. Bank for International Settlements.
- Deku, S. Y., Kara, A., & Zhou, H. (2019). Securitisation and financial stability: A systematic review of the literature. International Review of Financial Analysis, 63, 189–202. [CrossRef]
- Duffie, D. (2020). Intermediation of U.S. Treasury securities after the COVID-19 crisis. Hutchins Center Working Paper No. 72. Brookings Institution.
- Eichengreen, B., & Hausmann, R. (Eds.). (2005). Other people’s money: Debt denomination and financial instability in emerging market economies. University of Chicago Press.
- European Systemic Risk Board. (2024). A system-wide approach to macroprudential policy. ESRB.
- Falato, A., Goldstein, I., & Hortaçsu, A. (2020). Financial fragility in the COVID-19 crisis: The case of investment funds in corporate bond markets. NBER Working Paper No. 27559. [CrossRef]
- Financial Stability Board. (2020). Holistic review of the March 2020 market turmoil. FSB.
- Financial Stability Board. (2025). Global monitoring report on non-bank financial intermediation 2025. FSB.
- Financial Stability Board. (2025). Leverage in non-bank financial intermediation: Final report. FSB.
- Gorton, G., & Metrick, A. (2012). Regulated banking and the run on repo. Journal of Financial Economics, 104(3), 425–451. [CrossRef]
- Haddad, V., Moreira, A., & Muir, T. (2021). When selling becomes viral: Disruptions in debt markets in the COVID-19 crisis and the Fed’s response. Review of Financial Studies, 34(11), 5309–5351. [CrossRef]
- Huang, Y., & Jiang, Y. (2025). Shadow banking and systemic risk: Evidence and channels. Research in International Business and Finance, 69, Advance online publication.
- Kindleberger, C. P., & Aliber, R. Z. (2011). Manias, panics, and crashes: A history of financial crises (6th ed.). Palgrave Macmillan.
- Minsky, H. P. (1986). Stabilizing an unstable economy. Yale University Press.
- Mitchell, M., Pedersen, L. H., & Pulvino, T. (2012). Slow moving capital. Journal of Finance, 67(6), 2151–2193. [CrossRef]
- Mishra, A. K., Narayan, P. K., & Smyth, R. (2020). Stock market liquidity, funding liquidity, and monetary policy. International Review of Economics & Finance, 67, 51–65. [CrossRef]
- Rey, H. (2015). Dilemma not trilemma: The global financial cycle and monetary policy independence. In Proceedings of the Jackson Hole Economic Policy Symposium. Federal Reserve Bank of Kansas City.
- Ryu, D., Webb, R. I., & Yu, J. (2022). Funding liquidity shocks and market liquidity providers. Finance Research Letters, 47, 102734. [CrossRef]
- Schrimpf, A., Shin, H. S., & Sushko, V. (2020). Leverage and margin spirals in fixed income markets during the COVID-19 crisis. BIS Bulletin, No. 2.
- Sikalao-Lekobane, O. (2025). Macroprudential tightening and FinTech credit: Evidence of regulatory arbitrage. Economic Modelling, 123, Advance online publication.
- Zhu, Y., & Ma, S. (2025). Global financial cycle downturns and systemic risk: Evidence and transmission channels. Borsa Istanbul Review, 25(1), 1–15.
Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content. |
© 2025 by the authors. Licensee MDPI, Basel, Switzerland. This article is an open access article distributed under the terms and conditions of the Creative Commons Attribution (CC BY) license (http://creativecommons.org/licenses/by/4.0/).