

Submitted:
27 October 2025
Posted:
29 October 2025
You are already at the latest version
Abstract
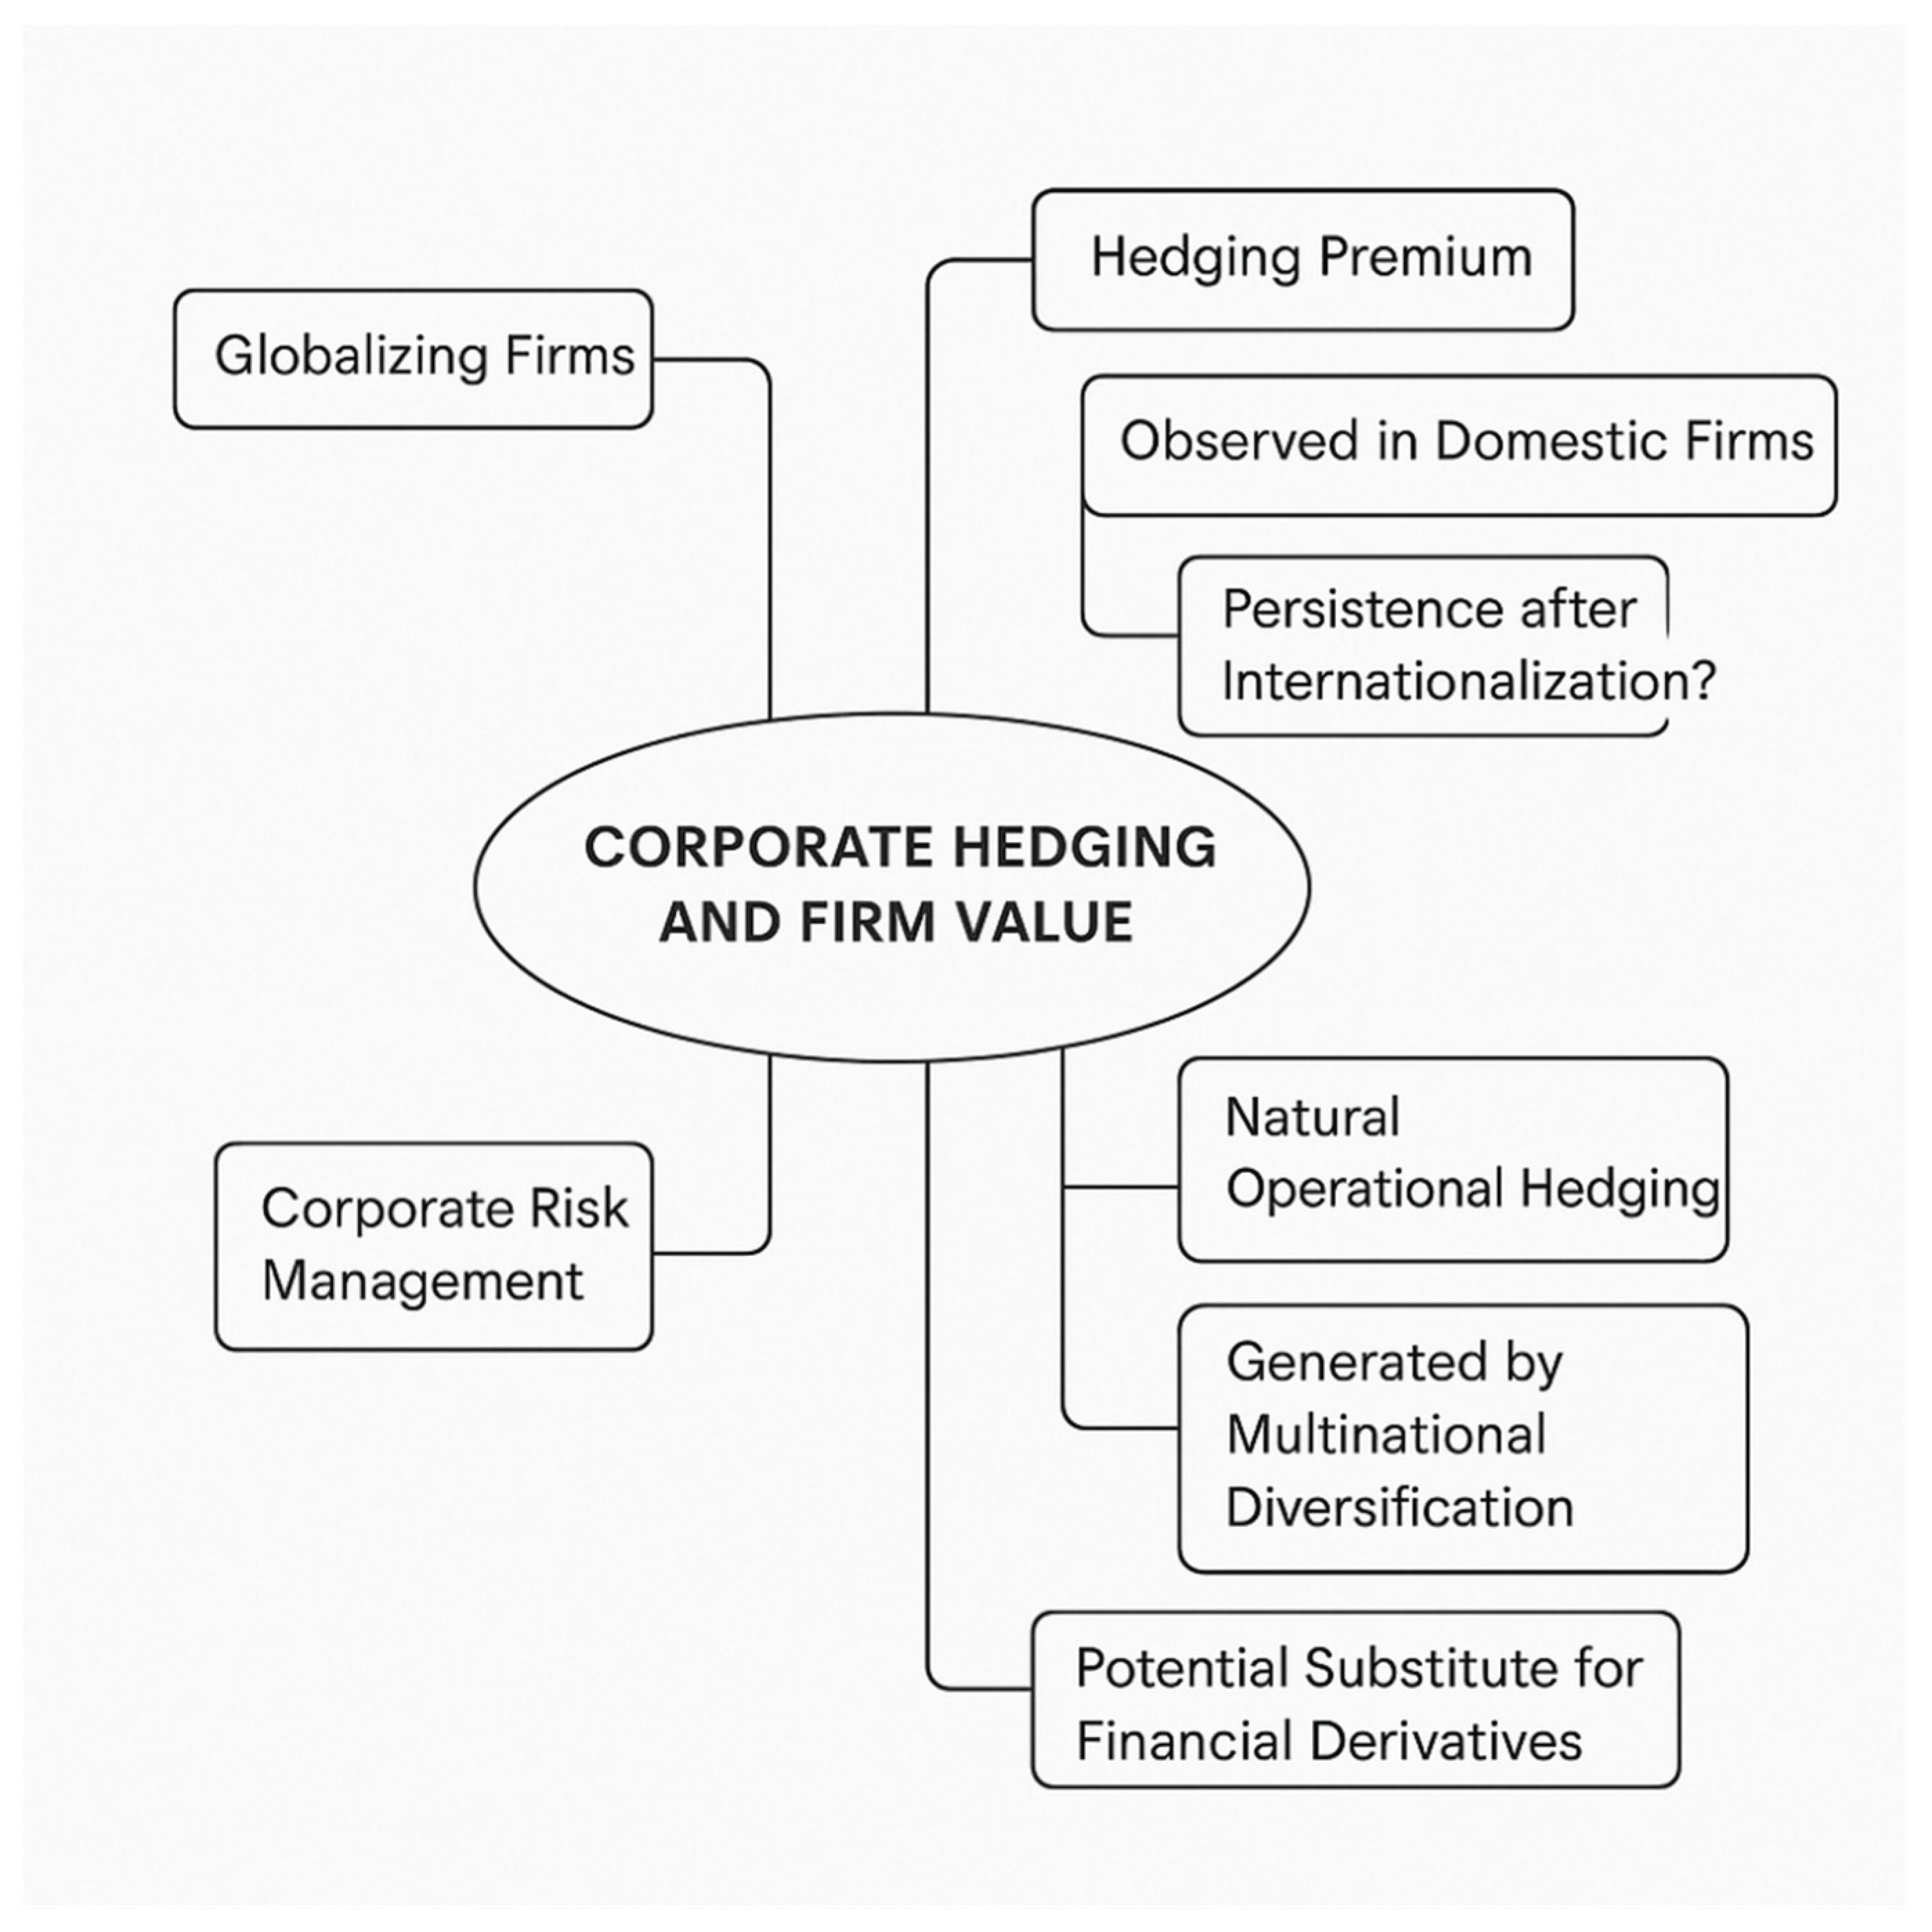
This study investigates the relationship between corporate hedging and firm value, with a focus on how this relationship evolves when firms transition from domestic operations to multinational status. Using a sample of 66 U.S. firms observed in 1999 and 2014, the analysis examines whether the previously observed "hedging premium"—an increase in firm value linked to financial derivatives usage—persists in globally diversified firms. Tobin’s Q is used as a proxy for firm value. Results show that prior to multinational expansion, financial hedging contributes significantly to firm value. However, this premium diminishes after internationalization, indicating that natural operational hedging from global diversification may substitute for financial derivatives. The study has implications for corporate risk managers in adapting hedging strategies across globalization cycles.
Keywords:
Introduction
- Literature Review
Methods and Data
2.1. Sample
2.2. Variables
The Role of Control Variables in Estimating the Hedging–Firm Value Relationship
- 1.
- Return on Assets (ROA)
- 2.
- Leverage (Debt/Assets)
- 3.
- Firm Size (Log of Total Assets)
- 4.
- Dividend Dummy (1 if dividends paid)
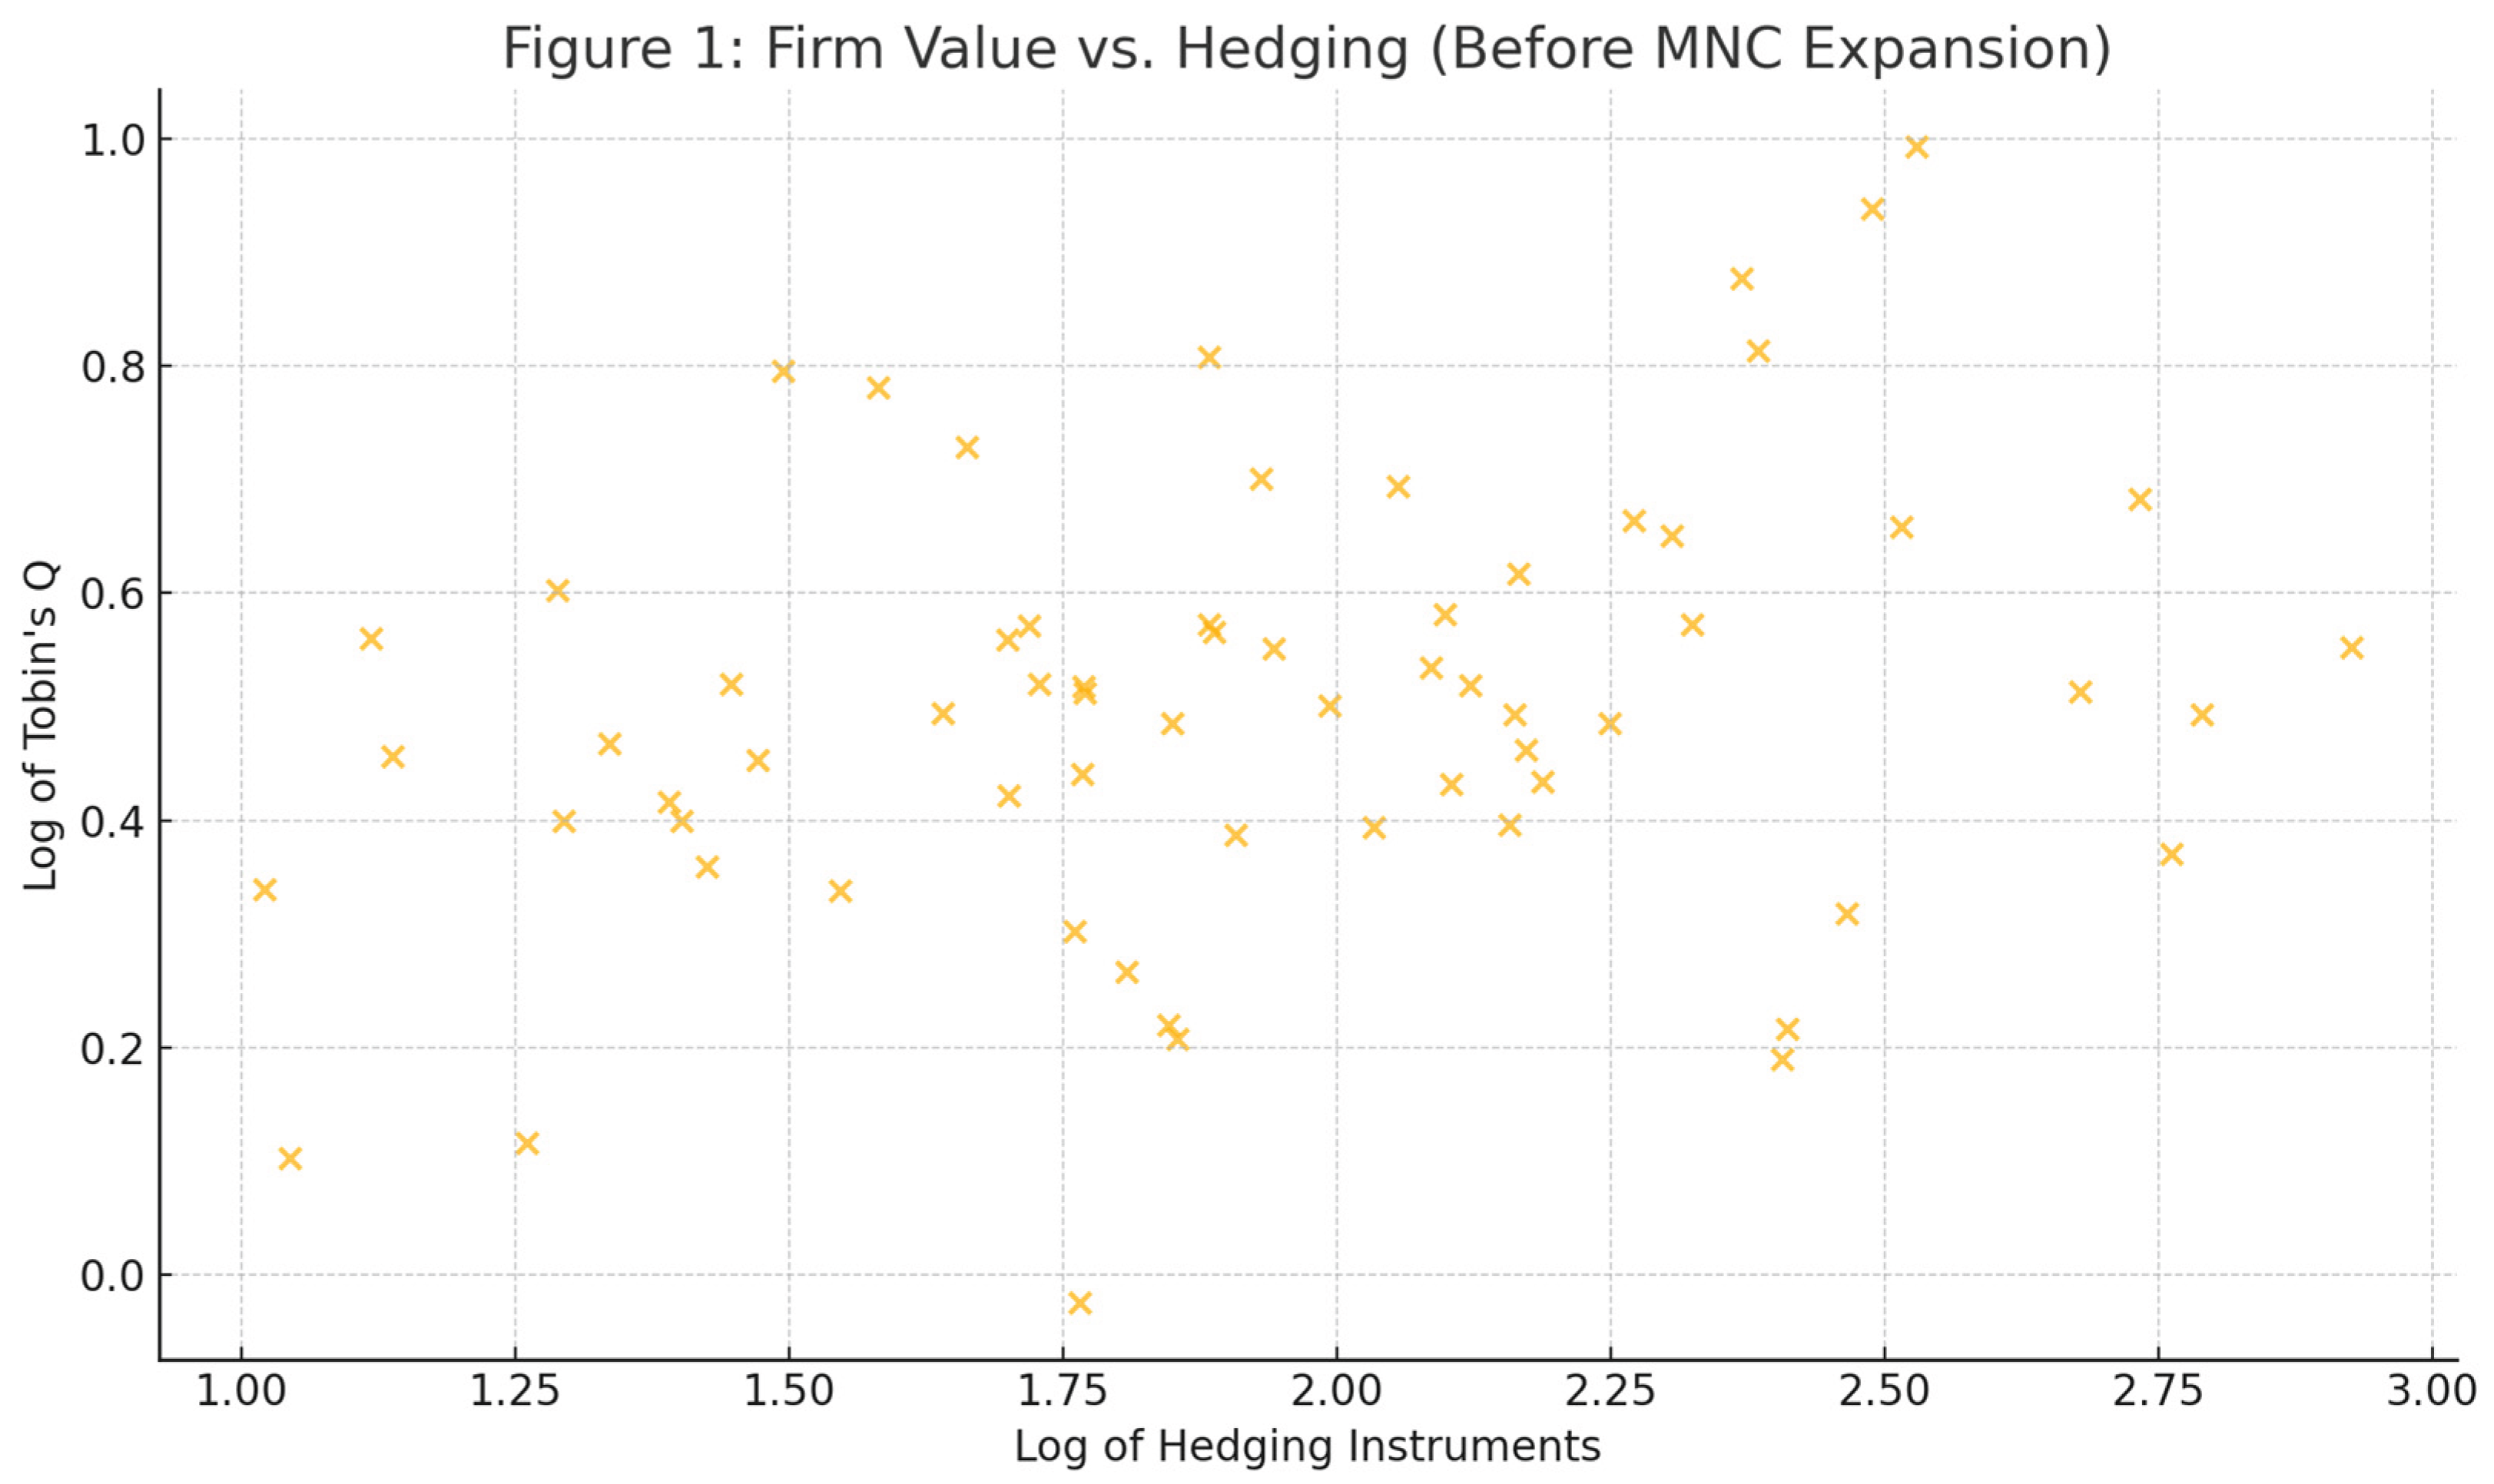
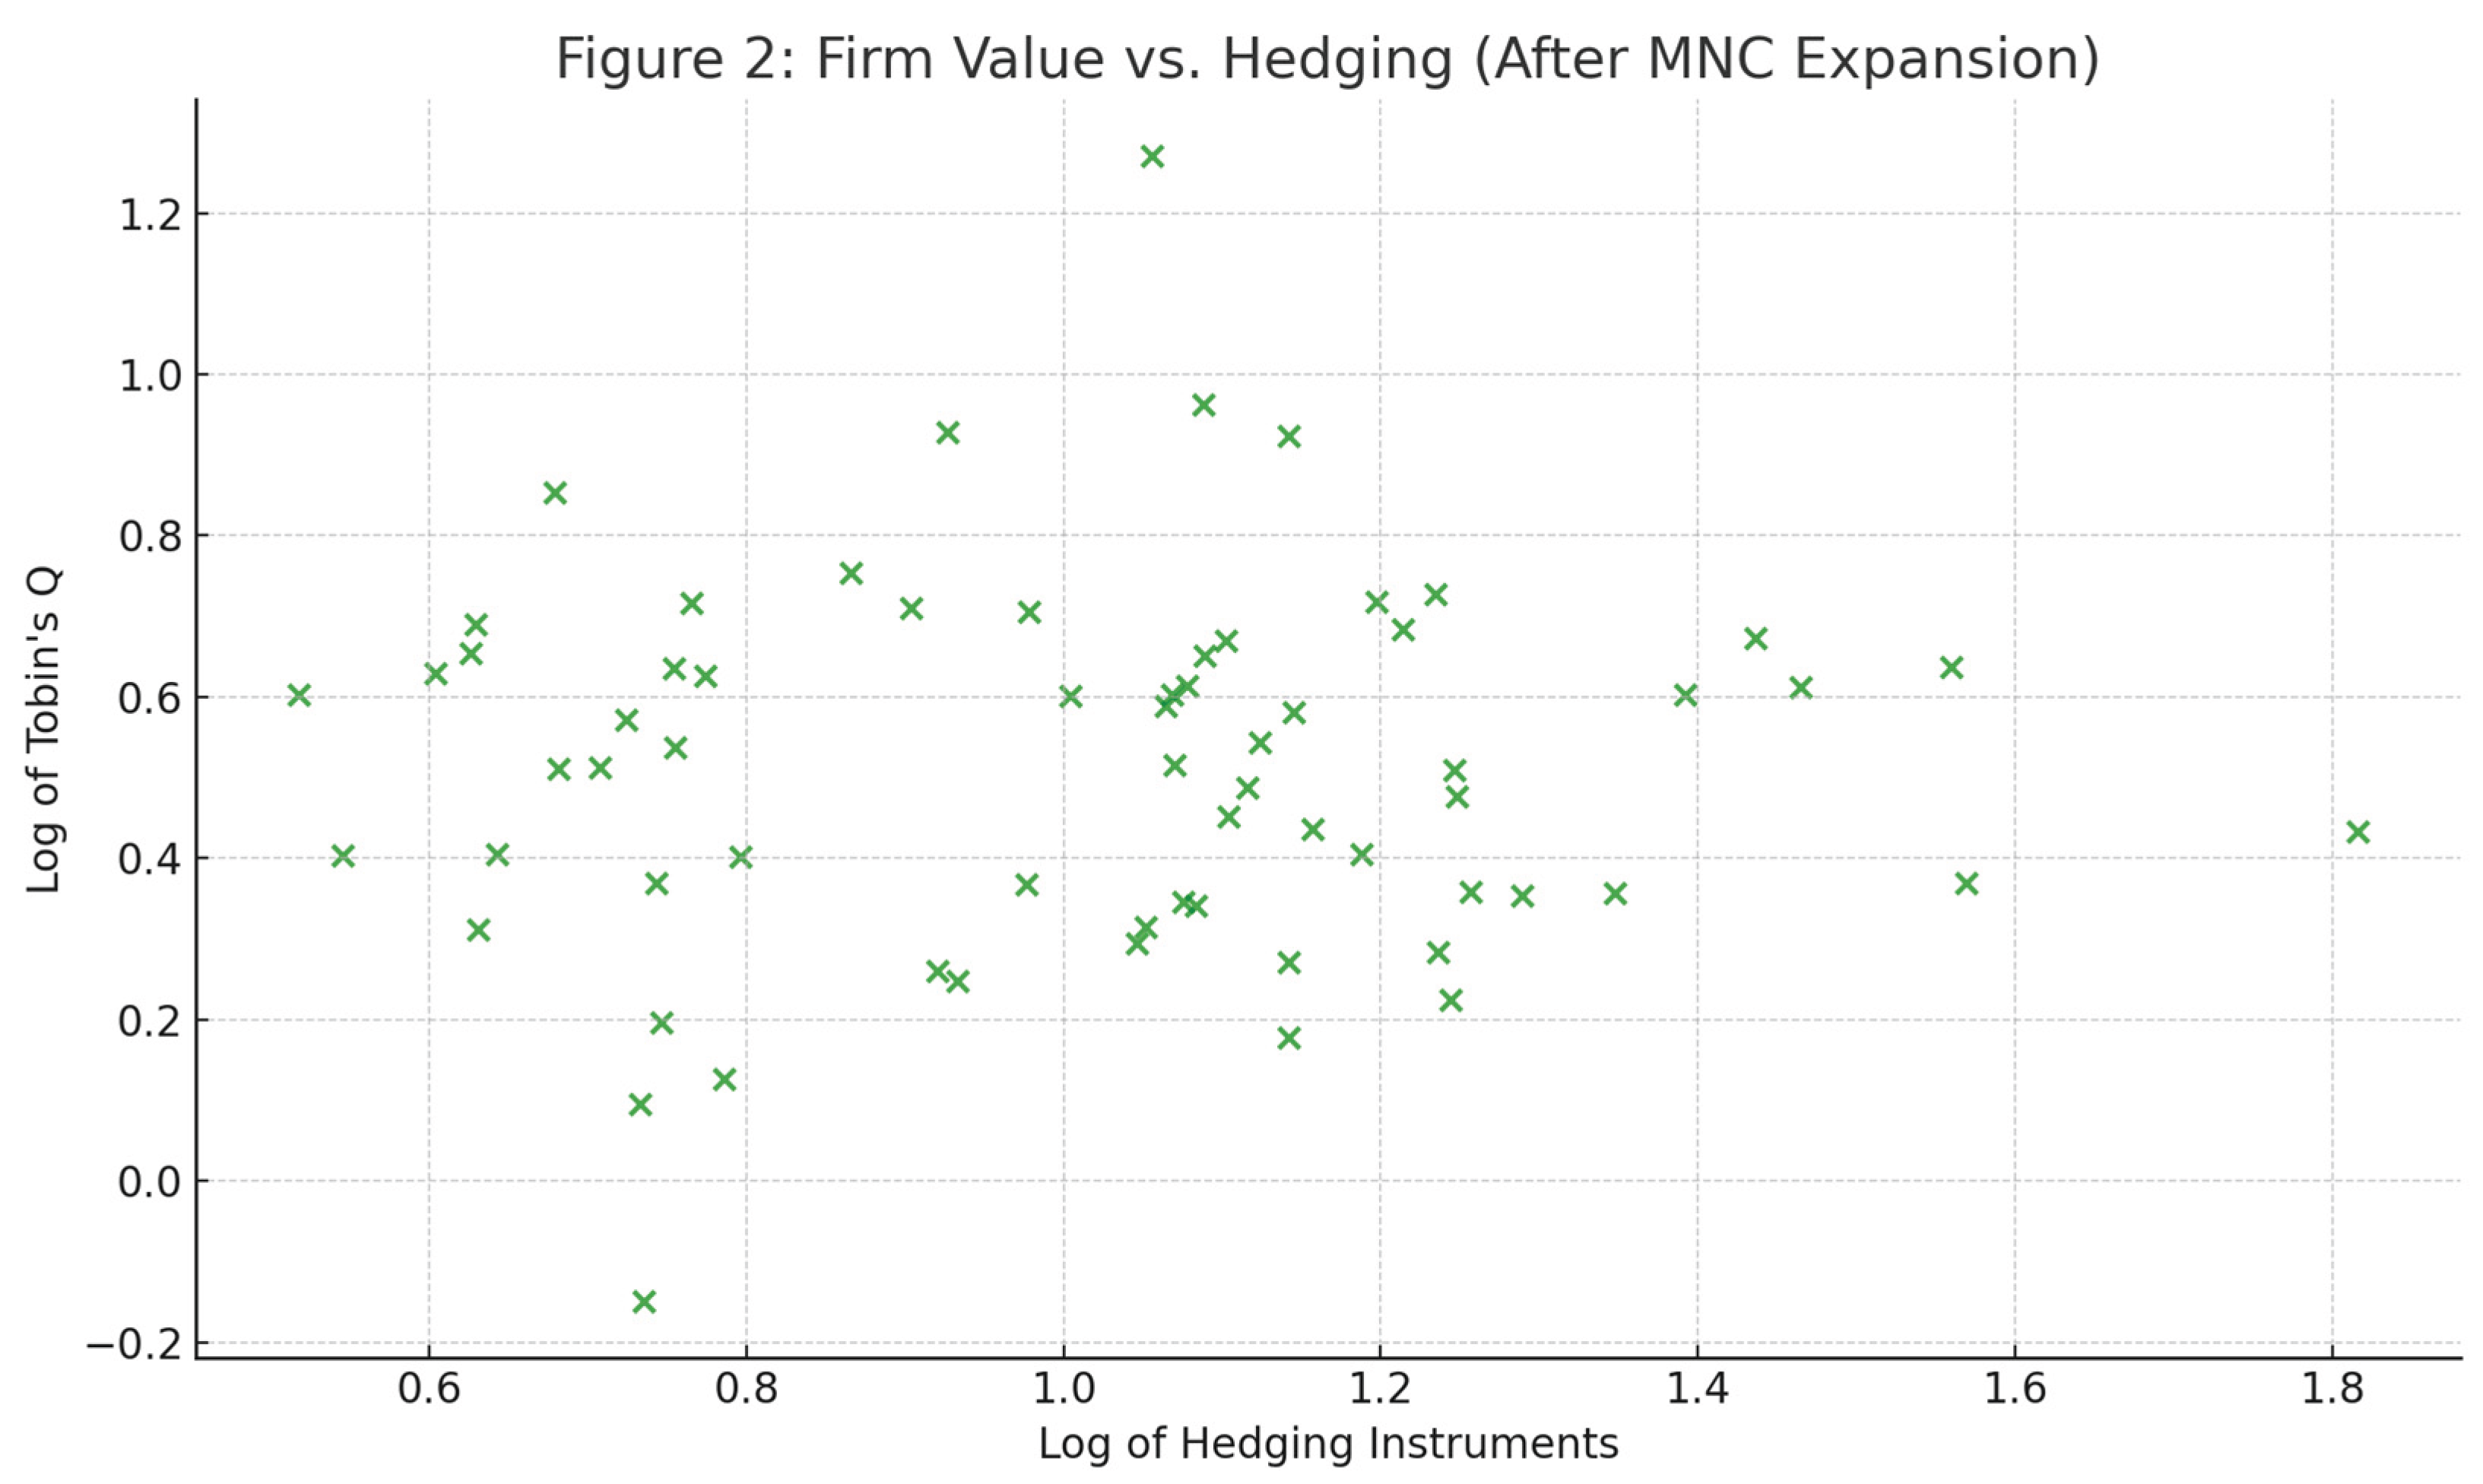
2.3. Model
3. Regression Results

| Model | Hedge_log Coefficient | Standard Error | Constant | Obs | Significance |
| Before MNC | 3.00e-09 | 1.46e-09 | -0.0994 | 66 | ** |
| After MNC | -0.0371 | 0.0479 | 0.107 | 66 | ns |
| Variable | Before MNC Coef | SE | After MNC Coef | SE |
| Hedge_log | 2.86e-09 | 1.54e-09 | 0.00553 | 0.0240 |
| Leverage_log | -0.425 | 0.0588 | -0.409 | 0.0315 |
| ROA_log | -0.0432 | 0.0252 | 0.00859 | 0.0225 |
| TotalAsset_log | 0.00858 | 0.0130 | 0.0250 | 0.0192 |
| Dividend | -0.00120 | 0.0716 | -0.193 | 0.117 |
| Constant | -0.290 | 0.161 | -0.217 | 0.241 |
| Model | R-squared | Observations |
| OLS Before MNC | 0.797 | 66 |
| OLS After MNC | 0.808 | 66 |
Discussion
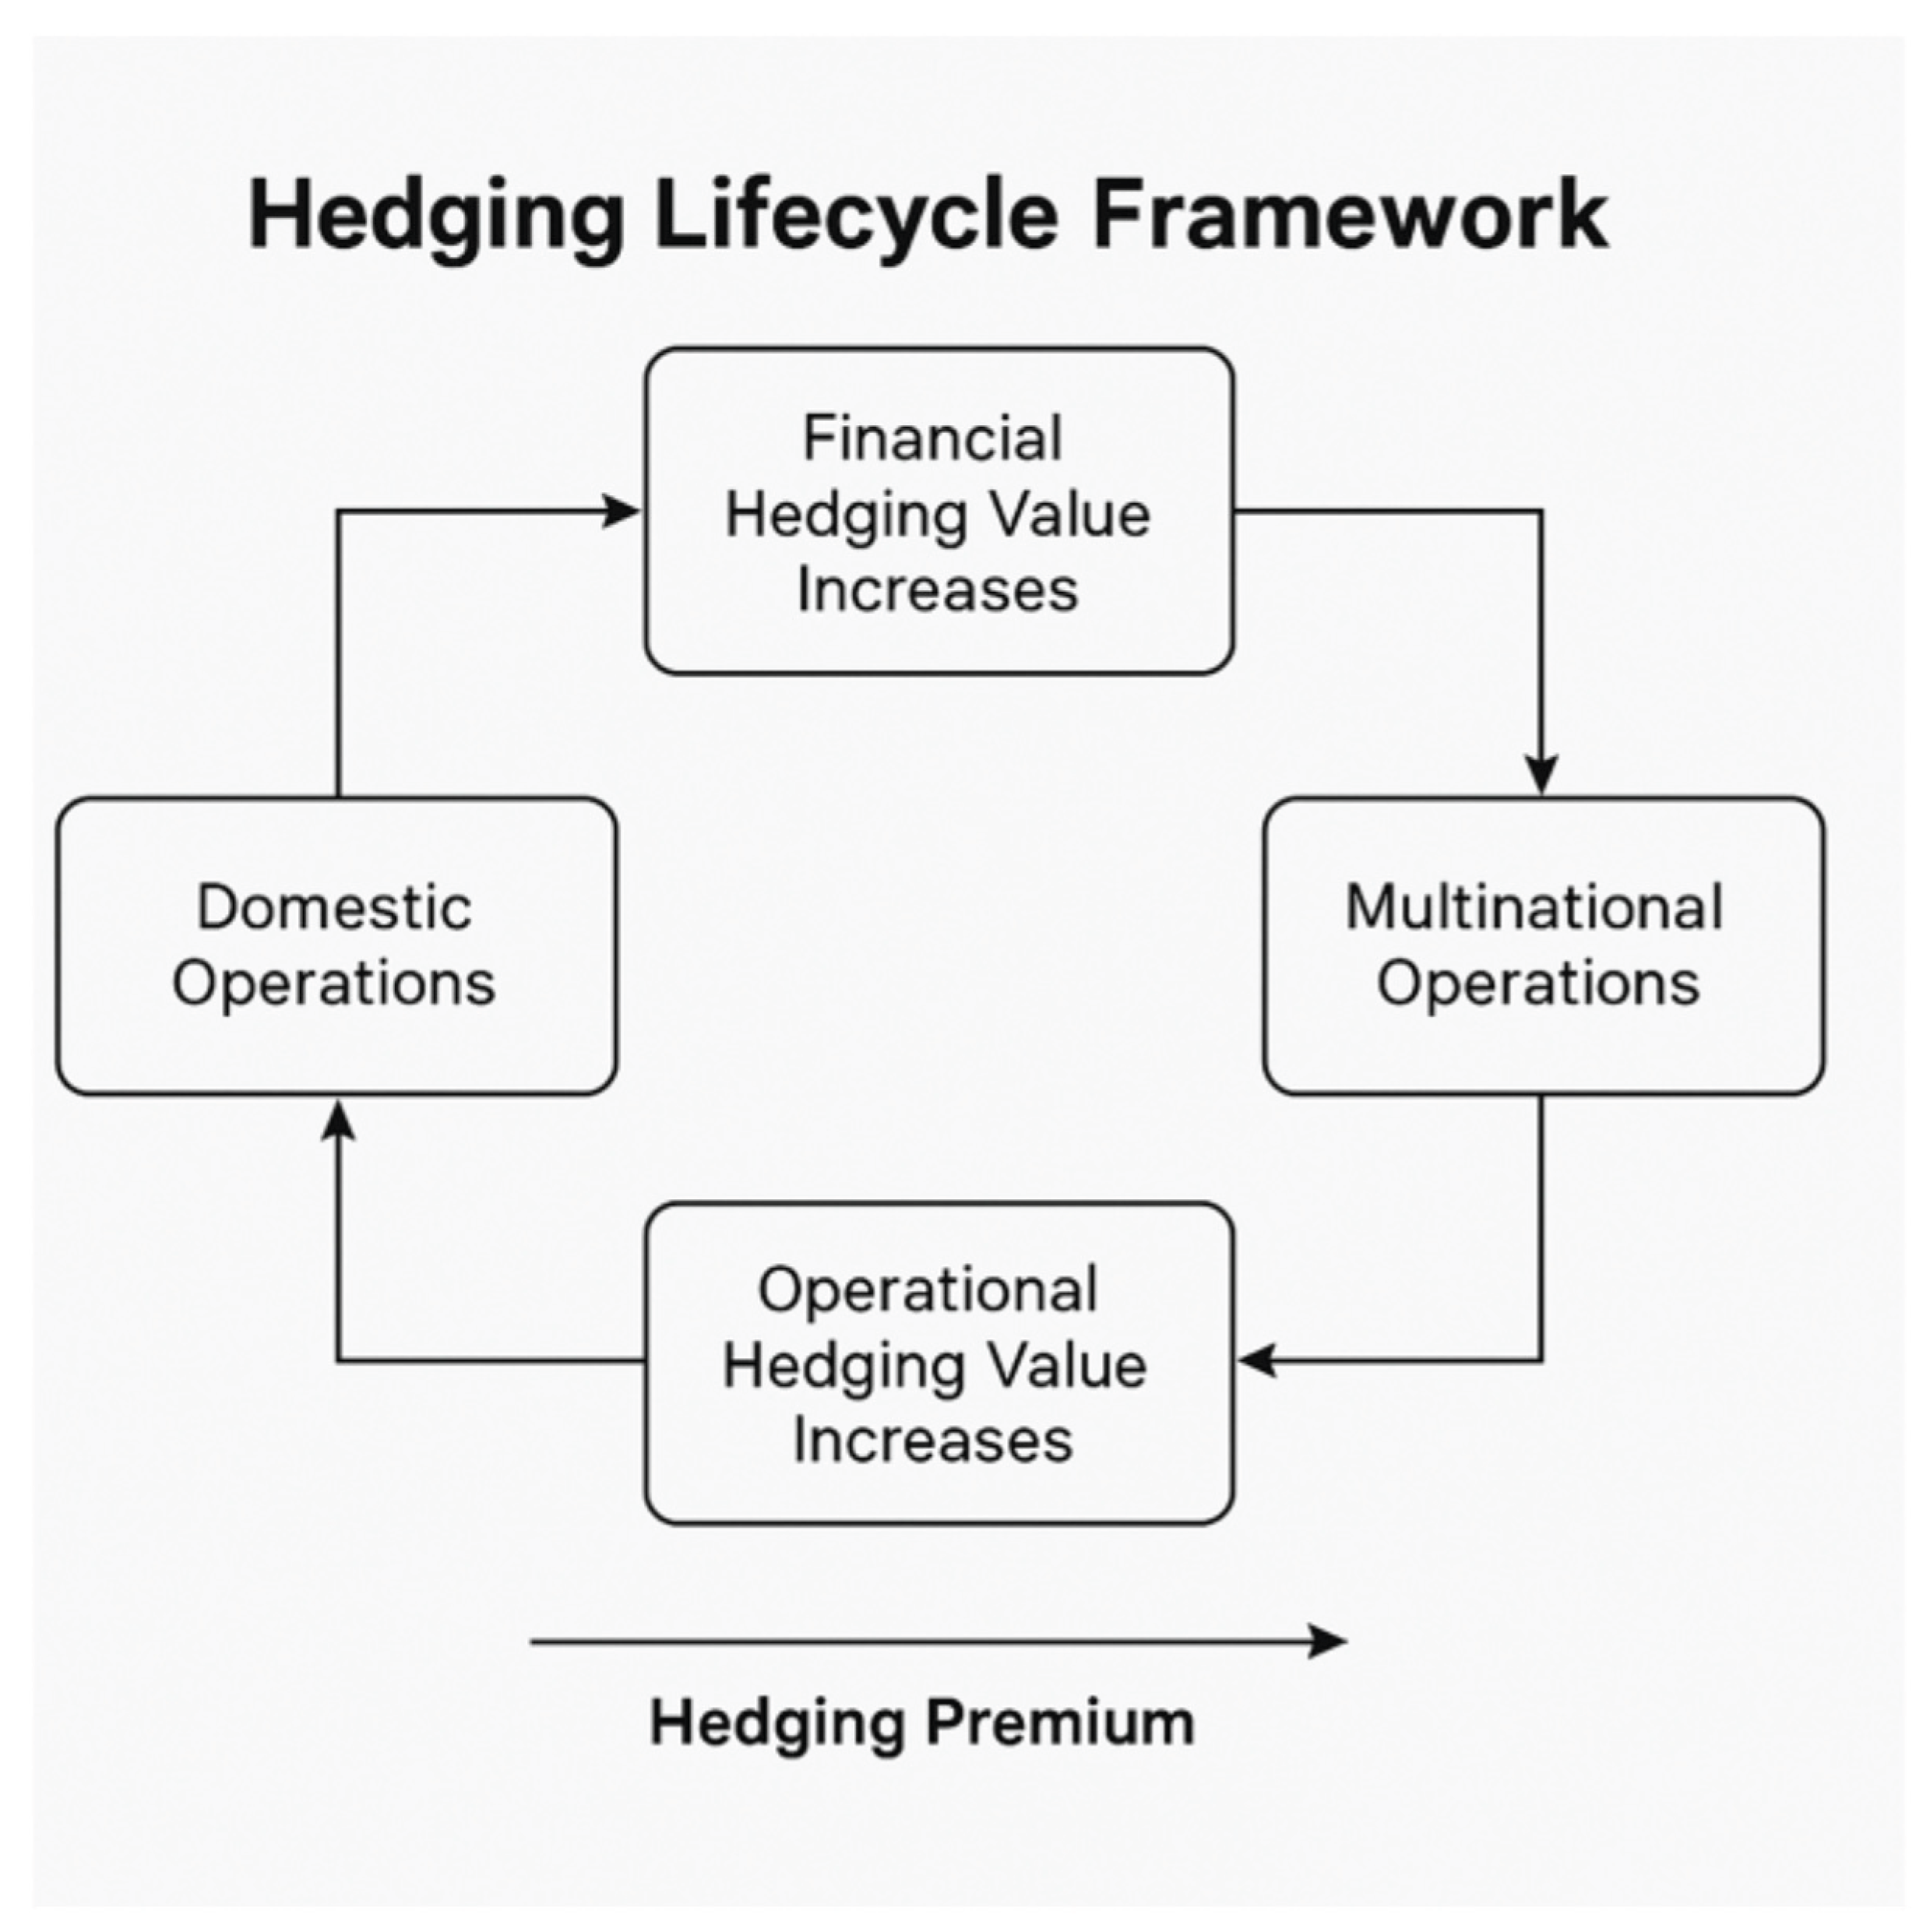
Conclusion
- Adopt a stage sensitive Hedging Policy
- 2.
- Integrate Operational and Financial Hedging Frameworks
- 3.
- Reevaluate Hedging Post-Deglobalization
- 4.
- Enhance Risk Governance and Reporting
- 5.
- Hedge Selectively Based on Firm and Industry Risk
- 6.
- Leverage Advanced Analytics in Hedging Decisions
Appendix
Appendix A: Variable Definitions and Measurement
- •
- Tobin’s Q (Q_log): Proxy for firm value, calculated as (Book Value of Total Assets - Book Value of Equity + Market Value of Equity) / Book Value of Total Assets. The natural logarithm is taken for analysis.
- •
- Hedge log: Natural logarithm of total hedging instruments reported in the 10-K filings, including currency forwards, swaps, and options.
- •
- ROA_log: Return on Assets, calculated as Net Income divided by Total Assets, expressed in natural logarithm.
- •
- Leverage_log: Natural logarithm of book value of debt divided by market value of common equity.
- •
- Total Asset log: Natural logarithm of Total Assets.
- •
- Dividend: Dummy variable equal to 1 if the firm paid dividends in the given year, 0 otherwise.
Appendix B: Descriptive Statistics (Before and After Multinational Expansion)
| Variable | N | Mean (Before) | SD (Before) | Mean (After) | SD (After) |
| Hedge | 66 | 2.03e+07 | 7.61e+07 | 96,355 | 676,620 |
| Total Asset | 66 | 1.96e+08 | 8.97e+08 | 1.87e+06 | 6.29e+06 |
| Debt | 66 | 4.05e+07 | 1.60e+08 | 618,878 | 1.89e+06 |
| Net Income | 66 | 7.66e+07 | 3.18e+08 | 213,022 | 715,225 |
| ROA | 66 | 5,567 | 43,750 | 0.433 | 1.098 |
| Leverage | 66 | 2.45 | 5.92 | 9.30 | 31.07 |
| Q | 66 | 1.99 | 5.79 | 0.864 | 4.53 |
| Dividend | 66 | 0.754 | 0.434 | 0.803 | 0.401 |
Appendix C: Regression Model Specifications
Appendix D: Diagnostic Tests and Robustness Checks
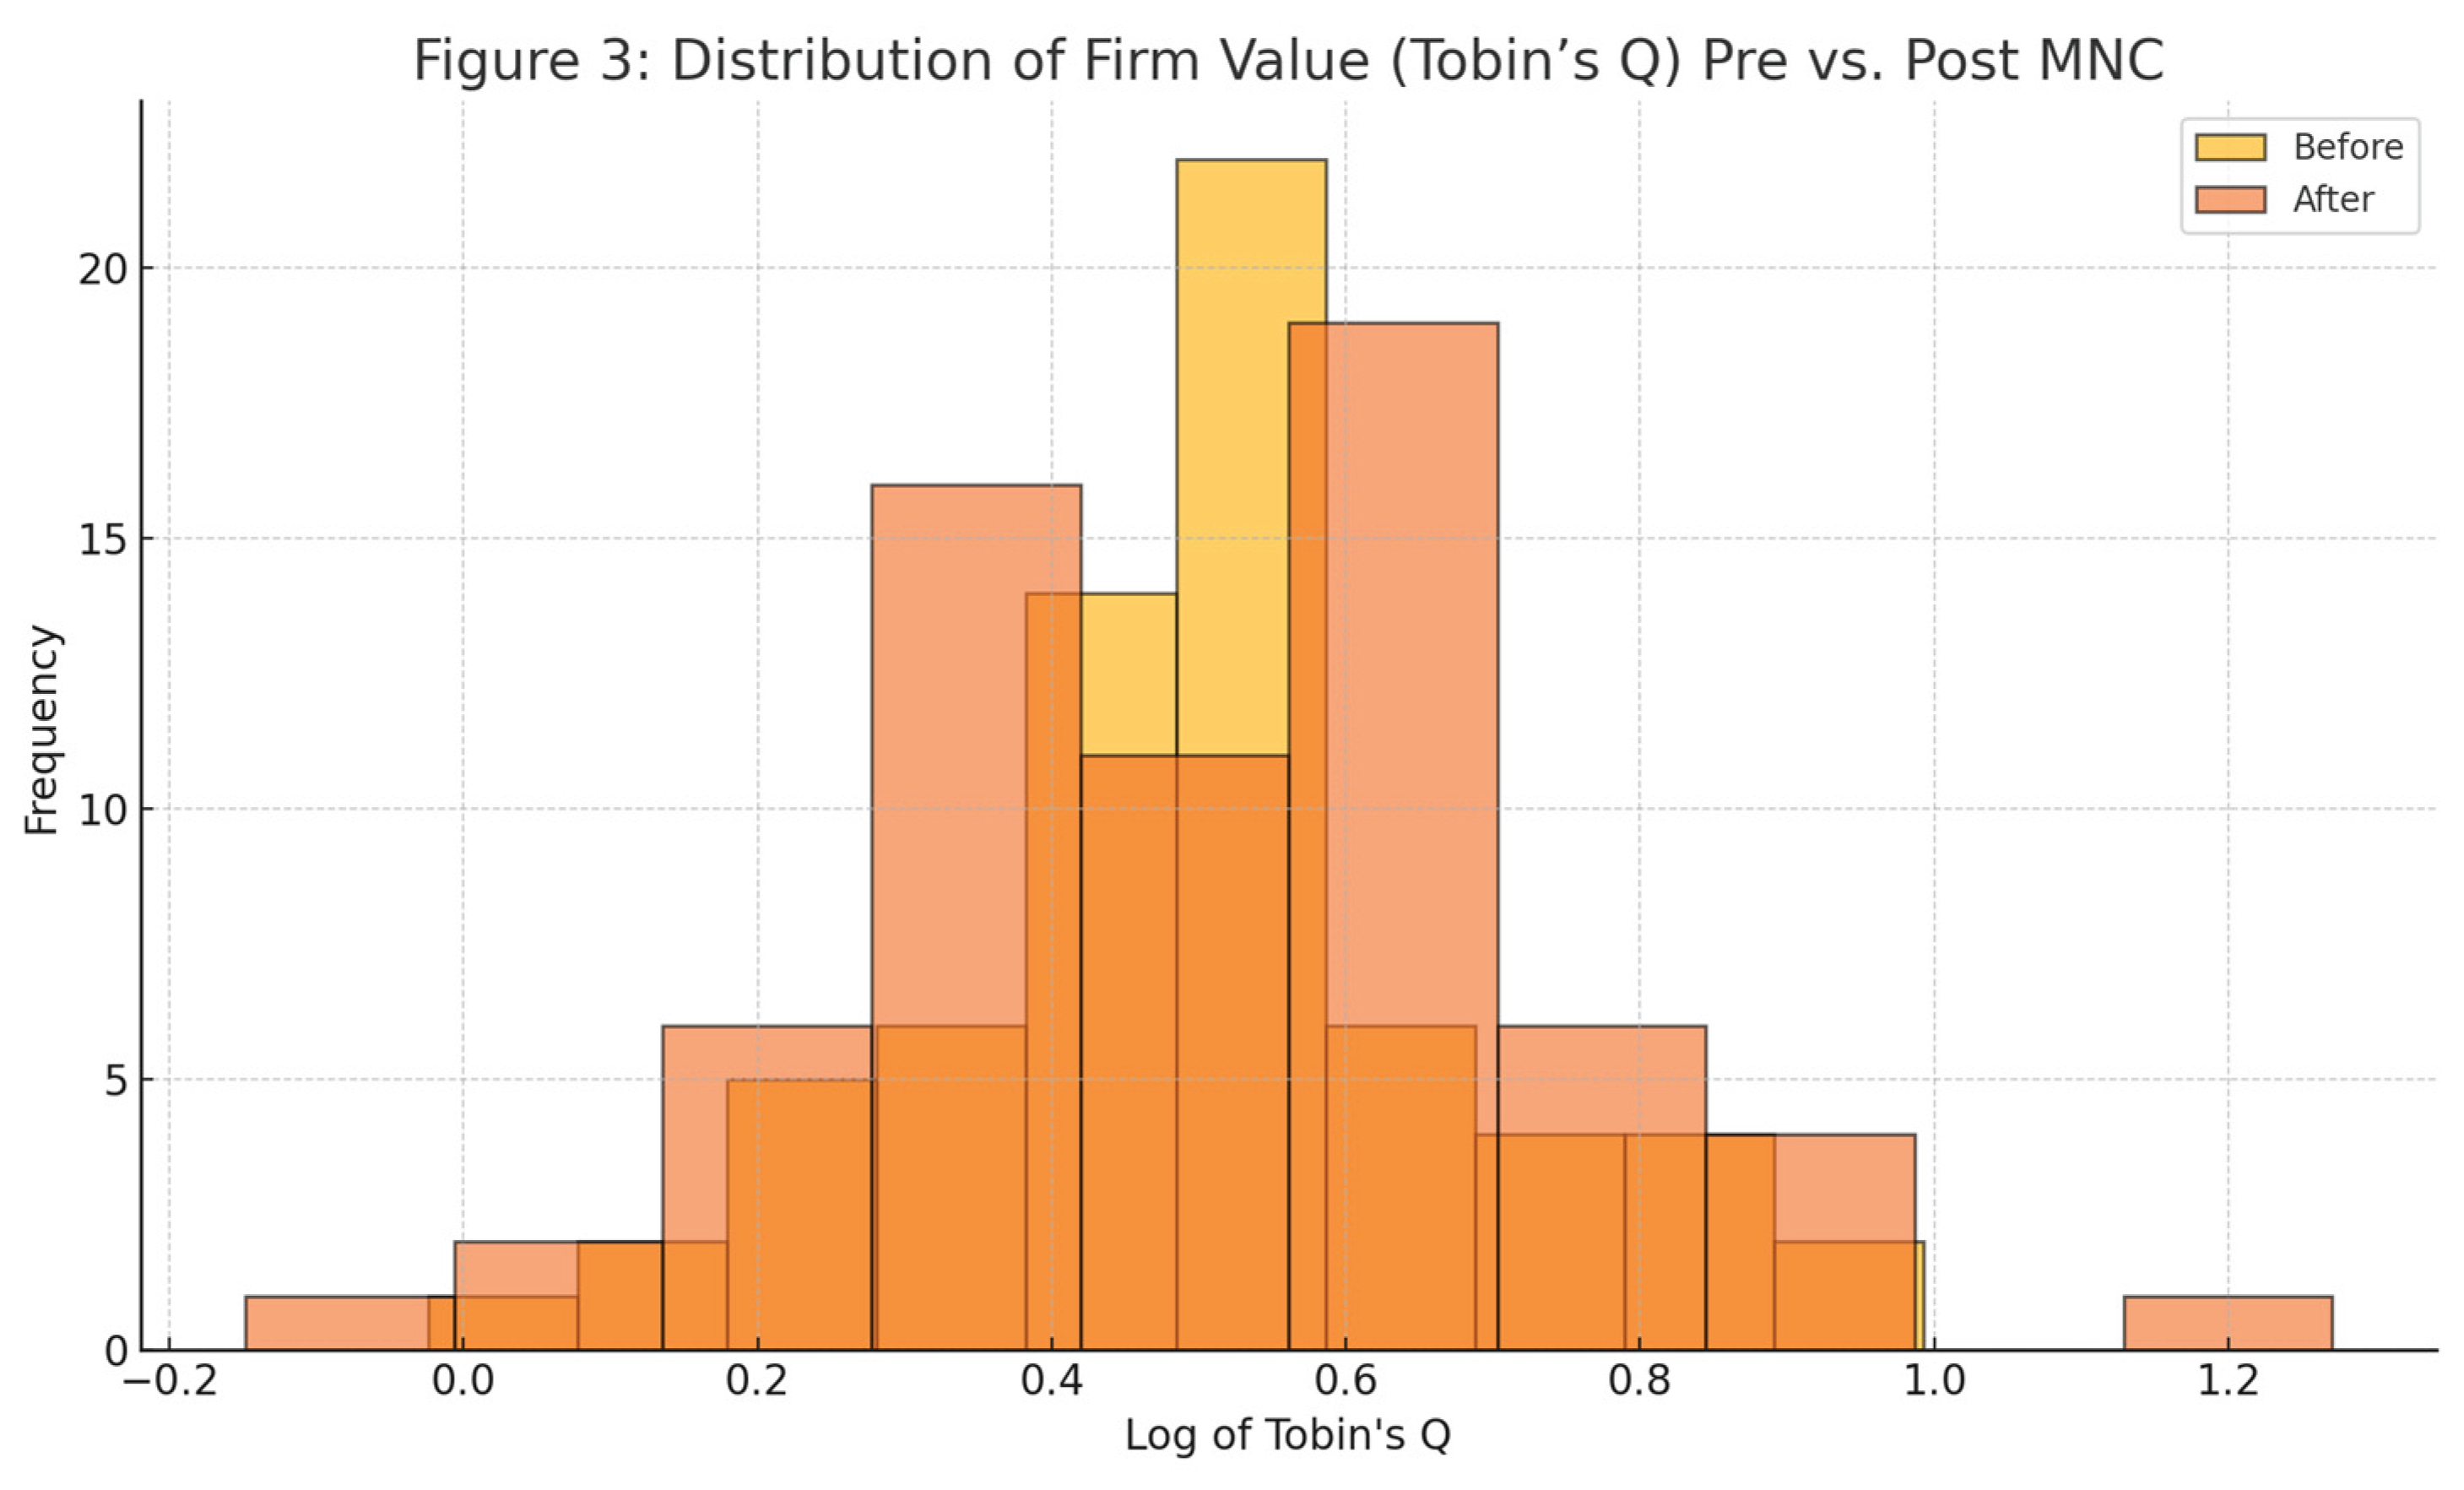
References
- Adler, M., & Dumas, B. (1984). Exposure to currency risk: Definition and measurement. Financial Management, 13, 41–50. [CrossRef]
- Akhtar, S., & Oliver, B. (2009). Determinants of capital structure for Japanese multinational and domestic corporations. International Review of Finance, 9(1-2), 1–26. [CrossRef]
- Allayannis, G., & Ofek, E. (2001). Exchange rate exposure, hedging, and the use of foreign currency derivatives. Journal of International Money and Finance, 20(2), 273–296. [CrossRef]
- Allayannis, G., & Weston, J. P. (2001). The use of foreign currency derivatives and firm market value. Review of Financial Studies, 14(1), 243–276. [CrossRef]
- Altman, E. (1983). Corporate financial distress. New York, NY: John Wiley.
- Bartram, S. M., Brown, G. W., & Conrad, J. (2011). The effects of derivatives on firm risk and value. Journal of Financial and Quantitative Analysis, 46(4), 967–999. [CrossRef]
- Bartram, S. M., Brown, G. W., & Fehle, F. (2009). International evidence on financial derivatives usage. Financial Management, 38(1), 185–206. [CrossRef]
- Brown, G. W. (2001). Managing foreign exchange risk with derivatives. Journal of Financial Economics. [CrossRef]
- Carter, D. A., Rogers, D. A., & Simkins, B. J. (2006). Does hedging affect firm value? Evidence from the US airline industry. Financial Management, 35(1), 53–87. [CrossRef]
- Cohn, J., Li, T., & Wardlaw, M. (2023). Deglobalization and corporate risk management. Journal of Financial Economics.
- Froot, K. A., Scharfstein, D. S., & Stein, J. C. (1993). Risk management: Coordinating corporate investment and financing policies. Journal of Finance, 48(5), 1629–1658.
- Géczy, C., Minton, B. A., & Schrand, C. (1997). Why firms use currency derivatives. Journal of Finance, 52(4), 1323–1354.
- Graham, J. R., & Rogers, D. A. (2002). Is corporate hedging consistent with value maximization? An empirical analysis. Journal of Finance, 57(2), 815–844.
- Guay, W. R. (1999). The impact of derivatives on firm risk: An empirical examination of new derivatives users. Journal of Accounting and Economics, 26(1-3), 319–351. [CrossRef]
- Guay, W. R., & Kothari, S. P. (2003). How much do firms hedge with derivatives? Journal of Financial Economics, 70(3), 423–461. [CrossRef]
- Jin, Y., & Jorion, P. (2006). Firm value and hedging: Evidence from U.S. oil and gas producers. Journal of Finance, 61(2), 893–919. [CrossRef]
- Jorion, P. (1990). The exchange-rate exposure of U.S. multinationals. Journal of Business, 63(3), 331–345. [CrossRef]
- Kim, Y. S., Kim, H., & Pantzalis, C. (2019). Corporate hedging, political risk, and firm value. Journal of Financial Research, 42(3), 461–494.
- Lee, K. C., & Kwok, C. Y. (1988). Multinational corporations vs. domestic corporations: International environmental factors and determinants of capital structure. Journal of International Business Studies, 19(4), 41–58. [CrossRef]
- Mian, S. L. (1996). Evidence on corporate hedging policy. Journal of Financial and Quantitative Analysis, 31(3), 419–439. [CrossRef]
- Modigliani, F., & Miller, M. H. (1958). The cost of capital, corporation finance, and the theory of investment. American Economic Review, 48(3), 261–297.
- Nance, D. R., Smith, C. W., Jr., & Smithson, C. W. (1993). On the determinants of corporate hedging. Journal of Finance, 48(1), 267–284.
- Pantzalis, C., Simkins, B., & Laux, P. (2001). Operational hedges and the foreign exchange exposure of U.S. multinational corporations. Journal of International Business Studies, 32(4), 793–812. [CrossRef]
- Schrand, C., & Unal, H. (1998). Hedging and coordinated risk management: Evidence from thrift conversions. Journal of Finance, 53(3), 979–1015. [CrossRef]
- Smith, C. W., Jr., & Stulz, R. M. (1985). The determinants of firms’ hedging policies. Journal of Financial and Quantitative Analysis, 20(4), 391–405. [CrossRef]
- Stulz, R. M. (1984). Optimal hedging policies. Journal of Financial and Quantitative Analysis, 19(2), 127–140. [CrossRef]
- Tufano, P. (1996). Who manages risk? An empirical examination of risk management practices in the gold mining industry. Journal of Finance, 51(4), 1097–1137.
- Wang, Y., & Zhou, H. (2022). Hedging and firm value during systemic crises: Evidence from the COVID-19 pandemic. Journal of Corporate Finance.
Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content. |
© 2025 by the authors. Licensee MDPI, Basel, Switzerland. This article is an open access article distributed under the terms and conditions of the Creative Commons Attribution (CC BY) license (http://creativecommons.org/licenses/by/4.0/).