
Submitted:
05 October 2026
Posted:
09 October 2026
You are already at the latest version
Abstract
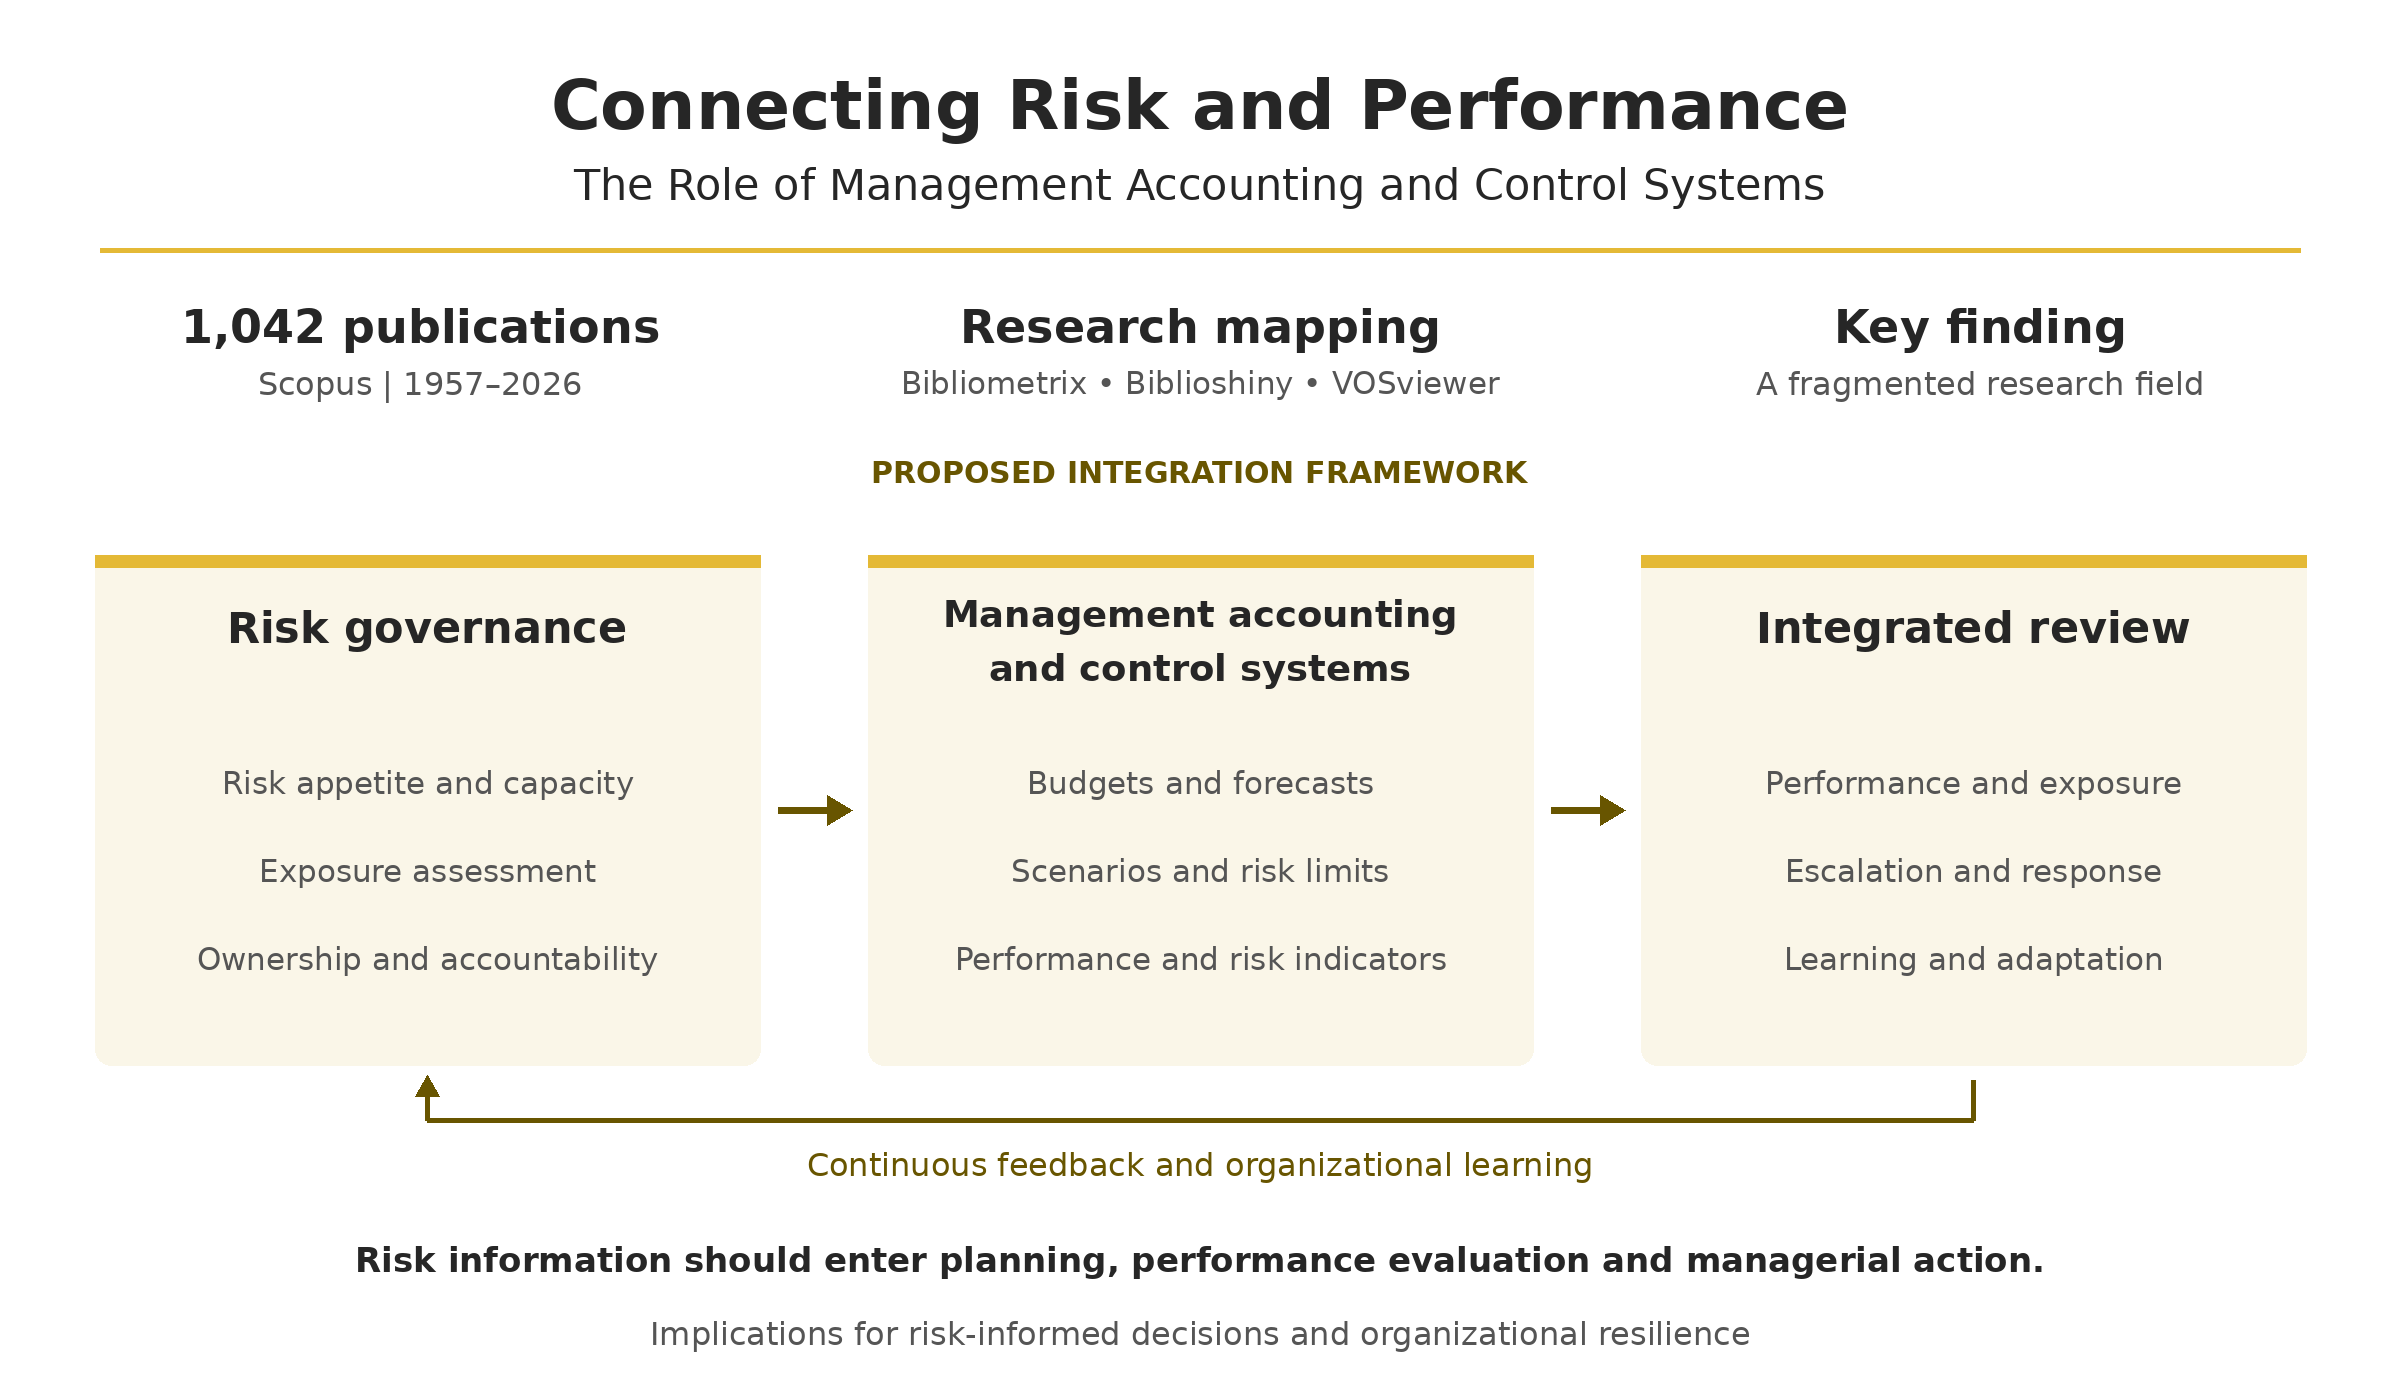
Enterprise risk management (ERM) and risk governance require organizations to connect risk identification, assessment, monitoring, and response with planning, performance evaluation, accountability, and organizational resilience. This study examines the development and intellectual structure of research at the intersection of ERM, risk governance, management accounting, and management control systems. A bibliometric analysis was conducted on 1,042 Scopus-indexed publications using Bibliometrix, Biblioshiny, and VOSviewer. The findings show sustained growth in the field and identify risk management, management control systems, and performance management as its principal motor theme. Management accounting occupies a central position in the keyword network and is closely connected with risk assessment, enterprise risk management, and performance measurement. However, the literature remains fragmented across risk governance, corporate governance, resilience, and sector-specific applications. The study therefore positions ERM and risk governance as the primary framework and interprets management accounting, control mechanisms, and information systems as enabling infrastructures through which risk information is translated into responsibilities, limits, resource-allocation decisions, corrective action, and organizational learning. The resulting framework clarifies how organizations can embed enterprise and financial risk considerations in established managerial routines rather than treating risk management as a separate reporting exercise.
Keywords:
enterprise risk management
; risk governance
; risk assessment
; management control systems
; management accounting
; financial risk
; organizational resilience
Copyright: This open access article is published under a Creative Commons CC BY 4.0 license, which permit the free download, distribution, and reuse, provided that the author and preprint are cited in any reuse.