
Submitted:
29 August 2026
Posted:
01 September 2026
You are already at the latest version
Abstract
This study examines the state- and frequency-dependent connectedness among crude oil, gold, the U.S. dollar, and the Thai equity market. Using daily data from 1 February 2008 to 31 December 2025, we combine quantile connectedness with frequency-domain decomposition to identify how market transmission changes across extreme and normal states and over short- and long-run horizons. The results reveal pronounced state dependence: system connectedness is substantially stronger in both the lower and upper tails than around the median. Gold emerges as an important net transmitter in both extreme states, although its transmission leadership changes across frequencies. In the lower tail, SET dominates short-run transmission while oil becomes the principal long-run transmitter; in the upper tail, USD leads short-run transmission whereas SET dominates at longer horizons. Most importantly, Gold–SET connectedness is negligible under normal conditions but rises sharply in both tails and remains strongly bidirectional. These findings do not support an unconditional interpretation of gold as a universally effective safe haven. Its diversification role is conditional on market state, transmission direction, and investment horizon. The results highlight the importance of state- and horizon-specific information for portfolio risk management and financial-market monitoring.
Keywords:
gold
; safe haven
; quantile connectedness
; frequency connectedness
; financial spillovers
; oil
; U.S. dollar
; Thai stock market
1. Introduction
1.1. Background and Research Motivation
Financial markets are increasingly interconnected through international trade, commodity pricing, exchange-rate movements, cross-border capital flows, portfolio rebalancing, and changes in investor risk perception. A shock originating in one market can therefore affect other markets through several channels and at different speeds. This issue is especially important for emerging economies, where domestic equity markets are exposed to global commodity prices, international liquidity, and movements in the U.S. dollar. The WTI crude-oil market, gold market, U.S. Dollar Index (DXY), and Stock Exchange of Thailand (SET) Index represent four economically distinct but interconnected dimensions of this system: global energy conditions, precious-metal risk, international currency conditions, and domestic equity-market risk. The four-market design is therefore economically motivated rather than merely statistical.
Crude oil is important because oil-price movements affect production costs, inflation expectations, transportation costs, corporate profitability, and aggregate demand. Oil shocks may originate from either supply-side disruptions or changes in global demand, and their financial consequences can therefore differ across episodes. The U.S. dollar provides an additional channel because internationally traded commodities are largely denominated in dollars. Changes in dollar strength can affect commodity valuations, the purchasing power of non-U.S. investors, international capital flows, and the valuation of emerging-market assets. These mechanisms imply that oil, gold, the dollar, and equities should not be viewed as independent markets (Diebold & Yılmaz, 2009, 2012, 2014; Baruník & Křehlík, 2018).
Gold is especially important because its conventional role as a hedge and safe haven is conditional rather than necessarily permanent. The traditional safe-haven argument suggests that investors may increase gold exposure when equity markets deteriorate because gold has historically exhibited diversification properties and can attract safe-haven demand during uncertainty (Baur & Lucey, 2010; Baur & McDermott, 2010; Beckmann et al., 2015). However, a low unconditional correlation between gold and equities does not establish that the two markets remain weakly connected during extreme events. When investors simultaneously face liquidity constraints, common information shocks, margin pressures, and rapid portfolio reallocation, previously weakly connected assets can become more synchronized.
Recent quantile-based evidence supports this concern. Mensi et al. (2024) find stronger return spillovers between oil, gold, and international stock markets during bearish and bullish conditions, with particularly intense spillovers during major stress episodes. Shang and Hamori (2024) similarly show that connectedness among crude oil, gold, financial markets, and macroeconomic indicators varies across both quantiles and time frequencies. These findings imply that an unconditional connectedness measure may conceal economically important transmission occurring in the tails.
This distinction is central to the present study. The question is not simply whether gold is correlated with the Thai stock market, nor whether gold is on average a safe haven. Rather, the relevant question is whether the transmission relationship changes when markets move toward extreme downside or upside states and whether the same relationship persists over different investment horizons. The manuscript adopts precisely this state–frequency perspective, evaluating the four-market system at τ = 0.05, 0.50, and 0.95 and then separating short- and long-run transmission.
The issue is particularly relevant for Thailand. The SET Index is an emerging-market equity benchmark influenced by global commodity prices, international capital movements, exchange-rate conditions, and global risk appetite. Thailand therefore provides a useful setting for examining whether global commodity and currency shocks are transmitted into an emerging equity market and whether the domestic market subsequently participates in the international transmission network.
1.2. From Average Dependence to State-Dependent Connectedness
A major development in the financial-spillover literature has been the movement from simple correlation analysis toward directional and network-based measures of connectedness. VAR-based studies established that shocks propagate dynamically across markets, while Pesaran and Shin (1998) provided generalized forecast-error variance decomposition that does not require a particular recursive ordering. Diebold and Yılmaz (2009, 2012, 2014) transformed this logic into a connectedness framework that separates total, directional, and pairwise spillovers.
These developments are important because financial-market transmission is multidirectional. A market may transmit shocks to some assets while simultaneously receiving shocks from others. It may also be a net transmitter over one horizon but a net receiver over another. Frequency-domain extensions therefore provide useful information that a single connectedness statistic cannot provide (Baruník & Křehlík, 2018; Baruník & Kley, 2019).
A second development concerns the conditional distribution. Standard connectedness measures describe average dynamics and can therefore obscure the economically important episodes that occur in the tails. Quantile connectedness addresses this limitation by estimating dependence at selected conditional quantiles (Ando et al., 2018). Recent evidence confirms that connectedness among oil, gold, and international equity markets rises materially in extreme market states (Mensi et al., 2024).
The present study combines these two developments. Quantiles identify the state in which transmission occurs, while frequency decomposition identifies the horizon over which transmission unfolds. The resulting framework distinguishes downside short-run, downside long-run, normal short-run, normal long-run, upside short-run, and upside long-run states.
1.3. Economic Channels Linking Oil, Gold, the Dollar, and SET
The four markets are linked through overlapping economic and financial channels. The oil channel operates through global demand, production costs, inflation, and trade balances. The dollar channel operates through international pricing, capital flows, and financial conditions. The gold channel operates through portfolio substitution and risk perception. The equity channel represents the domestic absorption of these external shocks through corporate earnings, discount rates, foreign investment, and investor sentiment.
These channels imply that transmission should not be interpreted as a simple one-way sequence from global markets to Thailand. A connectedness framework can determine whether global assets transmit risk into SET, whether SET transmits shocks back into international markets, and whether these roles change under extreme conditions.
1.4. Research Problem
The central research problem is that the safe-haven interpretation of gold may be incomplete if the Gold–SET relationship is evaluated only through unconditional dependence. A near-zero average correlation may indicate diversification potential under normal conditions while concealing strong dependence during extreme states. In addition, aggregate connectedness may hide whether transmission is predominantly short-lived or persistent.
Recent evidence reinforces this concern. Mensi et al. (2024) document stronger extreme-state spillovers, Shang and Hamori (2024) show that transmission varies jointly across quantiles and frequencies, and Biswas et al. (2024) demonstrate that geopolitical events can reorganize commodity–stock connectedness. The appropriate research question is therefore not simply whether gold is an unconditional safe haven, but when and under what transmission conditions it provides diversification value.
1.5. Research Objectives
1. To examine state-dependent connectedness among WTI crude oil, gold, the U.S. Dollar Index, and the SET Index.
2. To identify the direction and magnitude of transmission and determine which markets act as net transmitters or receivers across market states.
3. To determine whether the transmission structure differs between short-run and long-run horizons.
4. To examine whether the Gold–SET relationship is consistent with a universal safe-haven interpretation or is conditional on market state and transmission horizon.
1.6. Research Questions
RQ1: Does connectedness among oil, gold, the U.S. dollar, and the SET differ between downside, normal, and upside market states?
RQ2: Which markets are the principal net transmitters and receivers in each state?
RQ3: Does the identity of the dominant transmitter change between short-run and long-run horizons?
RQ4: Is Gold–SET transmission weak around the median but stronger in extreme states?
RQ5: Is the role of gold as a diversification or safe-haven asset conditional on market state and investment horizon?
1.7. Research Gap
Three gaps motivate the study. First, although previous research has examined commodity–equity, gold–equity, and oil–equity relationships, fewer studies integrate oil, gold, the U.S. dollar, and an emerging-market equity index within one state- and frequency-dependent system. Second, much of the safe-haven literature evaluates gold using correlations or average dependence, which can obscure tail behaviour. Third, even studies that establish stronger tail connectedness may not distinguish whether transmission is short-lived or persistent.
The contribution is therefore empirical rather than a claim of methodological invention. Quantile connectedness and frequency-domain connectedness are established methods. The novelty lies in applying them jointly to the WTI–Gold–DXY–SET network and using the resulting state–frequency structure to reconsider the safe-haven interpretation of gold for an emerging equity market. This positioning follows the manuscript's own description of the joint quantile–frequency design.
1.8. Contribution and Novelty
The study contributes in three respects. First, it provides an integrated framework linking energy, precious metals, currency, and emerging equity markets. Second, it distinguishes market state from transmission horizon, allowing the same asset to occupy different network positions depending on whether conditions are normal or extreme and whether the relevant horizon is short or long. Third, it reframes the safe-haven question from an unconditional classification toward a conditional risk-management question: when, at what horizon, and within which transmission direction does gold provide diversification value? This is consistent with recent evidence that tail and frequency information can materially alter the interpretation of financial connectedness.
1.9. Scope and Organization
The analysis uses daily observations for WTI crude oil, spot gold, the U.S. Dollar Index, and the SET Index from 1 February 2008 to 31 December 2025, producing 4,206 aligned observations for each market. Section 2 reviews the theoretical and empirical literature on cross-market transmission, gold as a hedge and safe haven, commodity–equity connectedness, quantile methods, and frequency-domain connectedness. Section 3 presents the data and methodology. Section 4 reports the empirical results, and Chapter 5 concludes with policy implications and limitations.
2. Literature Review
2.1. Theoretical Foundations of Cross-Market Transmission
The theoretical basis for cross-market transmission rests on market integration, information arrival, portfolio allocation, commodity pricing, exchange-rate effects, and investor risk management. Under the Efficient Market Hypothesis, information should be incorporated rapidly into prices, allowing shocks to propagate across integrated markets (Fama, 1970). The Adaptive Market Hypothesis provides a complementary perspective by allowing the strength of relationships to evolve as market participants and economic conditions change (Lo, 2004). This dynamic view is consistent with the present framework because transmission is not assumed to be invariant over the sample.
Portfolio theory provides another mechanism. Investors allocate capital according to expected return, risk, liquidity, and covariance. When uncertainty increases, portfolio weights may change rapidly, producing cross-market transmission even when underlying fundamentals do not change proportionately (Markowitz, 1952). During crises, liquidity constraints and deleveraging can reinforce common movements across otherwise diversified assets. This mechanism helps explain why an asset that appears weakly connected under normal conditions may become strongly connected during extreme episodes.
2.2. Gold as Hedge and Safe Haven
The literature distinguishes between a hedge and a safe haven. A hedge is an asset that is uncorrelated or negatively correlated with another asset on average, whereas a safe haven is expected to retain these properties specifically during periods of market stress (Baur & Lucey, 2010; Baur & McDermott, 2010). This distinction is crucial because the effectiveness of gold can change with the market state.
Empirical evidence does not support an unconditional safe-haven interpretation in every setting. Beckmann et al. (2015) show that gold's hedging and safe-haven properties vary across markets and regimes, while Baur and Glover (2016) emphasize the importance of the intensity and duration of stress. More recent connectedness studies reinforce this conditional interpretation. Mensi et al. (2024) find stronger oil–gold–equity spillovers in extreme states, and Mensi et al. (2025) report asymmetric and time-varying connectedness between safe-haven assets and stock markets.
This literature leads directly to the present research question. If gold is a safe haven, its relationship with SET should remain sufficiently weak or negative when equity risk becomes extreme. If Gold–SET connectedness instead rises sharply in the tails, gold may still provide diversification under normal conditions but its safe-haven properties would be conditional. The distinction matters because investors are most concerned about diversification precisely when markets experience large shocks.
2.3. Oil, Gold, and Equity-Market Connectedness
Oil and equity markets are linked through macroeconomic and financial channels. Oil-price changes affect production costs, inflation, household purchasing power, and corporate profitability. The direction of the effect depends on whether oil movements are driven by demand or supply conditions and whether the economy is an oil exporter or importer. Hanif et al. (2024) show that oil shocks and stock-market connectedness differ across major producers and consumers, while Biswas et al. (2024) document significant changes in commodity–stock connectedness during the Russia–Ukraine war.
Gold adds a different risk channel. Whereas oil is closely tied to production and demand conditions, gold is more closely associated with investor risk perception, monetary conditions, and portfolio substitution. The simultaneous inclusion of oil and gold therefore helps separate two economically different commodity channels. Mensi et al. (2024) show that both markets can be involved in strong stock-market spillovers during extreme states, although their net roles are not necessarily identical.
2.4. The U.S. Dollar as a Transmission Channel
The U.S. dollar is central to the international commodity and financial system. Because oil and gold are commonly priced in U.S. dollars, changes in dollar strength can alter their effective value for international investors. Dollar appreciation can also tighten financial conditions for emerging economies through capital flows, external financing costs, and risk appetite. These mechanisms create potential feedback among the dollar, commodities, and equities.
The dollar channel is particularly relevant when interpreting gold. Gold and the dollar can respond differently to changes in risk aversion, interest-rate expectations, and monetary conditions. A connectedness framework can therefore determine whether gold transmits shocks to the dollar, receives shocks from it, or changes role across market states.
2.5. Volatility Spillovers and Connectedness
The connectedness literature developed from VAR-based spillover analysis. Diebold and Yılmaz (2009) introduced a systematic approach to measuring return and volatility spillovers, while Diebold and Yılmaz (2012, 2014) developed a generalized connectedness framework based on forecast-error variance decomposition. The framework separates total connectedness into directional FROM and TO measures and a NET measure, allowing researchers to identify the role of each market in a transmission network.
The generalized approach of Pesaran and Shin (1998) is useful because it avoids dependence on an arbitrary Cholesky ordering. This is particularly relevant for Oil–Gold–USD–SET, where there is no compelling theoretical reason to impose one recursive ordering. Connectedness therefore provides a natural basis for examining whether shocks are transmitted from global markets into Thailand or whether the Thai market also contributes to the international network.
Time variation is another central feature. Time-varying connectedness methods allow transmission relationships to evolve, while frequency-domain methods separate short- and long-horizon spillovers (Baruník & Křehlík, 2018). These developments imply that a market's role should not be summarized by one number. It may be an important short-run transmitter but a long-run receiver, or vice versa.
2.6. Quantile Connectedness
Quantile methods extend connectedness analysis by allowing the transmission network to vary across the conditional distribution. Ando et al. (2018) develop quantile connectedness to characterize financial networks in the tails. The approach is especially suitable for risk analysis because extreme observations may contain information about contagion that is diluted by average measures.
Recent evidence strongly supports this direction. Mensi et al. (2024) find stronger connectedness between oil, gold, and international stock markets under bearish and bullish conditions. Shang and Hamori (2024) similarly show that system risk varies across quantiles and frequencies, with extreme conditions associated with higher connectedness. These studies provide direct support for evaluating the present system at the 5%, 50%, and 95% quantiles.
2.7. Frequency-Domain Connectedness
Quantile analysis identifies the state in which transmission occurs but does not by itself reveal how long transmission persists. Frequency-domain connectedness addresses this limitation by decomposing spillovers into different frequencies (Baruník & Křehlík, 2018). Short-run spillovers are associated more closely with immediate information arrival, liquidity adjustment, and rapid portfolio rebalancing, whereas long-run spillovers reflect persistent transmission through investment, macroeconomic adjustment, and sustained risk repricing.
This distinction is important for safe-haven analysis. An asset may respond strongly to a shock immediately but return rapidly to its previous position, which is different from an asset that remains connected over a long horizon. Shang and Hamori (2024) show that the roles of crude oil and gold differ across frequencies and market states. The present study follows this logic by distinguishing short-run and long-run connectedness within each quantile state.
2.8. Geopolitical and Systemic Stress
Recent literature shows that geopolitical events can reorganize financial and commodity transmission networks. Cui and Maghyereh (2024) document the influence of geopolitical risk and systemic stress on higher-order commodity connectedness. Zheng et al. (2024) show that geopolitical risk matters for extreme-risk spillover networks among strategic commodities. Biswas et al. (2024) find that the Russia–Ukraine war altered the direction of connectedness among global stock markets and commodities, including changes in the net role of crude oil.
The implication for gold is important. A financial crisis, geopolitical conflict, pandemic, monetary tightening episode, or commodity supply disruption may all generate extreme returns, but their transmission mechanisms need not be identical. Extreme downside and upside states should therefore not automatically be treated as economically symmetric. The present framework tests whether both tails exhibit elevated connectedness while allowing their directional and frequency structures to differ. The manuscript's bootstrap evidence supports the stronger conclusion that both tails differ materially from normal conditions, while the direct difference between the two tails is not statistically decisive.
2.9. Emerging Markets and Thailand
Emerging markets provide an informative setting because domestic asset prices are relatively exposed to international capital flows, commodity prices, and dollar conditions. External shocks can pass through several channels simultaneously. The SET is therefore useful for examining whether international commodity and currency shocks are absorbed by the domestic equity market and whether the domestic market becomes a transmitter during extreme conditions.
Existing evidence on Thailand and other Asian markets generally supports the importance of global commodity, currency, and equity linkages, but the literature is more fragmented than the international evidence. Studies often focus on one pair or one class of assets. The four-market specification instead treats SET as part of a broader international network and asks whether its role changes with market state and horizon.
2.10. Synthesis and Research Positioning
The literature yields five conclusions. First, financial-market transmission is multidirectional and cannot be adequately described by a single bilateral correlation. Second, volatility and tail dependence can differ substantially from average return dependence. Third, connectedness varies over time and across stress episodes. Fourth, spillovers differ across investment horizons. Fifth, gold's hedge and safe-haven properties are conditional on market state and the asset against which protection is evaluated.
These conclusions establish the rationale for the present study. A static correlation model would not identify tail dependence. A single connectedness index would not distinguish transmission direction. A time-domain measure alone would not distinguish short-lived from persistent shocks. A simple Gold–SET model would not reveal whether oil and the U.S. dollar alter gold's position within the wider network. The quantile–frequency framework addresses these limitations by evaluating the four-market system jointly across market states and horizons.
The study therefore positions itself not as a new estimator but as a focused empirical application that combines four economically meaningful markets within a unified state–frequency framework. Its central novelty is the interpretation of gold's role as conditional on both market state and transmission horizon. This positioning is consistent with the manuscript's conclusion that Gold–SET connectedness is weak around the median but substantial in both tails and that the direction and persistence of transmission change across frequencies
2.11. Conceptual Framework and Testable Expectations
The literature suggests four testable expectations. First, total connectedness should be higher at the lower and upper tails than around the median because extreme market conditions encourage common information processing, rapid portfolio adjustment, and stronger risk transmission. Second, the identity of the net transmitter should vary across states because different shocks dominate different episodes. Third, the same market may occupy different positions across short- and long-run frequencies. Fourth, Gold–SET connectedness should be stronger during extreme states than during normal conditions, implying that gold's diversification value is conditional rather than invariant.
These expectations are not treated as assumptions that must be confirmed. They are evaluated through quantile-specific total connectedness, TO/FROM/NET measures, pairwise Gold–SET transmission, frequency decomposition, and bootstrap comparisons. This is important because recent evidence does not imply that downside and upside states must be statistically identical or that one tail must always dominate the other.
2.12. Summary of the Literature Gap
Overall, the literature has moved from unconditional correlation toward dynamic, directional, tail-sensitive, and frequency-dependent measures of financial connectedness. This evolution provides a strong foundation for the present study. Nevertheless, an integrated assessment of WTI crude oil, gold, the U.S. dollar, and the Thai equity market remains useful because these markets represent distinct transmission channels and because Thailand provides an emerging-market setting in which global and domestic shocks interact. The present study fills this empirical space by asking not simply whether the markets are connected, but when they become connected, which market transmits the shocks, and how long those shocks persist.
3. Methodology and Data
3.1. Research Framework
This study employs a quantile–frequency connectedness framework to examine the state- and horizon-dependent transmission among oil, gold, the U.S. dollar, and the Thai equity market. The framework combines quantile-based analysis with frequency-domain connectedness to identify whether market integration changes across different locations of the conditional return distribution and across different investment horizons.
The motivation for this framework is that conventional unconditional dependence measures may conceal economically important relationships that emerge only during extreme market conditions. In particular, financial-market dependence may be weak around the centre of the distribution but substantially stronger in the lower or upper tails. Similarly, aggregate connectedness may combine short-lived and persistent spillovers and therefore obscure differences in the temporal structure of transmission.
For each quantile, connectedness is further decomposed into short-run and long-run frequency components. This allows the study to determine whether the identity of the principal transmitter or receiver changes according to both the market state and the persistence of shocks.
This design is consistent with the central empirical objective of the study: to move beyond an unconditional assessment of gold as a safe haven and instead determine when, at what horizon, and within which transmission structure gold becomes strongly connected with the Thai equity market.
3.2. Data Collection and Variable Definition
The empirical dataset consists of daily observations for four financial markets:
- WTI crude oil;
- Spot gold (XAU/USD);
- U.S. Dollar Index (DXY); and
- Stock Exchange of Thailand (SET) Index.
The sample covers the period from 1 February 2008 to 31 December 2025. After aligning the trading dates across markets, the final dataset contains 4,206 observations for each market.
The four markets represent economically distinct but interconnected dimensions of the international financial system. Oil represents global energy and commodity conditions, gold represents the precious-metal and safe-haven channel, the U.S. dollar represents international currency conditions, and the SET Index represents domestic equity-market risk.

Table 1.
Variables and Economic Roles.
| Variable | Market measure | Economic role |
| Oil | WTI crude oil | Global energy and commodity channel |
| Gold | Spot gold (XAU/USD) | Precious-metal and safe-haven channel |
| USD | U.S. Dollar Index (DXY) | Global currency and dollar-strength channel |
| SET | SET Index | Thai equity-market and domestic-risk channel |
Note: The four series are aligned by trading date before the return transformation and subsequent connectedness estimation.
3.3. Construction of Daily Returns
Let denote the closing price of market at time . The simple daily return is calculated as
or equivalently,
where denotes Oil, Gold, USD, or SET.
The return vector is defined as
The transformation removes the price-level component and places the four markets on a comparable scale of daily changes.
Importantly, the empirical specification uses simple daily returns rather than logarithmic returns. The purpose of the subsequent quantile–frequency analysis is to investigate the dependence structure of these returns across market states and horizons.
3.4. Quantile-Based Market States
The principal feature of the methodology is the evaluation of market dependence at different points of the conditional return distribution.
Let denote the conditional quantile of the return of market at quantile level . It can be expressed as
where:
is the quantile level;
is the conditional distribution of returns; and
represents the information available at time .
The empirical analysis focuses on
τ = 0.05
τ = 0.50
and
τ = 0.95
The interpretation is:
τ = 0.05 → extreme downside state
τ = 0.50 → median / normal state
τ = 0.95 → extreme upside state
This specification is particularly relevant because the descriptive statistics indicate substantial negative skewness and excess kurtosis, especially for Oil and SET. Such characteristics suggest that the dependence structure may differ substantially between normal and extreme market conditions.
3.5. Quantile Vector Autoregression (QVAR)
For each quantile state, the conditional dynamics of the four-dimensional return vector are modeled using a Quantile Vector Autoregression (QVAR) specification.
For each quantile , the conditional dynamics of the -dimensional return vector can be represented as
where:
= vector of market returns
= quantile-specific intercept vector
= quantile-specific coefficient matrix at lag = vector of innovations
= lag order
The important feature is that the transmission parameters are evaluated conditional on the quantile state. Therefore, in general
This means that the transmission mechanism during extreme downside conditions does not have to be identical to the transmission mechanism observed under normal or extreme upside conditions.
3.6. Moving-Average Representation
The dynamic system can be expressed in moving-average form as
where
and represents the dynamic response of the system to an innovation at horizon .
The moving-average representation provides the basis for decomposing forecast-error variance into contributions originating from the different markets.
3.7. Generalized Forecast-Error Variance Decomposition
The study uses generalized forecast-error variance decomposition (GFEVD) following Pesaran and Shin (1998) and Diebold and Yılmaz (2014).
Let denote the forecast horizon. The generalized contribution of shocks from market to the forecast-error variance of market is
where:
= contribution of market j to market i
= variance of innovation j
= moving-average coefficient matrix
= covariance matrix of innovations
= selection vector for market i
= forecast horizon
The generalized decomposition is preferable to an ordering-dependent Cholesky decomposition because it does not require an arbitrary ordering of the markets (Pesaran & Shin, 1998; Diebold & Yılmaz, 2014).
3.8. Normalization of Variance Decomposition
Because the generalized variance decomposition does not necessarily sum to one across all shocks, the elements are normalized as follows:
Therefore, for each market .
The normalized decomposition can subsequently be interpreted as the percentage contribution of shocks from market to the forecast-error variance of market .
3.9. Total Connectedness Index
The Total Connectedness Index (TCI) measures the proportion of forecast-error variance attributable to shocks originating from other markets.
The quantile-specific TCI is defined as
A higher value of indicates stronger overall cross-market connectedness, while a lower value indicates weaker transmission.
For the frequency-domain analysis, the corresponding frequency-specific TCI is
where represents a particular frequency band.
The empirical analysis therefore produces TCI measures for each combination of market state and transmission horizon.
3.10. Frequency-Domain Connectedness
To distinguish temporary from persistent transmission, the study follows the frequency-domain connectedness framework developed by Baruník and Křehlík (2018).
Let denote a frequency band. The generalized variance contribution within frequency band is represented by
where:
= frequency
= frequency band
= frequency-domain transfer function
= covariance matrix of innovations
= conjugate transpose
The frequency decomposition allows total connectedness to be divided into different temporal components.
In this study, the empirical interpretation focuses on two broad components:
Short-run component → rapidly transmitted shocks
Long-run component → persistent shocks
The importance of this decomposition is that the same market can occupy different roles depending on the horizon. The empirical results confirm this pattern: SET is the strongest short-run transmitter in the downside tail, whereas Oil becomes the strongest long-run transmitter; in the upper tail, USD leads short-run transmission while SET dominates the long run.
3.11. Directional Connectedness
Three directional measures are calculated: FROM, TO, and NET.
FROM connectedness
The volatility received by market from all other markets is
A high FROM value indicates that market receives a substantial amount of shocks from the rest of the system.
TO connectedness
The volatility transmitted by market to all other markets is
A high TO value indicates that market is an important source of shocks to other markets.
NET connectedness
Net directional connectedness is defined as
Therefore,
> 0 → net transmitter
< 0 → net receiver
= 0 → balanced position
These measures are central to identifying the changing roles of Oil, Gold, USD, and SET within the transmission network. The empirical results show, for example, that Gold has a positive aggregate NET position in both extreme tails, whereas the dominant transmitter changes when the frequency dimension is introduced.
3.12. Pairwise Directional Connectedness
To investigate individual transmission channels, pairwise connectedness from market to market is defined as
For the Gold–SET relationship:
The difference between the two directions can be represented as
A positive value indicates stronger Gold-to-SET transmission, whereas a negative value indicates stronger SET-to-Gold transmission.
This pairwise analysis is important because a positive aggregate NET position for Gold does not necessarily imply that Gold unilaterally dominates SET. Indeed, the empirical results show that Gold–SET connectedness is strongly bidirectional in both tails.
3.13. Short-Run and Long-Run Directional Connectedness
For the short-run frequency band , net directional connectedness is calculated as
For the long-run frequency band ,
Thus, a market may satisfy
which means that the market transmits shocks in the short run but receives shocks in the long run. This possibility is central to the concept of role switching. The empirical results demonstrate that transmission leadership is neither state invariant nor horizon invariant.
3.14. Quantile–Frequency Interaction
The principal analytical object of the study is the joint state–frequency connectedness:
where:
= market state
= transmission frequency
The empirical design therefore generates a connectedness matrix for each combination of:
And
Conceptually, the complete system can be represented as
This produces six principal analytical states:
| Market state | Short run | Long run |
| τ = 0.05 | Downside short-run | Downside long-run |
| τ = 0.50 | Normal short-run | Normal long-run |
| τ = 0.95 | Upside short-run | Upside long-run |
This two-dimensional structure is the central analytical contribution of the empirical design because it distinguishes the state in which transmission occurs from the horizon over which transmission persists.
3.15. Robustness and Supplementary Analysis
Several robustness exercises are conducted.
3.15.1. Alternative Quantile Specification
Additional results for the intermediate quantiles τ = 0.25 and τ = 0.75 are reported in Appendix B (Table B1), providing a compact check that the tail pattern is not driven only by the three focal quantiles.
The main analysis uses
while the robustness analysis considers
This allows the analysis to determine whether the observed tail effect represents a broader distributional pattern rather than being driven only by the two extreme quantiles.
The results support the interpretation that connectedness becomes substantially stronger as the system moves away from the centre of the distribution.
3.15.2. Supplementary Frequency Evidence
The complete frequency-specific TO/FROM results for the focal quantiles are provided in Appendix C (Table C1), allowing the directional evidence underlying the main-text interpretation to be inspected without expanding the main tables.
The analysis also examines connectedness separately across short- and long-run frequency components.
The purpose of this supplementary analysis is to show how the aggregate connectedness results are distributed across short- and long-run frequencies and to make the directional evidence underlying the role-switching interpretation transparent.
The results indicate that the dominant transmitter changes across horizons. Therefore, frequency aggregation can conceal economically relevant differences in the transmission structure.
3.15.3. Alternative Dependence Measures
Supplementary visual material is consolidated in Appendix D to extend the main figures without duplicating the principal tables.
As a complementary diagnostic, unconditional dependence is examined using Pearson, Kendall, and Spearman correlations.
The Pearson correlation between Gold and SET, for example, is close to zero, while the quantile–frequency analysis identifies substantial Gold–SET transmission in both tails.
This comparison provides an important methodological test:
Thus, conventional correlation measures and quantile–frequency connectedness capture different dimensions of the market relationship.
3.15.4. Block-Bootstrap Inference
The full block-bootstrap results are retained in the main text because they provide direct inference for the central state-comparison claims; they are not repeated in the appendices.
To assess the sampling stability of differences in connectedness across market states, the study uses a block-bootstrap procedure.
Let denote the number of bootstrap replications. For each replication , the difference between two quantile-specific TCI measures is
where the superscript denotes a bootstrap sample.
The bootstrap confidence interval is obtained from the empirical distribution of the bootstrap differences:
The analysis uses:
B = 500
successful bootstrap replications and a block length of five observations.
The principal comparisons are:
The results show that both extreme states differ strongly from the median state, whereas the difference between the two extreme states themselves is not statistically decisive.
3.16. Empirical Implementation
The empirical procedure can be summarized as follows.
Step 1: Align the daily price observations of Oil, Gold, USD, and SET.
Step 2: Calculate simple daily returns:
Step 3: Examine the distributional characteristics of the return series.
Step 4: Estimate the dependence structure at
Step 5: Calculate generalized forecast-error variance decompositions.
Step 6: Normalize the variance-decomposition matrices.
Step 7: Calculate total connectedness.
Step 8: Calculate directional TO, FROM, and NET connectedness.
Step 9: Decompose connectedness into short-run and long-run frequencies.
Step 10: Calculate pairwise Gold–SET transmission.
Step 11: Compare market roles across quantiles and frequencies.
Step 12: Conduct robustness checks using alternative quantiles, frequency decomposition, alternative dependence measures, and block bootstrap.
This procedure directly corresponds to the empirical structure reported in the results section, where the study first establishes distributional properties, then examines overall quantile-dependent connectedness, directional transmission, frequency-dependent transmission, Gold–SET transmission, state–frequency role switching, and robustness.
3.17. Link between Methodology and Research Questions
The methodology is directly linked to the research questions of the study.
| Research question | Method |
| Does connectedness vary across market states? | Quantile-specific TCI |
| Which market is a transmitter or receiver? | TO, FROM, NET |
| Does transmission differ by horizon? | Frequency-specific connectedness |
| Is Gold–SET transmission one-way or two-way? | Pairwise directional connectedness |
| Does Gold change its role across states? | Quantile-specific NET |
| Does Gold change its role across horizons? | Frequency-specific NET |
| Are extreme-state findings robust? | Alternative quantiles + bootstrap |
The methodology therefore allows the study to address the central question of whether gold should be regarded as a universally effective safe haven. Rather than imposing an unconditional classification, the framework evaluates the role of gold conditional on the market state and transmission horizon. This interpretation is consistent with the empirical conclusion that Gold–SET connectedness is negligible around the median but becomes substantial in both tails.
4. Empirical Results and Discussion
4.1. Descriptive Statistics and Preliminary Dependence Analysis
Table 2 provides the distributional characteristics of the four return series prior to examining their connectedness across market states and frequency horizons. Rather than focusing only on average movements, the table highlights the substantial heterogeneity in the distributional behaviour of the four markets.
Oil exhibits the greatest unconditional variability, with a standard deviation of 0.0239, more than four times that of USD (0.0049). Gold and SET display intermediate levels of variability, with standard deviations of 0.0116 and 0.0113, respectively. This difference indicates that the four markets enter the transmission network with markedly different levels of intrinsic return uncertainty.
More importantly for the subsequent quantile analysis, the distributions display pronounced asymmetry and tail thickness. Oil and SET exhibit particularly large kurtosis values of 16.0513 and 15.8423, respectively. Their negative skewness values (−0.7129 for Oil and −0.9994 for SET) further indicate that extreme negative movements are disproportionately important relative to positive movements. Gold also exhibits negative skewness and substantial excess tail behaviour, although less pronounced than Oil and SET. USD has the lowest unconditional variability and comparatively weaker asymmetry, but its kurtosis of 5.1352 still indicates departures from a thin-tailed distribution.
The quartile statistics provide an additional indication that the distributions are not adequately represented by their means alone. For example, the median return of Oil is close to zero, whereas its minimum and maximum values extend to −0.2798 and 0.1908, respectively. A similar pattern is observed for SET, whose distribution combines a near-zero median with exceptionally large negative observations. Consequently, the behaviour observed in the central part of the distribution may provide an incomplete representation of the dependence structure during extreme market conditions.
This distributional evidence is important for the empirical strategy adopted in this study. If volatility transmission were homogeneous across market states, an unconditional connectedness measure would provide a sufficient summary of the four-market system. However, the substantial tail asymmetry observed particularly in Oil and SET suggests that the transmission mechanism may differ between relatively adverse, normal, and favourable market states. The descriptive evidence therefore motivates the use of a quantile-based framework in which the transmission network can be evaluated separately at the lower tail, median, and upper tail of the conditional return distribution.
In this respect, the purpose of the quantile analysis is not simply to identify whether the markets are connected, but to determine whether the architecture of that connectedness changes when markets move from extreme downside conditions to normal conditions and then to extreme upside conditions. This distinction forms the basis for the quantile–frequency analysis presented in the following sections.
Why the Distributional Evidence Matters for Quantile–Frequency Connectedness
The descriptive results suggest that market transmission should not be interpreted as a single unconditional process. The pronounced negative skewness and excess kurtosis indicate that extreme observations contain information that can be obscured when the entire return distribution is compressed into a single average measure. This issue is particularly relevant for the SET and Oil markets, where the lower tail is substantially more pronounced than the central part of the distribution.
Accordingly, the empirical analysis distinguishes three market states:
τ = 0.05: extreme downside conditions;
τ = 0.50: median or normal market conditions;
τ = 0.95: extreme upside conditions.
The analysis then combines these market states with two frequency components, namely the short-run (1–2 periods) and long-run (2–∞ periods) transmission channels. This allows the study to distinguish between two dimensions that are normally aggregated in conventional connectedness measures: where in the return distribution the transmission occurs and over what investment horizon it operates.
This distinction is central to the contribution of the present analysis. A transmission channel that appears weak around the median may become substantially stronger in the lower or upper tail. Similarly, a large aggregate spillover may be predominantly short-lived rather than representing persistent long-run dependence. The quantile–frequency framework therefore provides a more granular representation of the four-market network than a single full-sample connectedness statistic.
4.2. Overall Quantile-Dependent Connectedness
4.2.1. System-Wide Connectedness across Market States
The quantile–frequency analysis reveals a pronounced state dependence in the connectedness of the four-market system. Rather than remaining broadly stable across the return distribution, market connectedness changes substantially between the lower tail, the median state, and the upper tail. This finding indicates that the interaction among oil, gold, the U.S. dollar, and the Thai equity market becomes particularly relevant when markets move away from their central distribution.
At the lower quantile (τ = 0.05), the system exhibits substantial connectedness, with the frequency-specific total connectedness measure reaching a markedly higher level than that observed at the median. A similarly elevated level is observed at the upper quantile (τ = 0.95). In contrast, connectedness around the median (τ = 0.50) is extremely limited. The resulting pattern indicates that the four markets are not uniformly integrated throughout the return distribution; instead, their interdependence intensifies under extreme market conditions.
This contrast is particularly important because the median state would suggest only weak interaction among the markets if considered in isolation. The quantile results demonstrate that such an interpretation would be incomplete. The stronger connectedness observed in both tails indicates that market shocks become more strongly interconnected when the system enters unusually adverse or favourable conditions.
The lower and upper tails, however, should not be interpreted as economically identical states. Although both exhibit substantially stronger connectedness than the median, the composition of transmission differs across frequencies and market participants. This distinction becomes clearer when directional and frequency-specific connectedness are examined in the subsequent sections.
The evidence therefore provides the first central result of the analysis: market integration in the Oil–Gold–USD–SET system is strongly state-dependent, with substantially greater interconnectedness occurring at distributional extremes than under normal market conditions. This result motivates the next analysis, which identifies the markets responsible for generating and absorbing these shocks.
4.2.2. Directional Connectedness and Net Transmission
Table 3 presents the directional results, making the state dependence more apparent. At the lower tail (τ = 0.05), gold records the largest positive total NET value among the four markets (1.2959), indicating that it acts as a net transmitter within the system. In contrast, SET records a negative NET value of −0.8457, identifying the equity market as an important net receiver. Oil also remains a net receiver overall (−0.4784), while the U.S. dollar is approximately balanced, with a NET value of 0.0282.
The upper tail presents a related but not identical configuration. Gold again records the largest positive NET value, increasing to 1.4223, while the U.S. dollar also becomes an important net transmitter with a value of 1.3290. Oil and SET remain net receivers, with NET values of −1.5458 and −1.2055, respectively. Thus, gold's positive net transmission position persists across both extreme tails, while the role of the U.S. dollar becomes more pronounced under extreme upside conditions.
By comparison, the median state produces almost no economically meaningful net transmission. NET values are close to zero for all four markets: 0.0050 for oil, −0.0479 for gold, 0.0117 for USD, and 0.0312 for SET. This provides a sharp contrast with the two tails and reinforces the conclusion that the transmission network cannot be adequately characterized by its behaviour around the centre of the distribution.
Importantly, the directional results also demonstrate that identifying a single permanent transmitter or receiver would be misleading. Gold is the strongest net transmitter when total connectedness is considered at both tails, but the identity of the dominant transmitter changes once the frequency dimension is introduced. At τ = 0.05, SET becomes a strong short-run transmitter while oil becomes the dominant long-run transmitter. At τ = 0.95, the short-run transmission is led by USD, whereas SET becomes the strongest long-run transmitter. These changes indicate that the structure of the network depends jointly on market state and transmission horizon.
Taken together, the directional evidence suggests that extreme market conditions do not simply increase the magnitude of connectedness; they also reorganize the roles played by individual markets within the transmission network. Gold consistently occupies an important transmitting position in the aggregate tail structure, but the underlying source and destination of shocks vary considerably across horizons. This state-dependent role switching is examined in greater detail in Section 4.3.
4.3. Frequency-Dependent Connectedness across Market States
4.3.1. Short-Run Transmission
The short-run transmission structure varies markedly across market states. Under normal conditions (τ = 0.50), net transmission remains close to zero across all four markets, indicating limited directional spillovers at the centre of the return distribution. In contrast, pronounced role differentiation emerges in the lower and upper tails.
At the lower tail (τ = 0.05), SET records the strongest positive short-run NET value (3.8557), followed by gold (1.4631), while oil is the principal receiver (−4.6083). This configuration indicates that adverse market conditions generate strong short-lived transmission from the domestic equity market, with oil absorbing a substantial share of the shocks.
At the upper tail (τ = 0.95), the configuration changes. USD becomes the strongest short-run transmitter (1.8226), closely followed by gold (1.8114), whereas SET becomes the dominant receiver (−4.4207). The change from SET-led transmission in the lower tail to USD-led transmission in the upper tail provides evidence that the source of short-lived spillovers is asymmetric across market states.
Overall, the short-run results show that extreme market conditions alter not only the magnitude but also the direction of immediate shock transmission. Gold maintains a positive transmitting role in both tails, but it does not consistently dominate the short-run network. This distinction is important for interpreting gold's role beyond the conventional safe-haven perspective.
4.3.2. Long-Run Transmission
The long-run transmission structure differs substantially from the short-run configuration, indicating that shocks are redistributed across markets as the investment horizon increases. Under normal conditions (τ = 0.50), long-run NET values remain close to zero for all four markets, suggesting limited persistent directional transmission around the centre of the return distribution.
A different pattern emerges in the lower tail (τ = 0.05). Oil becomes the strongest long-run transmitter, with a NET value of 4.1299, while SET records the largest negative value (−4.7014), indicating that the domestic equity market is the principal long-run receiver. Gold and USD play comparatively smaller roles, with NET values of −0.1672 and 0.7387, respectively.
The upper tail (τ = 0.95) presents a different long-run configuration. SET switches to become the strongest transmitter, recording a NET value of 3.2153, whereas oil becomes the largest receiver at −2.3325. Gold and USD both record modestly negative NET values. Thus, the direction of persistent transmission changes considerably between the lower and upper tails.
The long-run evidence therefore complements the short-run results by showing that the identity of the dominant transmitter is horizon-dependent as well as state-dependent. Oil leads long-run transmission under extreme downside conditions, whereas SET assumes the dominant transmitting position under extreme upside conditions. This switching pattern would be obscured by an aggregate connectedness measure that does not distinguish investment horizons.
Taken together, the short- and long-run results demonstrate that extreme market conditions generate different transmission mechanisms across horizons. The source of short-lived shocks need not be the source of persistent shocks, highlighting the importance of incorporating frequency information when assessing the role of gold and other markets within the system.
4.4. Gold–Equity Transmission and Conditional Diversification
4.4.1. Gold → SET across Quantiles
The Gold–SET relationship exhibits a pronounced state-dependent pattern across the return distribution. Under normal market conditions (τ = 0.50), Gold-to-SET transmission is negligible, with total connectedness of only 0.02%. This weak relationship contrasts sharply with the extreme tails, where transmission increases to 19.96% at τ = 0.05 and 19.27% at τ = 0.95. The results therefore indicate that the relationship between gold and the Thai equity market is not adequately represented by its behaviour around the centre of the distribution.
The frequency decomposition provides additional insight into this tail response. In the lower tail, Gold-to-SET transmission is divided between the short-run and long-run components, accounting for 8.82% and 11.14%, respectively. In the upper tail, the short-run component becomes more prominent, increasing to 12.07%, while the long-run component accounts for 7.20%. Thus, although Gold–SET transmission is strong in both tails, its temporal composition differs according to the direction of the market state.
This pattern provides an important qualification to the conventional safe-haven interpretation of gold. Rather than maintaining a stable relationship with equities across all market conditions, gold becomes substantially more connected to the SET market when returns move toward either extreme. The evidence therefore suggests that the relevance of gold for equity-market risk management is conditional on the prevailing market state and investment horizon, rather than being a uniform characteristic of gold.
4.4.2. Directional Comparison: Gold–SET
Table 4 presents the bidirectional results, further indicating that the tail relationship between gold and SET is better characterized as strong two-way connectedness than as persistent one-way transmission. At τ = 0.05, Gold-to-SET transmission is 19.96%, compared with 19.62% in the opposite direction. At τ = 0.95, the corresponding values are 19.27% and 18.62%, respectively. By contrast, both directions are negligible at the median, at 0.02% and 0.05%.
The near-symmetry of the two directions is important for interpreting the role of gold. Although gold occupies a positive net-transmitting position in the overall four-market system at both extreme quantiles, the Gold–SET pair itself does not provide evidence of persistent unilateral dominance. Instead, the two markets become strongly interconnected when conditions move toward the tails.
The frequency decomposition reinforces this interpretation. At τ = 0.05, Gold-to-SET transmission is slightly stronger in the long run (11.14%) than in the short run (8.82%), whereas the reverse direction is 10.36% and 9.26%, respectively. At τ = 0.95, the short-run component becomes more prominent in both directions, with 12.07% flowing from Gold to SET and 10.78% from SET to Gold. The direction and horizon of transmission therefore vary with the market state.
Overall, the evidence moves beyond a simple safe-haven classification. Gold is not isolated from equity-market shocks; instead, Gold–SET connectedness intensifies at both extremes and changes its temporal structure across states. This evidence does not by itself establish safe-haven performance, but it shows that gold–equity transmission becomes materially stronger under extreme conditions. The evidence therefore supports evaluating gold’s risk-management role conditionally rather than treating it as a universally effective safe haven.
4.5. State–Frequency Interaction and Role Switching
The combined quantile–frequency results reveal that market roles are not fixed across either market states or investment horizons. The identity of the strongest transmitter changes when the analysis moves from the lower tail to the upper tail and from short- to long-run frequencies.
At the lower tail (τ = 0.05), gold is the strongest transmitter when total connectedness is considered, whereas SET becomes the strongest short-run transmitter and oil assumes the leading transmitting position in the long run. At the upper tail (τ = 0.95), gold again occupies the strongest overall transmitting position, but USD becomes the leading short-run transmitter and SET becomes the strongest long-run transmitter. Under the median state, all NET positions remain close to zero, indicating no economically pronounced dominant transmitter.
This role switching provides evidence that transmission cannot be characterized by a fixed hierarchy among the four markets. In particular, the market that transmits shocks most strongly in the short run is not necessarily the market that dominates persistent transmission. The direction of transmission therefore depends jointly on where the market lies in its return distribution and the horizon over which shocks are evaluated.
The results also qualify the interpretation of gold's role. Gold consistently appears as an important aggregate transmitter in the two extreme states, but its dominance does not extend uniformly across frequencies. Its position is therefore better understood as state-contingent rather than structurally dominant.
Overall, the state–frequency interaction reveals a dynamic transmission architecture in which markets can switch between transmitting and receiving roles as conditions and horizons change. This finding represents a key distinction between the present framework and conventional connectedness measures that summarize the system with a single unconditional transmission structure.
4.6. Validation and Robustness Checks
The main results indicate strong variation in connectedness across market states and investment horizons. To assess the stability and interpretation of these findings, the analysis combines a quantile-selection check, supplementary frequency evidence, alternative dependence measures, and block-bootstrap inference.
4.6.1. Robustness to Quantile Selection
The analysis initially considers five quantiles, τ = 0.05, 0.25, 0.50, 0.75, and 0.95, rather than restricting the estimation to the three focal states used for the main interpretation. The intermediate quantiles provide a useful check on whether the observed tail pattern represents a gradual change across the distribution or is driven solely by the selected extreme points.
The results show that the pronounced transmission observed at τ = 0.05 and τ = 0.95 is accompanied by substantially weaker interaction around the centre of the distribution. The contrast between the extreme and median states therefore does not arise simply from selecting two isolated observations of the conditional distribution. Instead, the broader quantile specification supports the interpretation that connectedness becomes increasingly relevant as market conditions move away from the centre.
This robustness evidence strengthens the main conclusion that the transmission structure is quantile-dependent rather than unconditional. The extreme-state results consequently provide information that would be missed by focusing exclusively on average or median market behaviour.
4.6.2. Supplementary Validation through Frequency Decomposition
A second robustness consideration concerns the separation of transmission into short- and long-run components. The main findings remain informative when connectedness is examined separately across the two frequency bands rather than through aggregate transmission alone.
The comparison demonstrates that the identity of the dominant transmitter changes across horizons. For example, under extreme downside conditions, SET is the strongest short-run transmitter, whereas oil becomes the strongest long-run transmitter. Under extreme upside conditions, USD leads short-run transmission, while SET becomes the strongest long-run transmitter.
This evidence indicates that the principal findings are not an artefact of aggregating different frequencies into a single connectedness measure. Instead, the decomposition reveals additional structure that is concealed when short- and long-run transmission are combined. The results therefore support the interpretation that market-state dependence and horizon dependence operate jointly.
4.6.3. Alternative Dependence Measures
As an additional diagnostic, the unconditional dependence structure is examined using Pearson, Kendall, and Spearman correlations. The three measures produce consistently weak pairwise dependence across most of the four-market system. For example, the Pearson correlations between Oil and Gold, Gold and SET, and USD and SET are −0.0044, 0.0021, and 0.0019, respectively. The corresponding Kendall and Spearman measures remain similarly small.
This consistency across alternative dependence measures provides a useful diagnostic: the strong tail connectedness identified by the quantile–frequency framework is not simply a reflection of strong unconditional pairwise dependence. Rather, the two sets of results describe different aspects of the market relationship.
The contrast is particularly informative for Gold–SET. Their unconditional correlation is essentially zero, while their directional transmission rises substantially in both tails. This suggests that average dependence measures can mask relationships that become economically relevant only under extreme market conditions.
Accordingly, the alternative dependence measures reinforce rather than replace the main quantile–frequency results. They provide evidence that the central contribution of the study lies in identifying state-specific and horizon-specific transmission that is not apparent from conventional unconditional dependence measures.
4.6.4. Block-Bootstrap Robustness
The block-bootstrap analysis provides an additional assessment of the stability of the quantile-dependent connectedness results while preserving the temporal ordering of financial observations. The procedure uses 500 successful bootstrap replications with a block length of five observations. Rather than testing individual pairwise relationships, the analysis evaluates differences in system-wide connectedness between the lower tail, median state, and upper tail.
Table 5 presents the results, which provide strong support for the distinction between extreme and normal market conditions. The observed difference between the lower tail and the median state is 59.1898 percentage points, while the corresponding bootstrap mean is 58.8762, with a relatively narrow 95% confidence interval of [57.5924, 60.0270]. Similarly, the difference between the upper tail and the median state is 57.3697 percentage points, with a bootstrap mean of 57.7629 and a 95% confidence interval of [56.6749, 58.7565]. In both cases, the confidence intervals remain well above zero, indicating that the substantially stronger connectedness observed in the extreme states is stable under block resampling.
By contrast, the direct comparison between the two extreme states produces a smaller difference of −1.8201 percentage points. Its bootstrap confidence interval, [−2.2166, 0.0223], slightly overlaps zero. This result suggests that although both tails exhibit substantially greater connectedness than the median state, the evidence does not establish a statistically clear difference in overall connectedness between the lower and upper tails themselves.
This distinction is important for the interpretation of the main findings. The bootstrap evidence supports extreme-state amplification relative to normal conditions, but does not justify claiming that downside connectedness is systematically stronger than upside connectedness. The result therefore strengthens the state-dependent interpretation while imposing an appropriate qualification on claims of tail asymmetry.
Methodologically, this is consistent with the use of bootstrap inference to assess whether changes in connectedness measures are robust to sampling variation, particularly when the underlying financial observations may exhibit temporal dependence (Greenwood-Nimmo et al., 2024). It also complements recent research showing that financial-market connectedness can vary substantially across the conditional distribution and that tail spillovers may contain information that is obscured by unconditional measures (Cheng et al., 2024).
4.7. Economic Discussion
4.7.1. Tail-Dependent Market Integration
The empirical evidence suggests that integration among oil, gold, the U.S. dollar, and the Thai equity market is fundamentally state dependent. Market interaction remains limited around the centre of the conditional distribution but increases sharply when returns move toward either tail. Importantly, the block-bootstrap results confirm that the contrast between extreme and median states is highly stable, whereas the difference between the two extreme states themselves is not statistically decisive.
From an economic perspective, this pattern is consistent with the view that financial-market linkages become more tightly coupled when investors face unusually large shocks. Under relatively normal conditions, portfolio decisions can be diversified across assets with different risk characteristics. During extreme episodes, however, common information shocks, rapid portfolio rebalancing, liquidity considerations, and changes in risk perception can cause previously weakly connected markets to respond more synchronously. This interpretation is consistent with recent evidence that tail connectedness can differ substantially from dependence measured around the centre of the distribution (Cheng et al., 2024).
The finding is particularly relevant for the interpretation of gold. The weak Gold–SET relationship around the median does not imply that gold is structurally independent of the equity market. Instead, the relationship becomes substantially stronger in the tails. Thus, gold's diversification properties appear to be conditional on the market state, rather than invariant across the return distribution.
This result also provides a more nuanced interpretation of the safe-haven hypothesis. A conventional unconditional correlation may suggest little relationship between gold and equities and therefore appear consistent with a safe-haven interpretation. However, the quantile–frequency evidence shows that a near-zero average relationship can coexist with strong dependence during extreme states. Similar state-dependent behaviour has been documented in recent studies of tail connectedness and safe-haven assets (Cheng et al., 2024; Shahzad et al., 2025).
Accordingly, the economic value of gold should not be assessed solely from its unconditional correlation with equities. Its risk-management role depends on when the hedge is evaluated and under which part of the return distribution. This provides an important qualification to the traditional characterization of gold as a universally effective safe haven.
4.7.2. Horizon-Dependent Transmission
The results further indicate that market integration is not only conditional on the state of returns but also on the horizon over which shocks propagate. The short-run and long-run decompositions produce different transmitting and receiving configurations, demonstrating that the same market can occupy different positions in the connectedness network depending on the persistence of the shock.
This distinction has a clear economic interpretation. Short-run transmission is more closely associated with immediate information arrival, market reactions, liquidity adjustments, and rapid portfolio rebalancing. Long-run transmission, in contrast, reflects the persistence and gradual propagation of shocks through investment decisions and macro-financial adjustments. Consequently, aggregating these frequencies into a single connectedness measure can conceal economically meaningful differences in the transmission mechanism.
The role switching observed across the four markets illustrates this point particularly clearly. In the downside tail, SET is the strongest short-run transmitter while oil becomes the dominant long-run transmitter. In the upside tail, USD leads short-run transmission whereas SET assumes the strongest long-run transmitting position. Gold remains an important transmitter in the extreme states, but its position also varies across frequencies. These patterns indicate that transmission leadership is neither state invariant nor horizon invariant.
This finding has implications for portfolio management and risk monitoring. A portfolio manager concerned with immediate market stress may need to monitor the assets that dominate short-run transmission, whereas an investor with a longer horizon should pay greater attention to markets that propagate persistent shocks. A single total connectedness measure cannot provide this distinction. The economic relevance of a market therefore depends not only on whether it transmits risk, but also on how quickly that risk is transmitted and how long it persists.
The result is consistent with the broader literature on frequency-based connectedness, which shows that spillovers can have substantially different structures across short- and long-run frequencies (Baruník & Kley, 2019; Greenwood-Nimmo et al., 2024). It also supports the use of a joint quantile–frequency framework: quantiles identify the state in which transmission occurs, while frequency decomposition identifies the horizon over which transmission unfolds.
Taken together, these findings suggest that financial contagion should not be viewed as a single, homogeneous process. Market state determines the intensity and configuration of transmission, while frequency determines its persistence. This joint perspective provides a more informative basis for understanding gold's interaction with equity-market risk than an unconditional safe-haven classification.
5. Conclusions, Policy Implications, Limitations, and Future Research
5.1. Conclusions
This study examined the state- and frequency-dependent connectedness among oil, gold, the U.S. dollar, and the Thai equity market using a quantile–frequency connectedness framework. The analysis was motivated by the observation that conventional unconditional dependence measures may provide an incomplete representation of financial-market integration when relationships change across market conditions and investment horizons. The empirical results provide consistent evidence that the transmission structure of the four-market system is strongly conditional on both the position of returns within their distributions and the frequency at which spillovers are evaluated.
The first central finding is that market integration intensifies at distributional extremes. Connectedness is extremely limited around the median state but rises substantially at both the lower and upper tails. The result indicates that weak unconditional or median dependence should not be interpreted as evidence of persistent market segmentation. Instead, previously weakly connected markets can become substantially more integrated when the system enters extreme conditions.
Second, the analysis shows that market roles are state dependent. Gold occupies the strongest aggregate net-transmitting position in both extreme states, while SET, oil, and USD assume different transmitting and receiving roles depending on the market state and horizon. Consequently, the transmission network cannot be characterized by a fixed hierarchy of markets.
Third, the evidence challenges a simple interpretation of gold as an unconditional safe haven. Gold–SET connectedness is negligible under median conditions but becomes substantial in both tails. Moreover, the relationship is broadly bidirectional rather than persistently dominated by Gold-to-SET transmission. The evidence therefore suggests that gold's diversification and risk-management properties are conditional rather than unconditional.
Fourth, the frequency decomposition demonstrates that transmission leadership changes across horizons. SET dominates short-run transmission under extreme downside conditions, while oil becomes the dominant long-run transmitter. Under extreme upside conditions, USD leads short-run transmission and SET assumes the strongest long-run transmitting position. This indicates that the source of immediate shocks is not necessarily the source of persistent shocks.
Finally, the robustness analysis reinforces the central state-dependent interpretation. The block-bootstrap results show that the differences between each extreme state and the median state remain highly stable, whereas the direct difference between the two extreme states is not statistically decisive. Thus, the strongest conclusion supported by the evidence is not that downside connectedness is necessarily greater than upside connectedness, but that both extremes represent materially different integration regimes from normal market conditions.
Overall, the study moves beyond the conventional question of whether gold is a safe haven. The more informative question is when, at what horizon, and within which transmission structure gold provides diversification value. The findings indicate that these conditions matter substantially, while the connectedness evidence should not be interpreted as a direct test of portfolio-level safe-haven performance.
5.2. Policy Implications
The findings have several implications for financial-market monitoring and risk management.
First, financial surveillance should incorporate market-state information. Because connectedness rises substantially during extreme conditions, monitoring systems based only on unconditional correlations or average spillover measures may underestimate the potential for cross-market transmission during periods of stress. Regulators and financial institutions should therefore complement conventional indicators with tail-oriented measures that can identify changes in transmission as markets approach extreme states.
Second, risk monitoring should distinguish between short-run and persistent transmission. The results demonstrate that the dominant transmitter can change across frequencies. A market that is particularly important for immediate shock transmission may not be the principal source of persistent risk. Consequently, stress-monitoring frameworks should distinguish temporary market reactions from longer-lasting spillover channels rather than relying on a single aggregate connectedness indicator.
Third, the findings have implications for portfolio diversification involving gold. The negligible Gold–SET relationship under median conditions might suggest substantial diversification potential if considered alone. However, the pronounced increase in Gold–SET connectedness at both tails indicates that diversification benefits can weaken precisely when market conditions become extreme. Portfolio allocation strategies should therefore evaluate gold's effectiveness conditional on market states rather than treating its safe-haven property as invariant.
Fourth, policy coordination across financial and commodity markets may become more important during extreme episodes. Oil, gold, exchange rates, and equity markets do not operate as isolated segments when market conditions deteriorate or become unusually favourable. A shock originating in one market can be transmitted through different channels and at different speeds. Monitoring these cross-market linkages can therefore help policymakers identify emerging sources of systemic pressure.
The policy implication is consequently not to discourage the use of gold as a diversification asset, but to avoid treating its risk-management role as static or unconditional. Risk-management policies should instead recognize that the effectiveness of an asset depends on the prevailing market state and the investor's relevant horizon.
5.3. Limitations
Several limitations should be acknowledged.
First, the analysis is based on four markets—oil, gold, the U.S. dollar, and the Thai equity market. Although this configuration captures important commodity, precious-metal, currency, and equity channels, it does not encompass all assets that may influence Thailand's financial system. Other commodities, interest rates, bond markets, global equity indices, and volatility indicators could potentially alter the estimated transmission structure.
Second, the empirical analysis identifies statistical connectedness rather than structural causality. A high spillover measure indicates substantial transmission within the estimated system but does not by itself establish a specific economic causal mechanism. The interpretation of individual transmission channels should therefore remain consistent with the connectedness framework rather than being interpreted as definitive structural causation.
Third, the quantile–frequency framework summarizes market conditions through selected conditional quantiles and frequency bands. Although the robustness analysis considers alternative quantile specifications and confirms the stability of the main extreme-state pattern, additional quantile locations or alternative frequency partitions could reveal further heterogeneity.
Fourth, the block-bootstrap analysis provides evidence on sampling stability but does not eliminate all sources of model uncertainty. The bootstrap is designed to preserve temporal dependence through block resampling, while uncertainty associated with model specification, lag selection, frequency boundaries, and alternative estimation procedures may remain.
Finally, the study focuses on the statistical transmission structure rather than directly evaluating portfolio performance. The findings therefore establish when connectedness intensifies and how transmission roles change, but they do not directly quantify the resulting gains or losses from alternative portfolio allocations.
These limitations do not undermine the central findings but define the scope within which they should be interpreted.
5.4. Future Research
Future research can extend this framework in several directions.
First, subsequent studies could incorporate a broader multi-asset system by adding interest rates, sovereign bonds, volatility indices, cryptocurrencies, or additional Asian equity markets. Such an extension would allow researchers to determine whether the state- and frequency-dependent architecture identified here remains present in a larger regional financial network.
Second, future research could move from statistical connectedness toward portfolio-based evaluation. Quantile–frequency connectedness measures could be incorporated into dynamic portfolio allocation, hedging, and downside-risk optimization. This would provide direct evidence on whether state-dependent information improves risk-adjusted portfolio performance.
Third, future studies could investigate time-varying quantile–frequency connectedness. The present framework identifies differences across market states and horizons, but combining these dimensions with rolling or dynamic estimation could reveal how transmission evolves through major economic and financial episodes.
Fourth, future research could examine whether the observed transmission mechanisms are structurally asymmetric across crisis types. Financial crises, commodity shocks, geopolitical events, pandemics, and monetary-policy shocks may generate different transmission architectures even when they produce similarly extreme returns.
Finally, the role of gold warrants further investigation using a broader definition of safe-haven performance. Rather than classifying gold simply as a hedge or safe haven, future research could evaluate its effectiveness conditional on market state, transmission direction, frequency, and portfolio objective. Such an approach would provide a more economically meaningful assessment of gold's role in international risk management.
Funding
This research received no external funding.
Institutional Review Board Statement
Not applicable.
Informed Consent Statement
Not applicable.
Data Availability Statement
The processed dataset generated and analysed during the current study is available from the corresponding author upon reasonable request. The original raw data were obtained from publicly available sources, including Investing.com.
Conflicts of Interest
The author declares no conflict of interest.
Appendix A — Additional Statistical Diagnostics
Table A1.
Unit-Root Tests for the Daily Return Series.
| Variable | ADF | PP | KPSS | Conclusion |
| Oil | −46.4033*** | −65.5877*** | 0.0718 | Stationary |
| Gold | −46.4975*** | −64.8283*** | 0.3250 | Stationary |
| USD | −45.8506*** | −64.3049*** | 0.0312 | Stationary |
| SET | −43.2745*** | −63.5013*** | 0.2174 | Stationary |
Notes: ADF = Augmented Dickey–Fuller; PP = Phillips–Perron; KPSS = Kwiatkowski–Phillips–Schmidt–Shin. The ADF and PP tests have a null hypothesis of a unit root, whereas the KPSS test has a null hypothesis of stationarity. The reported statistics are based on the aligned daily return series used in the main analysis. *** denotes rejection of the unit-root null hypothesis at the 1% level for the ADF and PP tests.
Table A1 reports complementary stationarity diagnostics for the four daily return series. The ADF and PP statistics strongly reject the null hypothesis of a unit root for all markets, while the KPSS statistics do not reject the null of stationarity. The results therefore provide consistent evidence that the return series are stationary and suitable for the subsequent quantile-based dynamic and frequency-domain connectedness analysis.
Figure A1.
Daily Return Series of Oil, Gold, USD, and SET.
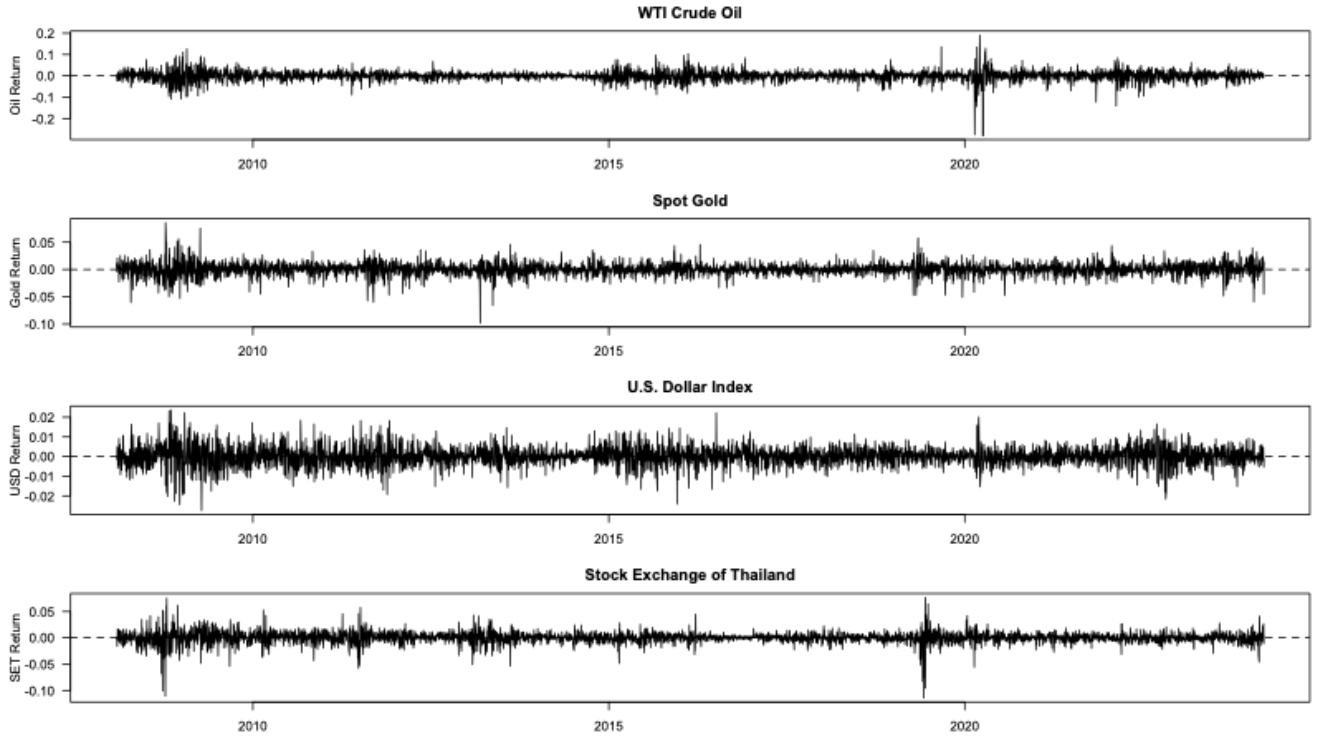
Figure A1 presents the daily return series used in the empirical analysis. The series display periods of elevated fluctuations and extreme observations, providing visual evidence of time-varying market conditions and supporting the use of a state-dependent connectedness framework.
Appendix B — Additional Quantile Evidence
Table A2.
Additional Quantile-Specific Net Connectedness.
| Quantile | Market | Total | Short-run | Long-run |
| 0.25 | Oil | −0.4561 | 0.0052 | −0.4613 |
| 0.25 | Gold | 0.3676 | −0.6529 | 1.0205 |
| 0.25 | USD | 0.1858 | −0.0132 | 0.1991 |
| 0.25 | SET | −0.0974 | 0.6609 | −0.7582 |
| 0.75 | Oil | −0.3521 | 0.4687 | −0.8207 |
| 0.75 | Gold | 0.3699 | −0.2210 | 0.5909 |
| 0.75 | USD | −0.0258 | 0.3115 | −0.3374 |
| 0.75 | SET | 0.0080 | −0.5592 | 0.5672 |
Note: Positive values indicate net transmission, whereas negative values indicate net reception. Short-run and long-run components correspond to the frequency decomposition adopted in the main analysis.
Table A2 provides additional evidence for the intermediate quantile states. The results indicate that the transmission structure evolves across the conditional distribution rather than changing only at the extreme tails. Gold remains a net transmitter at both τ = 0.25 and τ = 0.75, with its transmission concentrated predominantly in the long-run component. In contrast, SET exhibits stronger short-run transmission at τ = 0.25 but becomes a net long-run transmitter at τ = 0.75. These intermediate-state results reinforce the state–frequency interaction documented in the main analysis without reproducing the extreme-quantile estimates.
Appendix C — Additional Frequency Evidence
Table A3. Frequency-Specific TO and FROM Connectedness.
Panel A: τ = 0.05
| Market | TO Total | FROM Total | TO Short | FROM Short | TO Long | FROM Long |
| Oil | 58.8273 | 59.3057 | 26.9057 | 31.5140 | 31.9216 | 27.7917 |
| Gold | 61.8719 | 60.5760 | 29.9258 | 28.4628 | 31.9461 | 32.1133 |
| USD | 59.5417 | 59.5135 | 28.5047 | 29.2152 | 31.0370 | 30.2984 |
| SET | 58.6385 | 59.4842 | 29.3947 | 25.5390 | 29.2438 | 33.9452 |
Panel B: τ = 0.50
| Market | TO Total | FROM Total | TO Short | FROM Short | TO Long | FROM Long |
| Oil | 1.0104 | 1.0054 | 0.5740 | 0.6565 | 0.4363 | 0.3489 |
| Gold | 0.0437 | 0.0916 | 0.0255 | 0.0615 | 0.0183 | 0.0301 |
| USD | 0.9818 | 0.9701 | 0.6369 | 0.5537 | 0.3450 | 0.4164 |
| SET | 0.0844 | 0.0532 | 0.0586 | 0.0233 | 0.0258 | 0.0299 |
Panel C: τ = 0.95
| Market | TO Total | FROM Total | TO Short | FROM Short | TO Long | FROM Long |
| Oil | 55.5243 | 57.0701 | 33.3933 | 32.6066 | 22.1309 | 24.4634 |
| Gold | 60.0409 | 58.6186 | 35.5613 | 33.7499 | 24.4796 | 24.8687 |
| USD | 59.8443 | 58.5153 | 35.2990 | 33.4763 | 24.5454 | 25.0390 |
| SET | 56.1895 | 57.3950 | 31.8719 | 36.2926 | 24.3176 | 21.1024 |
Table A3 reports the complete directional connectedness measures by frequency for the three principal quantile states. The results show that directional transmission is substantially stronger in both tail states than in the median state. At the downside tail, Gold exhibits the highest total outward transmission, while SET receives relatively more short-run spillovers and exhibits greater long-run inflows. At the upside tail, Gold and USD display strong outward transmission, whereas SET is more strongly exposed to short-run inflows. These additional directional estimates provide further evidence that market roles depend jointly on the location of the return distribution and the transmission horizon.
Appendix D — Additional Figures
Figure A4.
Quantile–Frequency Connectedness Profile.
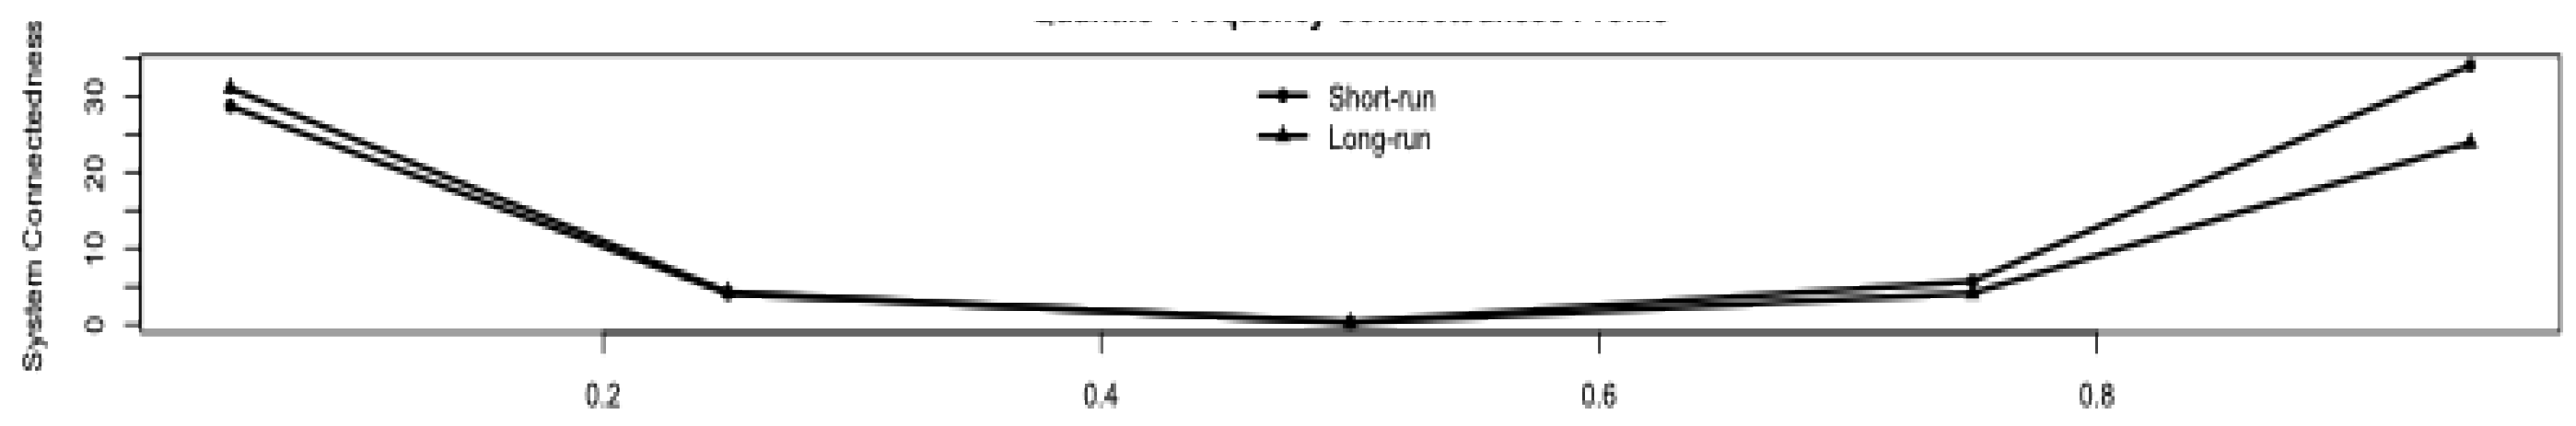
Figure A4 presents the system-wide connectedness across alternative locations of the conditional return distribution and transmission horizons. The figure complements the tabulated estimates by illustrating how short-run and long-run connectedness vary across market states. The separation between the two frequency components indicates that the intensity of market integration is not uniform across horizons, supporting the interpretation that connectedness is jointly state- and horizon-dependent
Figure A5.
Net Transmission Across the Four Markets.
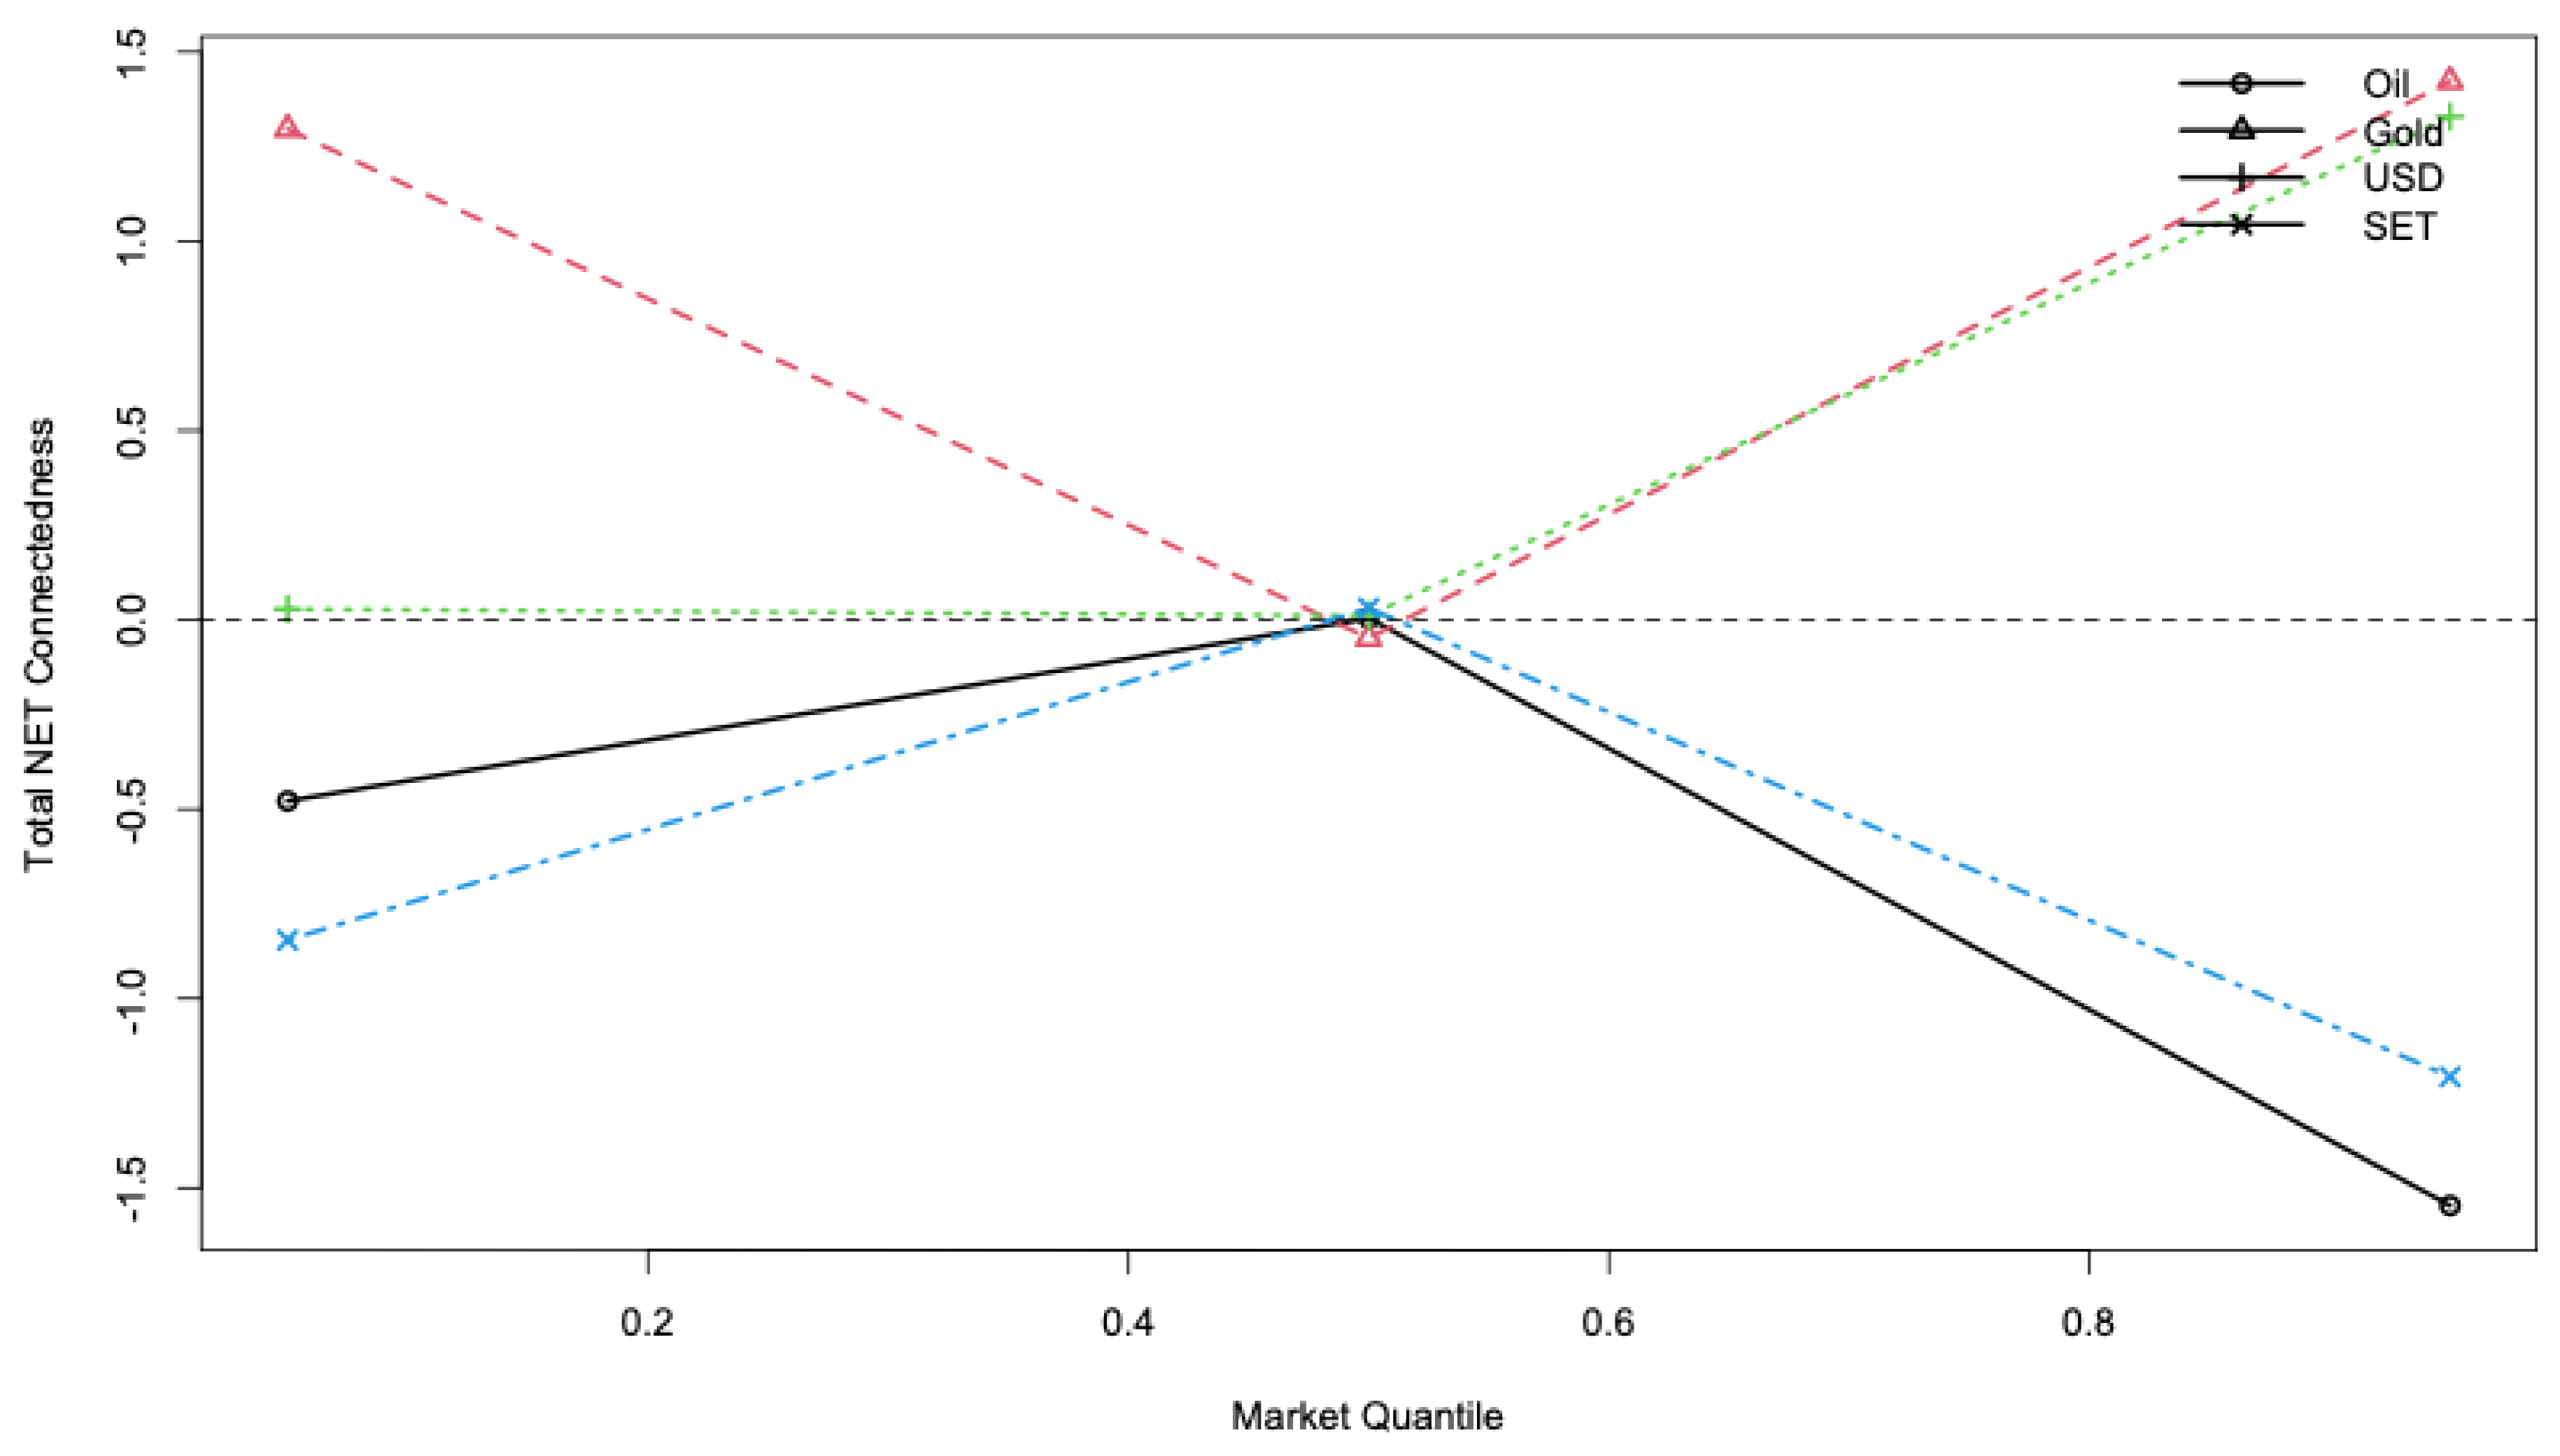
Figure A5 illustrates the net transmission positions of Oil, Gold, USD, and SET across the principal market states. Positive values identify net transmitters, whereas negative values indicate net receivers. The figure highlights differences in market roles across the conditional distribution and provides a visual representation of the role-switching pattern documented in the empirical results. In particular, Gold exhibits a relatively persistent net-transmitting position in the tail states, while the positions of Oil, USD, and SET vary according to the prevailing market state.
Figure A6.
Gold–SET Directional Transmission.
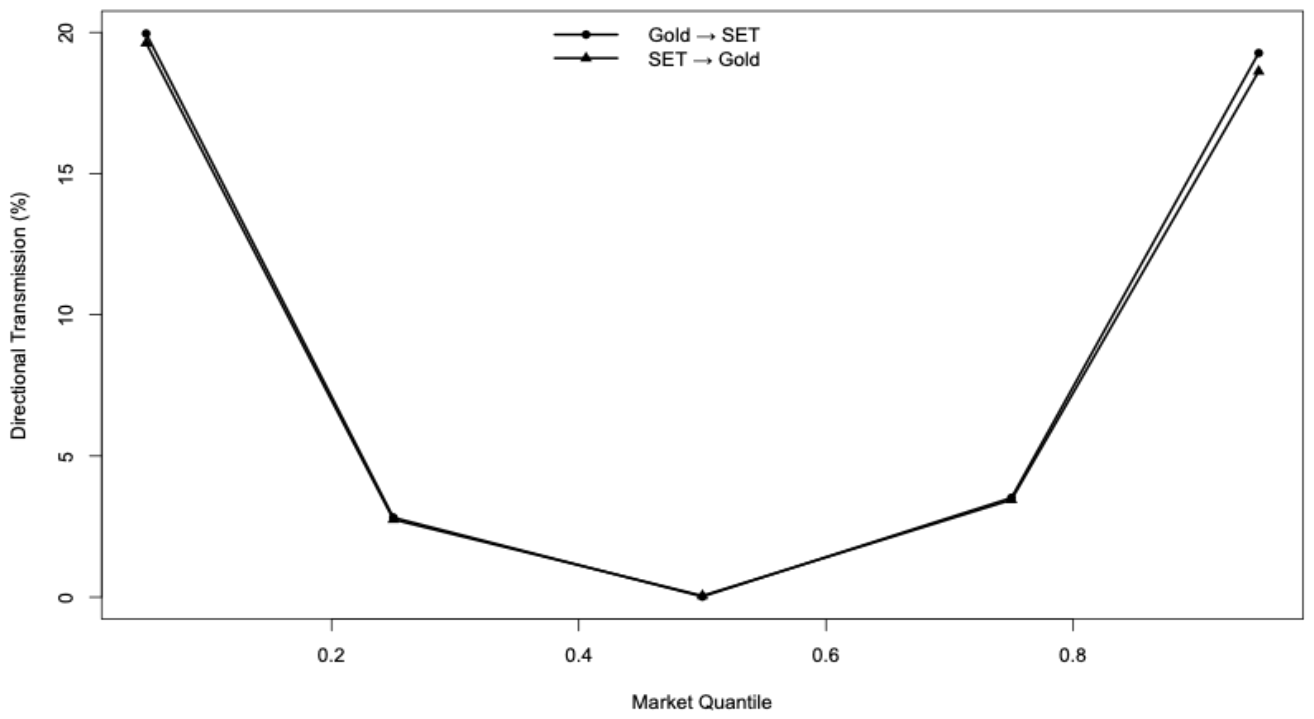
Figure A6 provides a supplementary visualization of the directional relationship between Gold and the SET market across the conditional return distribution. The comparison between Gold-to-SET and SET-to-Gold transmission shows that the two directions are broadly similar in magnitude in the extreme states rather than displaying persistent unilateral dominance. Directional transmission becomes substantially stronger in the tails than around the median state, providing additional evidence that the Gold–equity relationship cannot be adequately characterized by a single unconditional dependence measure.
Taken together, Figure A4, Figure A5 and Figure A6 provide visual confirmation of the principal empirical patterns without duplicating the main tables. The figures emphasize three complementary dimensions of the analysis: variation in system connectedness across market states and horizons, changes in the net roles of the four markets, and the broadly bidirectional Gold–SET relationship. These supplementary visualizations reinforce the interpretation of state-dependent and horizon-dependent market integration developed in the main analysis.
References
- Ando, T.; Greenwood-Nimmo, M.; Shin, Y. Quantile connectedness: Modelling tail behaviour in the topology of financial networks. Management Science 2018, 64(9), 4614–4631. [Google Scholar]
- Baruník, J.; Kley, T. Quantifying the frequency domain connectedness of financial assets. Journal of Financial Econometrics 2019, 17(2), 363–388. [Google Scholar]
- Baruník, J.; Křehlík, T. Measuring the frequency dynamics of financial connectedness and systemic risk. Journal of Financial Econometrics 2018, 16(2), 271–296. [Google Scholar] [CrossRef]
- Baur, D. G.; Glover, K. The dynamics of gold and silver as safe havens. International Review of Financial Analysis 45 2016, 1–14. [Google Scholar]
- Baur, D. G.; Lucey, B. M. Is gold a hedge or a safe haven? The role of stocks, bonds and gold. Financial Review 2010, 45(2), 217–229. [Google Scholar] [CrossRef]
- Baur, D. G.; McDermott, T. K. Is gold a safe haven? International evidence. Journal of Banking & Finance 2010, 34(8), 1886–1898. [Google Scholar] [CrossRef]
- Beckmann, J.; Berger, T.; Czudaj, R. Does gold act as a hedge or a safe haven for stocks? A smooth transition approach. Economic Modelling 48 2015, 16–24. [Google Scholar] [CrossRef]
- Biswas, P.; Jain, P.; Maitra, D. Are shocks in the stock markets driven by commodity markets? Evidence from Russia-Ukraine war. Journal of Commodity Markets 34 2024, 100387. [Google Scholar]
- Cheng, T.; Liu, F.; Liu, J.; Yao, W. Tail connectedness: Measuring the volatility connectedness network of equity markets during crises. Pacific-Basin Finance Journal 87 2024, 102497. [Google Scholar]
- Cui, J.; Maghyereh, A. Unveiling interconnectedness: Exploring higher-order moments among energy, precious metals, industrial metals, and agricultural commodities in the context of geopolitical risks and systemic stress. Journal of Commodity Markets 33 2024, 100380. [Google Scholar]
- Diebold, F. X.; Yılmaz, K. Measuring financial asset return and volatility spillovers, with application to global equity markets. The Economic Journal 2009, 119(534), 158–171. [Google Scholar] [CrossRef]
- Diebold, F. X.; Yılmaz, K. Better to give than to receive: Predictive directional measurement of volatility spillovers. International Journal of Forecasting 2012, 28(1), 57–66. [Google Scholar] [CrossRef]
- Diebold, F. X.; Yılmaz, K. On the network topology of variance decompositions: Measuring the connectedness of financial firms. Journal of Econometrics 2014, 182(1), 119–134. [Google Scholar] [CrossRef]
- Fama, E. F. Efficient capital markets: A review of theory and empirical work. The Journal of Finance 1970, 25(2), 383–417. [Google Scholar] [CrossRef]
- Greenwood-Nimmo, M.; Kočenda, E.; Nguyen, V. H. Detecting statistically significant changes in connectedness: A bootstrap-based technique. Economic Modelling 140 2024, 106843. [Google Scholar]
- Hanif, W.; Hadhri, S.; El Khoury, R. Quantile spillovers and connectedness between oil shocks and stock markets of the largest oil producers and consumers. Journal of Commodity Markets 34 2024, 100404. [Google Scholar]
- Lo, A. W. The adaptive markets hypothesis. The Journal of Portfolio Management 2004, 30(5), 15–29. [Google Scholar] [CrossRef]
- Markowitz, H. Portfolio selection. The Journal of Finance 1952, 7(1), 77–91. [Google Scholar] [CrossRef]
- Mensi, W.; Ziadat, S. A.; Rababa'a, A. R.; Vo, X. V.; Kang, S. H. Oil, gold and international stock markets: Extreme spillovers, connectedness and its determinants. The Quarterly Review of Economics and Finance 95 2024, 1–17. [Google Scholar] [CrossRef]
- Mensi, W.; Nabli, M. A.; Guesmi, M.; Belghouthi, H. E.; Kang, S. H. Quantile on quantile connectedness between safe-haven assets and stock markets: A portfolio risk perspective. The North American Journal of Economics and Finance 80 2025, 102496. [Google Scholar]
- Pesaran, M. H.; Shin, Y. Generalized impulse response analysis in linear multivariate models. Economics Letters 1998, 58(1), 17–29. [Google Scholar] [CrossRef]
- Shang, J.; Hamori, S. Quantile time-frequency connectedness analysis between crude oil, gold, financial markets, and macroeconomic indicators: Evidence from the US and EU. Energy Economics 132 2024, 107473. [Google Scholar]
- Shahzad, S. J. H.; Bouri, E.; Karim, S.; Sadorsky, P. A partial correlation-based connectedness approach: Extreme dependence among commodities and portfolio implications. Energy Economics 144 2025, 108421. [Google Scholar] [CrossRef]
- Zheng, Q.; Wu, J.; Lin, B. Geopolitical risk and extreme risk connectedness among energy and other strategic commodities: Fresh sight using the high-dimensional CoVaR model. Journal of Futures Markets 2024, 44(11), 1787–1806. [Google Scholar] [CrossRef]
Table 2.
Descriptive Statistics of Daily Returns.
| Market | N | Mean | SD | Min | Q25 | Median | Q75 | Max | Skewness | Kurtosis |
| Oil | 4,206 | 0.0000 | 0.0239 | −0.2798 | −0.0104 | 0.0008 | 0.0113 | 0.1908 | −0.7129 | 16.0513 |
| Gold | 4,206 | 0.0004 | 0.0116 | −0.0981 | −0.0051 | 0.0004 | 0.0064 | 0.0859 | −0.2652 | 8.1214 |
| USD | 4,206 | 0.0001 | 0.0049 | −0.0274 | −0.0026 | 0.0000 | 0.0027 | 0.0236 | −0.0514 | 5.1352 |
| SET | 4,206 | 0.0001 | 0.0113 | −0.1143 | −0.0048 | 0.0005 | 0.0055 | 0.0765 | −0.9994 | 15.8423 |
Note: Statistics are calculated from the aligned daily return series for Oil, Gold, USD, and SET over 1 February 2008–31 December 2025.
Table 3.
Quantile-Dependent Net Connectedness across the Four Markets.
| Quantile | Market | Total NET | Short-run NET | Long-run NET |
| 0.05 | Oil | −0.4784 | −4.6083 | 4.1299 |
| 0.05 | Gold | 1.2959 | 1.4631 | −0.1672 |
| 0.05 | USD | 0.0282 | −0.7105 | 0.7387 |
| 0.05 | SET | −0.8457 | 3.8557 | −4.7014 |
| 0.50 | Oil | 0.0050 | −0.0825 | 0.0874 |
| 0.50 | Gold | −0.0479 | −0.0360 | −0.0119 |
| 0.50 | USD | 0.0117 | 0.0831 | −0.0714 |
| 0.50 | SET | 0.0312 | 0.0353 | −0.0041 |
| 0.95 | Oil | −1.5458 | 0.7867 | −2.3325 |
| 0.95 | Gold | 1.4223 | 1.8114 | −0.3891 |
| 0.95 | USD | 1.3290 | 1.8226 | −0.4936 |
| 0.95 | SET | −1.2055 | −4.4207 | 3.2153 |
Note: NET > 0 indicates a net transmitter, whereas NET < 0 indicates a net receiver. Values are based on the final observation of the estimated quantile–frequency connectedness system.
Table 4.
Gold–SET Directional Connectedness across Quantiles and Frequencies.
| Quantile | Gold → SET Total | SET → Gold Total | Gold → SET Short-run | SET → Gold Short-run | Gold → SET Long-run | SET → Gold Long-run |
| 0.05 | 19.96 | 19.62 | 8.82 | 9.26 | 11.14 | 10.36 |
| 0.50 | 0.02 | 0.05 | 0.01 | 0.03 | 0.01 | 0.02 |
| 0.95 | 19.27 | 18.62 | 12.07 | 10.78 | 7.20 | 7.85 |
Table 5.
Block-Bootstrap Robustness of Quantile-Dependent Connectedness.
| Quantile comparison | Observed difference | Bootstrap mean | Bootstrap SD | 95% CI |
| τ = 0.05 vs. τ = 0.50 | 59.1898 | 58.8762 | 0.6124 | [57.5924, 60.0270] |
| τ = 0.95 vs. τ = 0.50 | 57.3697 | 57.7629 | 0.5171 | [56.6749, 58.7565] |
| τ = 0.95 vs. τ = 0.05 | −1.8201 | −1.1134 | 0.5612 | [−2.2166, 0.0223] |
Note: Bootstrap estimation achieved 500 successful replications, so there are no failed bootstrap draws in the reported sample.
Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content. |
© 2026 by the author. Licensee MDPI, Basel, Switzerland. This article is an open access article distributed under the terms and conditions of the Creative Commons Attribution (CC BY) license.
Copyright: This open access article is published under a Creative Commons CC BY 4.0 license, which permit the free download, distribution, and reuse, provided that the author and preprint are cited in any reuse.