
Submitted:
22 October 2026
Posted:
22 October 2026
You are already at the latest version
Abstract
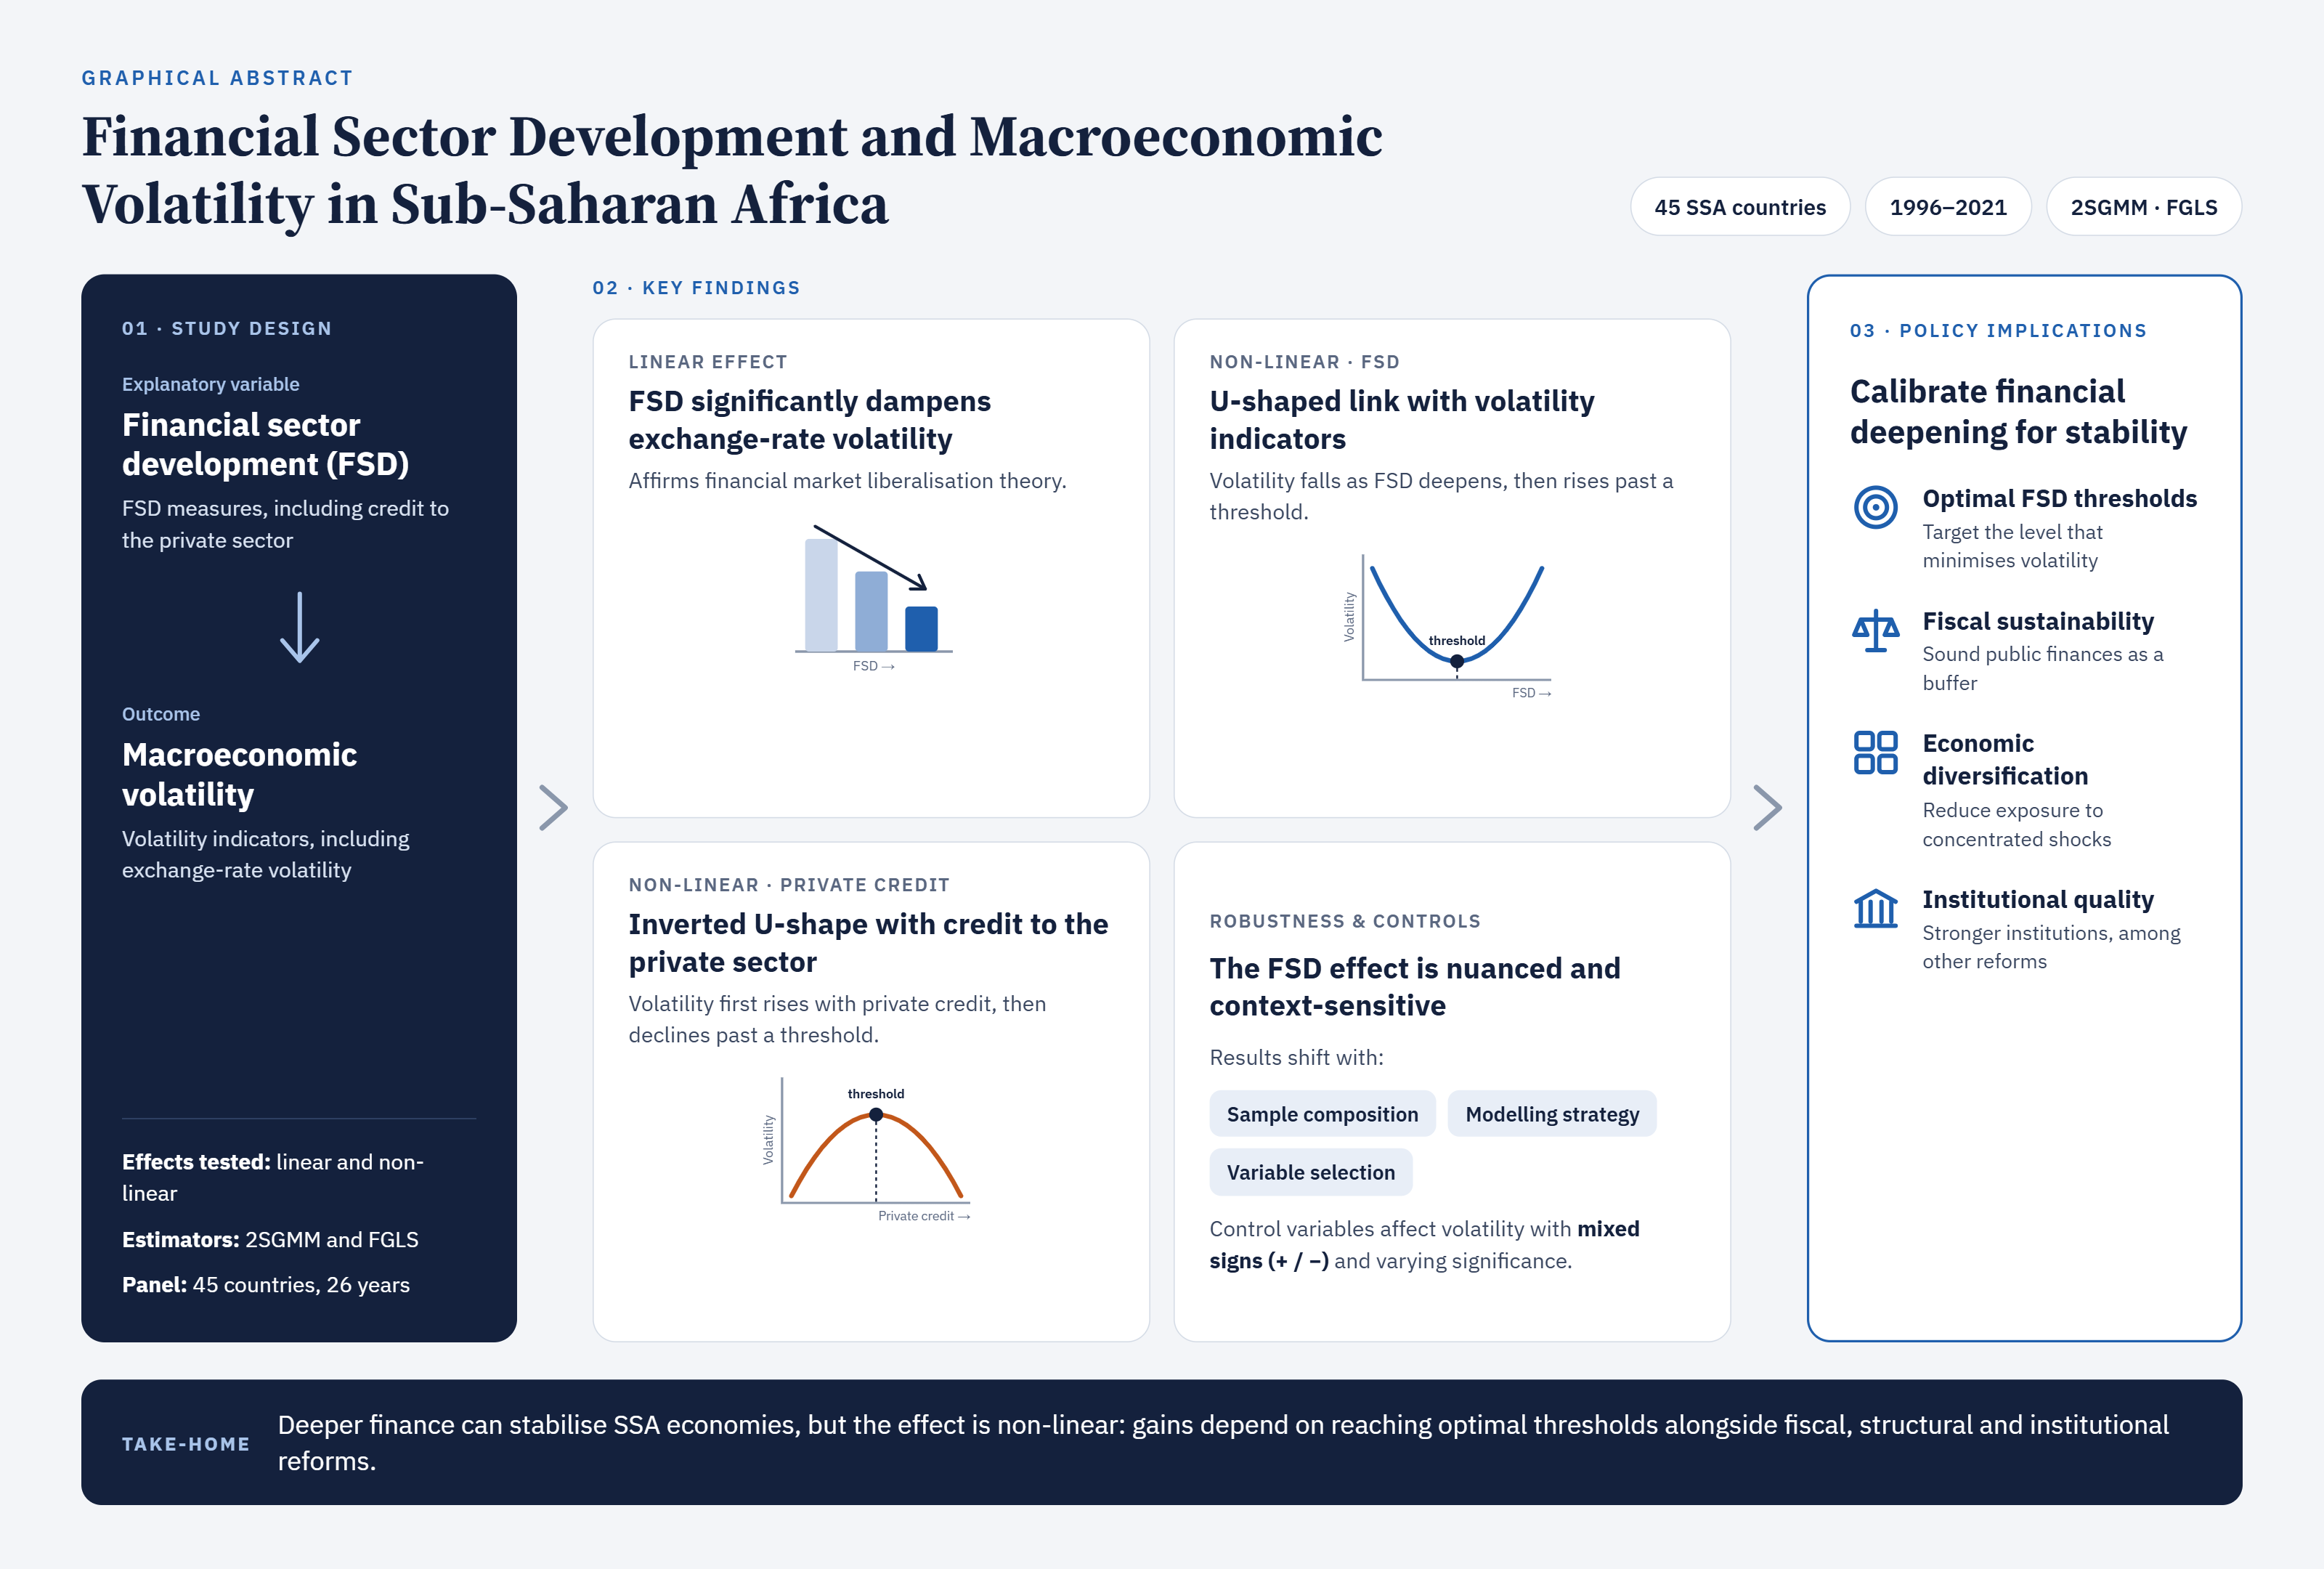
This study investigates linear and non-linear effects of financial sector development on macroeconomic volatility in 45 SSA countries from 1996 to 2021, using the 2SGMM and FGLS estimators. The empirical analysis shows that financial sector development can significantly dampen exchange rate volatility, affirming financial market liberalization theory. However, the effect of financial sector development is nuanced and sensitive to the vagaries of sample composition, econometric modeling strategy, and variable selection. Also, a non-linear, U-shaped relationship is found between financial sector development and macroeconomic volatility indicators, whereas an inverted U-shaped effect is observed when credit to the private sector is used. Furthermore, the study's control variables are shown to influence macroeconomic volatility to varying degrees of statistical significance and with varying signs of the coefficients. Therefore, policymakers should strive to achieve optimal thresholds for macroeconomic stability while focusing on fiscal sustainability, economic diversification, and improvements in institutional quality, among others.
Keywords:
financial sector development
; financial market liberalization
; structural reforms
; macroeconomic volatility
; SSA countries
Copyright: This open access article is published under a Creative Commons CC BY 4.0 license, which permit the free download, distribution, and reuse, provided that the author and preprint are cited in any reuse.