

Submitted:
05 October 2026
Posted:
09 October 2026
You are already at the latest version
Abstract
Geopolitical instability presents an inherent paradox for renewable energy economics, reinforcing the strategic imperative for renewable energy while acting as a cost multiplier for its deployment. This study examines how geopolitical escalation associated with the US-Israel-Iran conflict would affect renewable energy investment in Egypt, specifically utility-scale solar photovoltaic (PV), through physical supply side and financial risk transmission channels. Drawing on the theory of investment under uncertainty, a quantitative scenario-based techno-economic framework is developed using recent secondary data. Physical pressures arising from commodity, manufacturing, and logistics disruptions are measured through changes in capital expenditure (CAPEX), while changes in the weighted average cost of capital (WACC) measure financial risk. A reference solar PV system is evaluated alongside limited escalation, prolonged disruption, and severe escalation stress scenarios, followed by two-way sensitivity and robustness analyses. The reference case yields a levelized cost of electricity (LCOE) of 4.62 US cents/kWh under the baseline assumptions. Findings show that LCOE increases to 5.17 cents/kWh under limited escalation, 6.04 cents/kWh under prolonged disruption, and 7.06 cents/kWh under severe combined stress, with an increase of 52.9% relative to the reference case. Results further suggest that financing conditions exert a larger independent effect than the physical supply shock; a 20% increase in CAPEX raises LCOE by 18.4%, whereas increasing WACC by 4% raises it by 28.7%. This ranking remains stable across alternative reference specifications, while combined scenarios reveal an amplification mechanism when higher financing costs are applied to an enlarged capital requirement. Consistent with the theoretical proposition, the findings indicate that abundant renewable resources do not necessarily imply resilient investment conditions under geopolitical stress. Geopolitically exposed emerging economies like Egypt should therefore prioritize financial de-risking and supply chain resilience when formulating energy policy.
Keywords:
geopolitical risk
; investment under uncertainty
; renewable energy
; solar PV
; levelized cost of electricity
; cost of capital
1. Introduction
The global energy transition is unfolding within an increasingly fragmented and uncertain geopolitical environment. Technological learning, manufacturing scale and policy support have substantially improved the competitiveness of renewable energy, yet the conditions surrounding deployment are no longer shaped by technology costs alone. Geopolitical tensions interact with commodity markets, trade relations, technology supply chains, shipping routes and financing conditions, creating multiple channels through which external instability can affect renewable investment. Recent empirical research confirms that geopolitical risk can influence renewable transition outcomes, but the direction and magnitude of that influence vary across countries, technologies, development levels and institutional settings (He et al., 2025; Javed et al., 2025; 2026; Lin & Zhang, 2025; Shittu et al., 2025; Zhu et al., 2026). This heterogeneity is particularly important for emerging and developing economies, where strong renewable resources can coexist with imported technology dependence, exposure to international logistics and comparatively expensive capital.
Renewables nevertheless remain economically compelling. Recent IRENA evidence places utility-scale solar PV among the most competitive sources of new electricity generation and emphasizes the central role of renewables in accelerating the transition away from fossil fuels (International Renewable Energy Agency [IRENA], 2026a, 2026b). The strategic case can become even stronger during geopolitical instability because domestic renewable generation reduces recurrent dependence on internationally traded fuels and can limit exposure to fossil fuel price shocks. Yet low technology costs and strong natural resources do not by themselves guarantee favorable investment conditions. The economics of a capital-intensive renewable project also depend on the price of equipment, the reliability of supply chains, the timing of delivery, the cost of finance and the risk premium attached to committing capital.
This distinction is increasingly visible in the recent literature. Studies of geopolitical risk and renewable transition no longer point toward a single positive or negative relationship. Some evidence suggests that geopolitical pressure can accelerate renewable transition by strengthening incentives for diversification and energy autonomy (He et al., 2025). Other studies identify adverse effects on renewable investment and clean energy transition performance through financial, institutional and market channels (Javed et al., 2025; Lin & Zhang, 2025; Shittu et al., 2025). Cross-country evidence further indicates development-specific effects, with geopolitical risk more likely to impede renewable progress in developing economies where institutional and financial constraints are more binding (2026). Zhu et al. (2026) add a nonlinear dimension by identifying an inverted U-shaped relationship in which moderate geopolitical pressure can stimulate transition while excessive risk inhibits it. Together, these findings provide empirical support for treating geopolitical instability as a source of opposing pressures rather than a uniformly beneficial or harmful force.
Egypt represents a particularly relevant setting in which to examine those pressures. The country possesses substantial solar and wind resources and has increasingly positioned renewable energy as part of its long-term decarbonization and energy security strategy (Abdelmeguid & Ibrahiem, 2025; Dallmann et al., 2022; Gad et al., 2025). At the same time, renewable competitiveness cannot be assessed solely through resource availability or technological learning. Egypt participates in internationally integrated renewable technology markets, operates within an emerging market financing environment and occupies a strategically sensitive geographic position adjacent to the Suez Canal and Red Sea. These characteristics create exposure to external disruptions even when domestic solar irradiation and plant technology remain unchanged.
Recent escalation involving the United States, Israel and Iran illustrates how several forms of exposure can emerge simultaneously. Maritime disruption can increase freight, insurance and logistics costs, extend voyage distances and delay equipment delivery (2026; United Nations Conference on Trade and Development [UNCTAD], 2025). Geopolitical risk can affect critical mineral prices and strengthen the connectedness between mineral markets and clean technology investment (Depraiter & Goutte, 2025; Saadaoui et al., 2025). Concentrated PV production and trade networks can transmit disruptions across multiple stages of the value chain, while aggressive attempts to localize or decouple supply chains can themselves impose cost penalties (Chen et al., 2025; Cui et al., 2025; Gervais et al., 2025; W. Li et al., 2025). At the same time, geopolitical uncertainty can alter perceived sovereign, currency and project risk and increase the return required by providers of debt and equity (Bondarenko et al., 2024; Dato et al., 2025; International Energy Agency [IEA], 2024; Terrapon-Pfaff et al., 2025; Wildgruber et al., 2026).
These channels matter because utility-scale solar PV is highly capital intensive. A large share of lifetime expenditure is committed before commercial operation, while fuel expenditure is effectively absent. As a result, both the amount of upfront capital and the rate at which that capital is financed have a structural influence on LCOE. Recent evidence shows that renewable power is particularly sensitive to financing costs (Wilson et al., 2025), that WACC remains elevated across many African electricity markets (Dato et al., 2025), and that country and technology specific financing conditions vary substantially across renewable markets (Wildgruber et al., 2026). Evidence from Brazil further demonstrates that expensive capital can offset the benefit of falling PV technology costs in an emerging market (Monroy Gomez & Jansen, 2026). This makes financing conditions a potential geopolitical transmission mechanism in their own right rather than merely a background assumption in project appraisal.
The resulting tension can be described as an inherent paradox for renewable energy investment. Geopolitical instability and fossil fuel market volatility can reinforce the strategic imperative for renewable deployment by increasing the value of domestic low fuel cost generation and reducing dependence on imported fuels (He et al., 2025; IRENA, 2026b; Tol, 2023; Vakulchuk et al., 2020). The same instability can simultaneously weaken the economic conditions required to undertake renewable investment by raising equipment and logistics costs, tightening financing conditions and increasing uncertainty (Depraiter & Goutte, 2025; Javed et al., 2025; Lin & Zhang, 2025; Saadaoui et al., 2025; Shittu et al., 2025; Zhu et al., 2026). A country may therefore have stronger strategic reasons to accelerate renewables precisely when the financial and physical conditions for doing so become less favorable.
A rapidly expanding literature now examines each part of this problem. Empirical studies estimate how geopolitical risk affects renewable investment and transition outcomes (Flouros et al., 2022; He et al., 2025; Javed et al., 2025; 2026; Lin & Zhang, 2025; Matallah et al., 2023; Shittu et al., 2025; Zhu et al., 2026). A second strand examines maritime disruption, critical minerals and PV supply chain vulnerability (Chen et al., 2025; Cui et al., 2025; Depraiter & Goutte, 2025; Erol et al., 2024; Gervais et al., 2025; W. Li et al., 2025; 2026; Saadaoui et al., 2025; UNCTAD, 2025). A third demonstrates the importance of financing conditions for renewable competitiveness and LCOE (Calcaterra et al., 2024; Dato et al., 2025; IEA, 2024; Monroy Gomez & Jansen, 2026; Terrapon-Pfaff et al., 2025; Wildgruber et al., 2026; Wilson et al., 2025). The theory of investment under uncertainty provides an additional explanation for why irreversibility, uncertainty and the possibility of delaying commitment can affect investment decisions (Dixit & Pindyck, 1994; Pindyck, 1991), with direct applications to renewable energy and solar PV (Kim et al., 2017; Lazo & Watts, 2023; Ofori et al., 2021; Or et al., 2024; Zhang et al., 2016). The literature is therefore rich in relevant components, but those components are commonly examined at different levels of analysis.
The remaining gap is not whether geopolitical risk matters for renewable energy. Recent evidence makes that proposition increasingly difficult to dispute. The less developed question is how geopolitical stress is translated into the economics of an individual renewable project through distinguishable physical and financial channels, how the magnitudes of those channels compare, and how they interact when they deteriorate simultaneously. Aggregate geopolitical risk indices and transition indicators are well suited to identifying broad relationships, but they do not directly reveal how external stress changes project CAPEX, WACC and ultimately LCOE. Conventional techno-economic analysis, conversely, often treats CAPEX and discount rates as exogenous assumptions without explicitly connecting their deterioration to geopolitical mechanisms.
This study addresses that gap through a quantitative scenario-based techno-economic assessment of geopolitical stress and utility-scale solar PV economics in Egypt. The theory of investment under uncertainty provides the principal economic lens for interpreting why changes in uncertainty and capital market conditions matter for a capital-intensive and substantially irreversible investment. The empirical model then focuses on the project-level mechanisms through which those conditions are transmitted. Rather than forecasting the precise consequences of a particular conflict trajectory, progressively adverse scenarios are calibrated from contemporary secondary evidence. Two principal transmission mechanisms are examined; a physical supply side channel through which commodity, manufacturing and logistics pressures affect project CAPEX, and a financial channel through which increasing investment risk affects WACC.
Accordingly, the study asks; (RQ1) How can geopolitical escalation affect utility-scale solar PV LCOE in Egypt through physical supply side and financial risk transmission channels? (RQ2) Which transmission channel—higher CAPEX or deteriorating financing conditions—exerts the greater influence on solar PV LCOE under progressively adverse geopolitical scenarios? (RQ3) To what extent can concurrent physical and financial shocks amplify the effect of geopolitical risk on the economic competitiveness of utility-scale solar PV in Egypt?
The contribution is threefold. First, the study connects the theory of investment under uncertainty with the recent empirical literature on geopolitical risk and renewable investment and translates that relationship into project-level economic transmission channels. Second, it decomposes physical and financial exposure within a reproducible LCOE framework by representing supply side pressures through CAPEX and financing risk through WACC, while also testing their interaction. Third, it evaluates whether the relative importance of these channels remains stable across alternative project assumptions. The contribution is therefore located in the integrated architecture of the analysis rather than in any single variable; it moves from the established proposition that geopolitical risk influences renewable transition outcomes to the more specific question of how external stress reshapes utility-scale solar PV economics through the cost of the physical asset and the cost of financing it.
2. Literature Review
2.1. Geopolitical Risk, Energy Security and the Energy Transition
Geopolitical risk has historically been closely associated with energy security because fossil fuel production and international trade are geographically concentrated and exposed to political instability, sanctions, conflict and strategic competition (Baumeister & Hamilton, 2019; Flint, 2022; Kilian et al., 2024; Pinchetti, 2024; Verduzco-Bustos & Zanetti, 2025). Energy market research further shows that oil prices respond to shifts in supply, demand and uncertainty and that volatility is shaped by global market conditions (Caldara et al., 2019; Chatziantoniou et al., 2021). These mechanisms make conventional energy systems sensitive not only to physical interruption but also to expectations about future availability, transport routes and political relations. For fuel-importing economies, geopolitical shocks can therefore transmit rapidly through import bills, inflation, exchange-rate pressures and electricity generation costs.
The expansion of renewable energy changes this geopolitical relationship but does not eliminate it. Wind and solar generation can reduce recurrent dependence on imported fuels because the primary energy resource is domestic and no continuous fuel purchase is required. This creates an important energy security benefit and can strengthen the strategic case for renewable deployment when fossil fuel markets are volatile (He et al., 2025; IRENA, 2026b; Tol, 2023; Vakulchuk et al., 2020). However, renewable technologies remain embedded in international markets for minerals, components, manufacturing capacity, shipping, insurance and capital. The geopolitical exposure of the energy system therefore shifts in form rather than disappearing.
Recent empirical evidence reflects this duality. He et al. (2025) find that geopolitical risk can accelerate renewable transition and report particularly strong effects for solar energy, making the study especially relevant to the present focus on solar PV. In contrast, Javed et al. (2025) find that geopolitical risk hinders renewable energy investment in the United States, while Lin and Zhang (2025) identify an inhibitory effect on renewable energy development in China through channels that include green investment and energy metal markets. Shittu et al. (2025) similarly report adverse effects on clean energy transition performance in a broad global panel. Taken together, this evidence shows that a strategic incentive to diversify away from fossil fuels does not automatically translate into stronger investment outcomes and reinforces the need to distinguish strategic transition incentives from the economic conditions governing project deployment.
The most recent cross-country evidence further suggests that national development conditions and the intensity of geopolitical stress shape the direction of the relationship. Y. Li, Hanif et al. (2026) find that geopolitical risk can accelerate renewable adoption in advanced economies while hindering progress in developing economies, where institutional and financial constraints are more binding. Zhu et al. (2026) identify an inverted U-shaped relationship across 42 countries; moderate geopolitical risk can stimulate renewable transition, while excessive geopolitical pressure becomes inhibitory. This 2026 evidence is particularly important for the present argument because it empirically supports the possibility that the strategic impetus for transition can coexist with progressively worsening investment conditions as geopolitical stress intensifies. The effect is therefore conditional on intensity, institutional quality, financial development and structural characteristics rather than governed by a single universal response.
Earlier studies had already pointed toward this ambiguity. Flouros et al. (2022) identify geopolitical risk as a determinant of renewable investment, while Matallah et al. (2023) show that persistent geopolitical risk can strengthen the transition imperative in MENAT oil-importing economies. The more recent literature does not overturn these contributions; it refines them by showing that the strategic push toward renewables can coexist with deteriorating investment conditions. This distinction is central to the present study because it separates the strategic value of renewable energy from the economics of committing capital to a specific project.
For the present analysis, energy security is therefore treated as a multidimensional concept. Renewable generation can improve long-run security by reducing exposure to imported fuels, but the ability to realize that benefit depends on whether projects remain financeable and constructible under stress. A geopolitical episode that strengthens the desirability of renewable energy can still delay deployment if equipment costs rise, logistics become less reliable or investors demand higher returns. This provides the conceptual basis for examining physical and financial transmission channels separately rather than interpreting geopolitical risk through a single aggregate sign.
2.2. Geopolitical Risk and Renewable Energy Supply Chains
Solar PV supply chains are geographically dispersed and involve multiple stages, including mineral extraction, refining, polysilicon and wafer production, cell and module manufacturing, electrical equipment production, shipping and project installation. This international division of production has supported rapid cost reduction, but it also creates exposure to concentrated manufacturing capacity and cross-border disruption. Recent network and optimization studies show that PV supply chains remain geographically concentrated and vulnerable to trade disruption (Chen et al., 2025; Cui et al., 2025; Gervais et al., 2025; W. Li et al., 2025). The same studies also caution that resilience cannot be equated with complete localization because aggressive decoupling or isolationist restructuring can raise costs and slow deployment (Chen et al., 2025; Cui et al., 2025).
The physical vulnerability begins upstream. Renewable technologies depend on internationally traded metals and minerals whose prices can respond to geopolitical risk. Saadaoui et al. (2025) show that geopolitical risk affects the prices of several critical minerals and that the magnitude and timing of the response depend on procurement risk and the nature of geopolitical shocks. Depraiter and Goutte (2025) similarly find that the connectedness among geopolitical risk, rare earth markets and clean technology markets strengthens during periods of elevated tension and can hinder clean energy investment. These findings establish a mechanism through which geopolitical stress can affect renewable project costs even when the conflict is geographically distant from the project site.
Manufacturing concentration creates a second vulnerability. Cui et al. (2025) show that policy-driven restructuring of global PV supply chains involves a trade-off between security and cost; diversification can improve resilience, while highly isolationist strategies can generate significant inefficiencies. W. Li et al. (2025) map the evolving geography of global PV trade and show that increasing concentration can amplify vulnerability to bilateral trade disruption. Gervais et al. (2025) likewise demonstrate how disruption can propagate through PV supply chain scenarios. Together, these studies suggest that a disturbance at one stage of production or trade can be transmitted through downstream equipment availability, lead times and prices.
Maritime logistics constitute a third transmission mechanism. The Suez Canal and Red Sea connect Asian manufacturing centers with European, Mediterranean and North African markets. Disruptions affecting these routes can generate rerouting, longer voyage distances, higher fuel use, insurance costs, delivery delays and freight-rate volatility. UNCTAD documents how Red Sea disruption forced rerouting around the Cape of Good Hope and increased voyage distances, delays and operating costs (UNCTAD, 2025). Y. Li, Xia, et al. (2026), using panel data for 42 coastal economies, find that geopolitical risk weakens shipping supply chain resilience through logistics infrastructure disruption, freight-rate volatility and reduced customs clearance efficiency. These mechanisms are directly relevant to imported renewable equipment.
PV-specific resilience research provides a complementary management perspective. Erol et al. (2024) identify diversification, collaboration, visibility, flexibility and related organizational capabilities as important enablers of resilience in solar PV supply chains. Chen et al. (2025) show that global PV supply chain integration has supported diffusion and cost savings, implying that resilience policy must preserve the benefits of international specialization while reducing excessive concentration. The relevant policy question is therefore not whether international supply chains should be abandoned, but how exposure to single suppliers, routes and manufacturing nodes can be reduced without sacrificing the cost advantages that helped make solar PV competitive.
For project appraisal, these different disturbances overlap economically. A mineral price shock, higher manufacturing energy costs, freight escalation, insurance premiums and delayed delivery can all ultimately increase the amount of capital required to place a project into service. Treating each disturbance as a separate percentage addition to LCOE would risk double counting because several pressures are already embodied in equipment and installed-cost quotations. The present study therefore consolidates the physical consequences of geopolitical stress into CAPEX. This preserves the economic meaning of the physical channel while allowing its effect to be compared transparently with a distinct financing shock.
2.3. Solar PV Costs, LCOE and Financing Conditions
LCOE provides a widely used measure of the discounted lifetime cost of electricity generation. For solar PV, principal determinants include installed CAPEX, operation and maintenance expenditure, electricity generation, project lifetime, technological degradation and the discount rate or WACC. The metric is particularly useful for the present study because it allows changes in physical investment cost and financing conditions to be translated into a common unit of generation cost while holding solar resource and technical performance constant.
Rapid technological learning, manufacturing expansion and deployment scale have dramatically reduced PV costs (IRENA, 2026a). However, global weighted averages conceal substantial differences between markets because installed costs, solar resources, taxes, contractual structures and financing conditions vary considerably. A project in a high-irradiation market can therefore have excellent physical productivity and still face a comparatively high LCOE if the capital required to build it is expensive. This distinction is especially important in emerging economies, where the cost of capital can remain high even when global technology prices decline.
The temporal structure of PV expenditure explains why financing matters so strongly. Unlike thermal generation, where a substantial share of lifetime expenditure is incurred through recurrent fuel purchases, solar PV concentrates a large proportion of cost before commercial operation. The discount rate therefore affects the annualized value of a large upfront investment over the entire project lifetime. Wilson et al. (2025) show that renewable power is more sensitive to financing costs than fossil generation and that changes in the cost of capital can materially alter relative competitiveness. Financing is therefore not an ancillary variable; it is embedded in the economic structure of capital-intensive renewable generation.
The IEA finds that the cost of capital for utility-scale solar PV in emerging and developing economies is well above that observed in advanced economies and that financing costs can account for around half or more of PV LCOE in these markets (IEA, 2024). African evidence reinforces this point. Dato et al. (2025) estimate electricity-sector WACC across 48 African countries and find values consistently above global and other regional benchmarks, with substantial cross-country variation. Calcaterra et al. (2024) further show that differentiated financing costs materially affect the affordability and pace of energy transition in developing economies. These findings indicate that renewable-resource abundance and low technology costs can be partly offset by the financial environment in which projects are developed.
Recent methodological work also improves the empirical basis for representing renewable WACC. Wildgruber et al. (2026) develop an approach calibrated against 439 empirical WACC observations across 86 countries and demonstrate the importance of country and technology specific premia. A MENA-focused assessment reports an inflation-adjusted pre-tax renewable energy WACC of 13.86% for Egypt under its business-as-usual country risk specification (Terrapon-Pfaff et al., 2025). Although individual project financing terms can differ materially from national estimates, this evidence supports treating WACC as a variable that responds to country and market risk rather than as a universal technical constant.
Project-level evidence from Brazil provides an especially relevant comparator. Monroy Gomez and Jansen (2026) estimate WACC and LCOE for utility-scale solar PV projects awarded through regulated auctions and show that financing conditions became a dominant component of project cost despite substantial reductions in CAPEX. Their results demonstrate how macroeconomic and financial conditions can offset technological cost improvements in an emerging market. The present study extends this logic in a different direction by asking whether a geopolitical stress episode can transmit into project economics through WACC and whether that financial channel can exceed the effect of a physical CAPEX shock.
The distinction between capital cost and cost of capital is therefore essential. Capital cost refers to the physical amount of investment required to construct and commission the asset and is represented here by CAPEX. Cost of capital refers to the return required by debt and equity providers and is represented by WACC. Geopolitical stress can affect either dimension independently. Commodity, manufacturing, freight, insurance and equipment disruption can raise CAPEX without necessarily changing financing rates, while higher perceived sovereign, currency, regulatory or project risk can increase WACC even if equipment prices remain unchanged. The two channels can also occur simultaneously, which creates the possibility of amplification when a higher financing rate is applied to a larger capital requirement.
2.4. Theoretical Background and Conceptual Foundations
The theoretical foundation of this study draws primarily on the theory of investment under uncertainty, complemented by neoclassical investment theory and the role of financing conditions in capital-intensive investment. This combination is particularly relevant to renewable energy projects because substantial capital must be committed upfront, much of that commitment is difficult to reverse once construction begins, and the economic environment surrounding the project can change considerably over its lifetime. Geopolitical instability adds another layer of uncertainty by affecting both the physical cost of developing renewable assets and the financial conditions under which those assets are financed.
Neoclassical investment theory provides an important starting point. Jorgenson (1963) links capital formation to the economic cost of employing capital, implying that changes in the relative price of capital services alter the desired capital stock and the incentive to invest. For utility-scale solar PV, this relationship is especially important because expenditure is concentrated at the beginning of the project while subsequent fuel costs are negligible. A deterioration in financing conditions can therefore affect project economics even when the generating technology and renewable resource remain unchanged. Conventional investment appraisal becomes less complete, however, when investment is substantially irreversible, future conditions are uncertain and investors retain flexibility regarding when capital is committed.
The theory of investment under uncertainty extends conventional investment analysis by explicitly recognizing irreversibility, uncertainty and timing flexibility. Pindyck (1991) emphasizes that many investment expenditures are largely irreversible once undertaken but can often be delayed. The ability to postpone commitment allows investors to wait for additional information about future prices, costs, interest rates and market conditions. Uncertainty therefore affects investment not only through expected profitability but also through the value associated with retaining flexibility. Dixit and Pindyck (1994) formalize this logic by treating an investment opportunity as an option; exercising it commits capital and sacrifices the possibility of waiting for further information. When uncertainty rises and investment is sufficiently irreversible, the threshold required to justify immediate commitment can increase.
This reasoning is directly relevant to renewable energy investment. Renewable power projects are capital intensive, require substantial expenditure before electricity production begins and involve assets whose alternative uses may be limited once installed. Investors simultaneously face uncertainty surrounding technology costs, electricity prices, financing conditions, regulatory arrangements, policy support and macroeconomic conditions. The theoretical implication is not simply that uncertainty makes projects more expensive. It is that the timing and attractiveness of commitment depend on both expected project value and the value of preserving flexibility when future conditions remain unresolved.
Real options applications provide empirical and methodological support for this interpretation. Zhang et al. (2016) develop a real options model for solar PV investment and show that uncertainty surrounding investment costs and market variables can materially affect investment value and optimal timing. Kim et al. (2017) identify policy conditions, financing variables, exchange rates, inflation and technological change among the uncertainties shaping renewable investment decisions in developing countries. Ofori et al. (2021), examining utility-scale renewable energy investment in Ghana, find value in delaying investment while uncertainty remains elevated and show that investment value is sensitive to volatility in project costs and revenues. These studies are particularly relevant to emerging economies where renewable-resource potential can be strong while the conditions required to mobilize capital remain fragile.
The wider solar PV literature reinforces the importance of timing flexibility. Lazo and Watts (2023), in a comprehensive review of real options applications to solar PV, identify investment timing, technological change, policy design, market conditions and uncertainty as recurring concerns. Or et al. (2024) demonstrate in a recent Turkish PV application that explicitly valuing the option to defer can alter investment appraisal relative to conventional NPV analysis. Carozzani and D’Alpaos (2025), in a 2025 systematic literature review of real options in renewable power investment with particular attention to hydropower and solar PV, further show that deferral is the most frequently examined real option and that investment costs remain among the recurrent sources of uncertainty. Their review also highlights the continuing need for more robust treatment of uncertainty in developing-country settings. The literature has continued to develop in 2026. Y. Li, Pan, et al. (2026) apply a real options valuation framework to concentrated solar power investment in China and show that accounting for a ten-year deferral option and optimal investment timing can change the investment conclusion relative to conventional NPV appraisal. Together, these studies confirm that the economic relevance of uncertainty, irreversibility and timing flexibility remains active in the most recent renewable investment literature. They do not imply that every renewable project requires a formal real options model. Rather, they establish that static project economics can understate the importance of uncertainty when investors can delay commitment and when the underlying capital expenditure is difficult to reverse.
Geopolitical risk introduces a distinctive source of uncertainty into this investment problem. Earlier evidence established that geopolitical risk is relevant to renewable investment rather than being confined to conventional fossil fuel markets (Flouros et al., 2022; F. Li et al., 2021; Matallah et al., 2023; Vakulchuk et al., 2020). The recent empirical literature is considerably richer and does not point in a single direction. Positive, negative, nonlinear and development-specific responses have all been documented (He et al., 2025; Javed et al., 2025; Y. Li, Hanif, et al., 2026; Lin & Zhang, 2025; Shittu et al., 2025; Zhu et al., 2026). This heterogeneity is compatible with the theory of investment under uncertainty because geopolitical pressure can alter both the expected strategic value of renewable energy and the uncertainty surrounding the conditions under which capital is committed.
The inherent paradox can therefore be expressed in investment terms. Geopolitical instability can raise the strategic value of renewable energy by increasing the benefits of diversification, domestic generation and reduced exposure to imported fossil fuels (He et al., 2025; IRENA, 2026b; Tol, 2023; Vakulchuk et al., 2020; Zhu et al., 2026). At the same time, the same instability can increase the physical cost of investment through mineral, manufacturing and logistics pressures (Cui et al., 2025; Depraiter & Goutte, 2025; W. Li et al., 2025; Saadaoui et al., 2025) and increase the financial cost of commitment through higher risk premia and financing costs (Calcaterra et al., 2024; Dato et al., 2025; IEA, 2024; Monroy Gomez & Jansen, 2026; Wildgruber et al., 2026; Wilson et al., 2025). A stronger strategic rationale can therefore coexist with a weaker immediate investment environment.
The cost of capital forms a particularly important bridge between theory and project economics. In a capital-intensive technology, an increase in WACC changes the economic value attached to future electricity production relative to the upfront commitment of capital. This can occur even when the physical asset and solar resource remain unchanged. Project-level evidence from Brazil shows that financing can become a dominant component of utility-scale PV costs in an emerging market (Monroy Gomez & Jansen, 2026), while African and cross-country evidence demonstrates substantial variation in WACC and the importance of financing premia (Calcaterra et al., 2024; Dato et al., 2025; Wildgruber et al., 2026). These findings make the financial environment central to interpreting how uncertainty reaches renewable project economics.
The theoretical argument also clarifies why CAPEX and WACC should remain analytically distinct. CAPEX represents the physical amount of capital that must be committed, while WACC represents the required return associated with financing that commitment. A geopolitical shock can increase one, the other or both. When both deteriorate simultaneously, the higher financing rate is applied to an enlarged capital requirement. This interaction does not constitute a real options result in itself, but it demonstrates how the economic conditions surrounding irreversible investment can worsen through more than one pathway at the same time.
The theory of investment under uncertainty is therefore used as an interpretive foundation rather than as a formally tested model. The study does not estimate an option value, derive an optimal investment trigger or determine the optimal timing of deferral. Such an exercise would require stochastic specification of the relevant state variables and a different empirical design. Instead, the theory establishes why uncertainty, irreversibility and changing capital conditions matter when interpreting the vulnerability of renewable investment. The scenario framework then quantifies two observable project-economic channels through which geopolitical stress can alter those conditions; physical supply side pressures represented through CAPEX and financial risk represented through WACC.
This theoretical structure provides the bridge between the geopolitical literature and the techno-economic model. It moves the analysis beyond the general proposition that geopolitical instability influences renewable energy by identifying the project-level variables through which such influence can occur. It also provides the basis for examining whether physical supply side disruption or financing deterioration represents the stronger source of investment vulnerability and whether the two channels reinforce one another under combined stress. The scenario and sensitivity analyses therefore do not test the theory of investment under uncertainty directly; they quantify project-level mechanisms whose interpretation is consistent with its broader economic logic.
2.5. Egypt and the Research Gap
Egypt combines significant renewable energy potential with distinctive geopolitical, logistical and financial exposure. Existing studies demonstrate both the potential for accelerated renewable deployment and the importance of system-level planning in the Egyptian power sector (Abdelmeguid & Ibrahiem, 2025; Dallmann et al., 2022; Gad et al., 2025). Abdelmeguid and Ibrahiem (2025) identify pathways for accelerated decarbonization, while Dallmann et al. (2022) emphasize the interaction between renewable potential and power-system path dependence. Gad et al. (2025) further illustrate the value of integrated planning when energy choices interact with wider resource constraints. Collectively, this literature establishes a strong domestic rationale for renewable expansion but does not directly examine how a regional geopolitical stress episode changes the economics of an individual utility-scale PV project.
Recent Egypt-specific evidence brings geopolitical risk much closer to the center of the national energy debate. Hassanen et al. (2026), using data for 2000–2023, identify a long-run negative relationship between geopolitical risk and energy security in Egypt while also finding a positive role for renewable energy. This is an important contribution because it demonstrates that geopolitical exposure is empirically relevant to Egyptian energy outcomes rather than merely a regional background condition. Its level of analysis, however, remains national and macro-oriented. It does not decompose how geopolitical stress can alter renewable project CAPEX, financing conditions and LCOE.
The international literature provides strong evidence for each component required to build such a project-level explanation. Geopolitical risk affects renewable transition and investment outcomes (Flouros et al., 2022; He et al., 2025; Javed et al., 2025; Y. Li, Hanif, et al., 2026; Lin & Zhang, 2025; Matallah et al., 2023; Shittu et al., 2025; Zhu et al., 2026). Maritime disruption and concentrated PV supply chains can transmit physical stress through freight, trade and equipment availability (Chen et al., 2025; Cui et al., 2025; Erol et al., 2024; Gervais et al., 2025; W. Li et al., 2025; Y. Li, Xia, et al., 2026; UNCTAD, 2025). Critical mineral markets provide another route through which geopolitical tension can affect clean technology costs and investment (Depraiter & Goutte, 2025; Saadaoui et al., 2025). Financing research shows that WACC is elevated and heterogeneous across African and emerging markets and can materially alter renewable LCOE (Calcaterra et al., 2024; Dato et al., 2025; IEA, 2024; Monroy Gomez & Jansen, 2026; Terrapon-Pfaff et al., 2025; Wildgruber et al., 2026; Wilson et al., 2025). The theory of investment under uncertainty explains why worsening uncertainty and capital conditions matter for investments that are substantially irreversible and can be delayed (Carozzani & D’Alpaos, 2025; Dixit & Pindyck, 1994; Kim et al., 2017; Lazo & Watts, 2023; Y. Li, Pan, et al., 2026; Ofori et al., 2021; Or et al., 2024; Pindyck, 1991; Zhang et al., 2016).
What remains less developed is the integration of these strands within one transparent project model. Much of the geopolitical literature relies on indices, panel regressions, time-series models or aggregate transition indicators. These approaches are valuable for identifying whether geopolitical risk affects renewable outcomes and for revealing heterogeneity across countries and periods. They are less suited to showing how a geopolitical shock enters the cost structure of a specific renewable project. Conversely, conventional LCOE analysis commonly treats installed cost and discount rates as exogenous assumptions without tracing their deterioration to geopolitical mechanisms.
The gap is therefore methodological and conceptual rather than a claim that geopolitical risk and renewable energy have not been studied. The missing link is the project-level translation of external geopolitical stress into distinct physical and financial variables, the direct comparison of their effects on generation economics and the assessment of their interaction. The present study addresses this gap by consolidating overlapping physical pressures into their effect on CAPEX, representing financial risk through WACC and comparing both channels within a common LCOE framework. This design makes it possible to ask not only whether geopolitical risk matters, but which project-economic pathway matters more under the modeled stress conditions.
The Egyptian case adds analytical value because several exposures coexist. Egypt has high-quality solar resources and experience with utility-scale renewable deployment, but it also operates within an emerging market financing environment and is geographically embedded in a maritime system whose strategic importance can become a source of vulnerability during regional escalation. African finance research shows that high costs of capital can materially shape electricity technology costs (Calcaterra et al., 2024; Dato et al., 2025), while emerging-market project evidence demonstrates how financing can offset falling PV technology costs (Monroy Gomez & Jansen, 2026). Egypt therefore illustrates a wider challenge facing renewable-rich emerging economies; natural-resource advantage can coexist with financial and supply chain exposure. The case is valuable not because it is unique, but because it allows these mechanisms to be examined together in a setting where they are simultaneously relevant.
3. Conceptual and Analytical Framework
Building on the theoretical and empirical foundations discussed above, the analytical framework translates geopolitical uncertainty into two principal project-level economic pathways. The first is a physical supply side channel. Geopolitical escalation can affect internationally traded metals and materials, manufacturing energy costs, freight rates, insurance, shipping routes, equipment availability and delivery schedules. Evidence on critical minerals and PV trade networks demonstrates that geopolitical shocks can alter input prices and propagate through geographically concentrated technology supply chains (Cui et al., 2025; Depraiter & Goutte, 2025; Gervais et al., 2025; W. Li et al., 2025; Saadaoui et al., 2025). Because several of these mechanisms overlap, their principal project-level effect is represented through changes in installed project CAPEX rather than as separate direct multipliers of LCOE.
This aggregation is important for both conceptual clarity and model discipline. Commodity prices, manufacturing costs, freight, insurance and delivery risk are not independent additions to the final cost of a PV project. Higher mineral or energy costs can already be reflected in module and equipment prices, while freight and insurance can be incorporated into delivered equipment quotations. Modelling each pressure as a separate percentage increase in LCOE would therefore risk counting the same cost escalation more than once. Representing the physical channel through CAPEX captures the cumulative effect on the capital requirement while preserving transparency.
The second pathway is a financial risk channel. Heightened geopolitical uncertainty can increase perceived sovereign, currency, regulatory and project risk, raise required returns and widen financing premia. This pathway is represented through changes in WACC. The distinction is supported by evidence showing that renewable electricity costs are highly sensitive to financing conditions, particularly in emerging and developing economies (Calcaterra et al., 2024; Dato et al., 2025; IEA, 2024; Monroy Gomez & Jansen, 2026; Wildgruber et al., 2026; Wilson et al., 2025). WACC is therefore treated as a project-economic variable that can deteriorate independently of physical equipment costs.
The two channels converge in the LCOE calculation but enter it differently. CAPEX changes the amount of capital that must be recovered over the project lifetime. WACC changes the rate at which future generation and costs are discounted and therefore the annualized burden of the upfront investment. When supply side disruption increases CAPEX while geopolitical uncertainty concurrently increases WACC, the higher cost of capital applies to an enlarged investment base. The model identifies this interaction as an amplification mechanism rather than assuming that physical and financial shocks are simply additive.
A parallel strategic mechanism operates in the opposite direction. Greater instability in fossil fuel markets can increase the energy security value of domestic renewable generation and strengthen policy incentives for diversification. Recent empirical evidence is consistent with this duality. Geopolitical risk has been found to accelerate renewable transition under some conditions while constraining it under others, with nonlinear and development-specific effects increasingly documented (He et al., 2025; Javed et al., 2025; Y. Li, Hanif, et al., 2026; Lin & Zhang, 2025; Shittu et al., 2025; Zhu et al., 2026). Geopolitical risk may therefore reinforce the strategic imperative for renewable deployment while weakening the near-term economic conditions under which renewable projects are financed and constructed. This tension constitutes the inherent paradox examined in the study.
The theory of investment under uncertainty provides the interpretive link between these pathways. Utility-scale PV requires a substantial and largely irreversible upfront commitment, while project initiation can often be delayed. A deterioration in CAPEX or WACC therefore does more than raise a static cost metric; it worsens the conditions under which irreversible capital is committed and can increase the attractiveness of preserving flexibility until uncertainty is resolved (Carozzani & D’Alpaos, 2025; Dixit & Pindyck, 1994; Y. Li, Pan, et al., 2026; Ofori et al., 2021; Or et al., 2024; Pindyck, 1991). The present study does not estimate the value of waiting, but the theoretical framework explains why the modeled deterioration in project economics is relevant to investment behavior.
The framework consequently distinguishes between a shock’s geopolitical origin and the project variable through which it enters the model. This separation allows the analysis to answer three connected questions; how geopolitical stress can change solar PV LCOE, whether the physical CAPEX channel or financial WACC channel is more influential, and whether simultaneous deterioration creates additional vulnerability. The structure also produces a direct policy interpretation because resilience measures can be mapped to the channel they are intended to address; procurement and supply chain measures primarily protect the physical capital requirement, while financial de-risking and institutional credibility primarily protect the cost and availability of capital.
4. Materials and Methods
4.1. Research Design
This study employs a quantitative scenario-based techno-economic approach to assess the sensitivity of utility-scale solar PV generation costs in Egypt to geopolitical risk. Investment under uncertainty theory informs the selection and interpretation of the economic transmission channels but is not itself estimated within the model. The analysis does not calculate an option value or optimal investment threshold; instead, it evaluates how geopolitical stress can change the underlying economics of a capital-intensive investment through CAPEX and WACC. The analysis does not seek to predict the economic consequences of a specific future conflict trajectory. Instead, it develops progressively adverse stress scenarios using parameter ranges informed by contemporary empirical, institutional and peer-reviewed evidence.
The procedure consists of four stages. First, a representative utility-scale PV reference system is specified. Second, its LCOE is calculated using discounted lifetime costs and electricity generation. Third, progressively adverse physical and financial stress assumptions are introduced through CAPEX and WACC. Fourth, sensitivity, decomposition and robustness analyses evaluate the independent and combined effects of these channels.
Scenario analysis is appropriate to this research question because the purpose is conditional rather than predictive. The model asks what happens to project economics if identifiable geopolitical transmission channels deteriorate within plausible bounds. It does not assign probabilities to military or diplomatic outcomes and does not infer that any particular escalation will mechanically produce the selected CAPEX or WACC values. This distinction is especially important in a fast-moving geopolitical setting, where deterministic forecasts would quickly become obsolete and could overstate the precision supported by available evidence.
The design also improves transparency relative to the original weighted-variable approach. Each scenario input has a direct economic interpretation and enters a standard project-cost model through a defined parameter. The resulting LCOE can therefore be reproduced, decomposed and subjected to sensitivity testing. The analytical emphasis is consequently placed on the stability of the mechanism and ranking of effects rather than on claiming a single precise forecast of future Egyptian solar costs.
4.2. Reference Solar PV System
The system represents a normalized utility-scale PV project rather than a particular Egyptian plant. The 10% real WACC should not be interpreted as an estimate of the economy-wide cost of renewable finance in Egypt. It represents a comparatively de-risked reference-project financing environment used as the analytical baseline. The high-risk boundary is informed by broader financing evidence for emerging and African markets and by the Egypt-specific WACC estimate reported by Terrapon-Pfaff et al. (Calcaterra et al., 2024; Dato et al., 2025; Terrapon-Pfaff et al., 2025; Wildgruber et al., 2026).

Table 1.
Reference solar PV system assumptions.
| Parameter | Reference assumption |
| Installed CAPEX | USD 750/kW |
| Fixed O&M | USD 7/kW-year |
| Capacity factor | 23% |
| Economic lifetime | 25 years |
| Annual degradation | 0.5% |
| Real WACC | 10% |
| Fuel expenditure | 0 |
4.3. LCOE Model
LCOE is calculated as the ratio of the present value of lifetime project costs to the present value of lifetime electricity generation;
where CAPEX is initial capital expenditure, O&Mₜ is operation and maintenance expenditure in year t, r is the real WACC, and Eₜ is electricity generated in year t.
where CF is the capacity factor and d is annual degradation. The resulting metric represents plant-level generation cost; it is not a retail electricity tariff or PPA price and excludes wider electricity-system expenditures outside the generating asset. Under the reference assumptions, the model produces an estimated LCOE of approximately USD 46.2/MWh (4.62 US cents/kWh), close to contemporary international utility-scale PV benchmarks (IRENA, 2026a).
LCOE = [CAPEX + Σₜ(O&Mₜ/(1+r)ᵗ)] / [Σₜ(Eₜ/(1+r)ᵗ)] (1)
Eₜ = 8760 × CF × (1−d)ᵗ−1 (2)
4.4. Geopolitical Transmission Channels and Scenario Calibration
Physical pressures arising from commodity prices, manufacturing-energy conditions, freight, insurance and logistics are consolidated into CAPEX shocks to reduce double counting. Financial stress is represented independently through WACC. Four progressively adverse scenarios are examined.
Table 2.
Geopolitical stress scenario assumptions.
| Scenario | CAPEX assumption | Real WACC |
| Reference | USD 750/kW | 10.0% |
| Limited escalation | +5% | 11.0% |
| Prolonged disruption | +12% | 12.5% |
| Severe escalation | +20% | 14.0% |
These values are calibrated stress assumptions rather than conflict-specific forecasts. The severe CAPEX assumption is bounded against historical evidence showing that concurrent commodity and freight price surges could raise utility-scale PV investment costs by around 25% (EA, 2021). Capacity factor, lifetime and technological performance are held constant across the primary scenarios to isolate economic and financing transmission.
The calibration follows a bounded-stress logic. The reference case represents a comparatively de-risked project environment rather than an economy-wide average for Egypt. Subsequent scenarios progressively deteriorate both the physical and financial conditions facing the project. The severe CAPEX shock is deliberately kept within an empirically defensible stress envelope; historical IEA analysis found that concurrent commodity and freight price pressures could raise utility-scale PV investment costs by around one quarter. The model’s +20% central severe shock therefore represents substantial disruption without adopting the historical upper stress value as the baseline assumption.
The WACC calibration is interpreted in the same way. The 10% reference value is a modelling baseline for a comparatively bankable project, while the 14% severe value represents a high-risk boundary rather than a claim that conflict itself causes a four-percentage-point increase. This is consistent with evidence that renewable financing conditions in emerging markets can be materially more expensive than in advanced economies and that financing costs can dominate project economics even when technology costs decline (Calcaterra et al., 2024; Dato et al., 2025; IEA, 2024; Monroy Gomez & Jansen, 2026; Wilson et al., 2025). The calibration therefore uses observed financing environments to bound the scenarios while avoiding a causal claim that the available evidence cannot support.
4.5. Sensitivity and Robustness Analysis
A two-way sensitivity analysis varies CAPEX and WACC independently. Robustness is then examined across alternative reference specifications covering CAPEX of USD 650–900/kW, capacity factors of 21–25%, economic lifetimes of 25–30 years, degradation rates of 0.3–0.75%, and reference WACC values of 8–12%. An additional +25% severe CAPEX stress test is included. The purpose is to assess the stability of the relative findings rather than identify a single universally applicable LCOE for Egyptian PV.
Robustness testing serves two purposes. First, it examines whether the headline percentage changes are artifacts of a single set of engineering and financial assumptions. Second, and more importantly, it tests whether the ordering of the transmission channels is stable. For a scenario study, the latter is the stronger criterion; absolute LCOE necessarily changes when capacity factor, lifetime or baseline financing conditions change, but a policy conclusion is more credible when the relative importance of financing and physical cost stress persists across plausible specifications.
The parameter ranges also separate variables that primarily influence the absolute cost level from those that alter geopolitical sensitivity. Capacity factor, for example, changes the quantity of electricity over which project costs are spread and therefore materially affects absolute LCOE. Because it is held constant between the reference and geopolitical cases, however, it should have a much smaller effect on the relative percentage increase produced by a given CAPEX or WACC shock. Testing this explicitly helps distinguish resource-quality uncertainty from geopolitical-cost vulnerability.
5. Results
5.1. Reference-Case LCOE
The reference specification produces an estimated LCOE of 4.62 US cents/kWh (USD 46.2/MWh). Its proximity to contemporary international utility-scale solar PV cost evidence provides an external reasonableness check on the reference specification (IRENA, 2026a).
5.2. Geopolitical Stress Scenarios
The severe scenario therefore increases plant-level PV LCOE from approximately USD 46/MWh to USD 71/MWh despite no deterioration in solar resource, capacity factor, project lifetime or underlying technological performance. Figure 1 visualizes the progressive increase across the four geopolitical stress scenarios.
Table 3.
LCOE across geopolitical stress scenarios.
| Scenario | CAPEX | WACC | LCOE (¢/kWh) | Change from reference |
| Reference | USD 750/kW | 10.0% | 4.62 | — |
| Limited escalation | +5% | 11.0% | 5.17 | +11.9% |
| Prolonged disruption | +12% | 12.5% | 6.04 | +30.9% |
| Severe escalation | +20% | 14.0% | 7.06 | +52.9% |
5.3. Physical Versus Financial Transmission
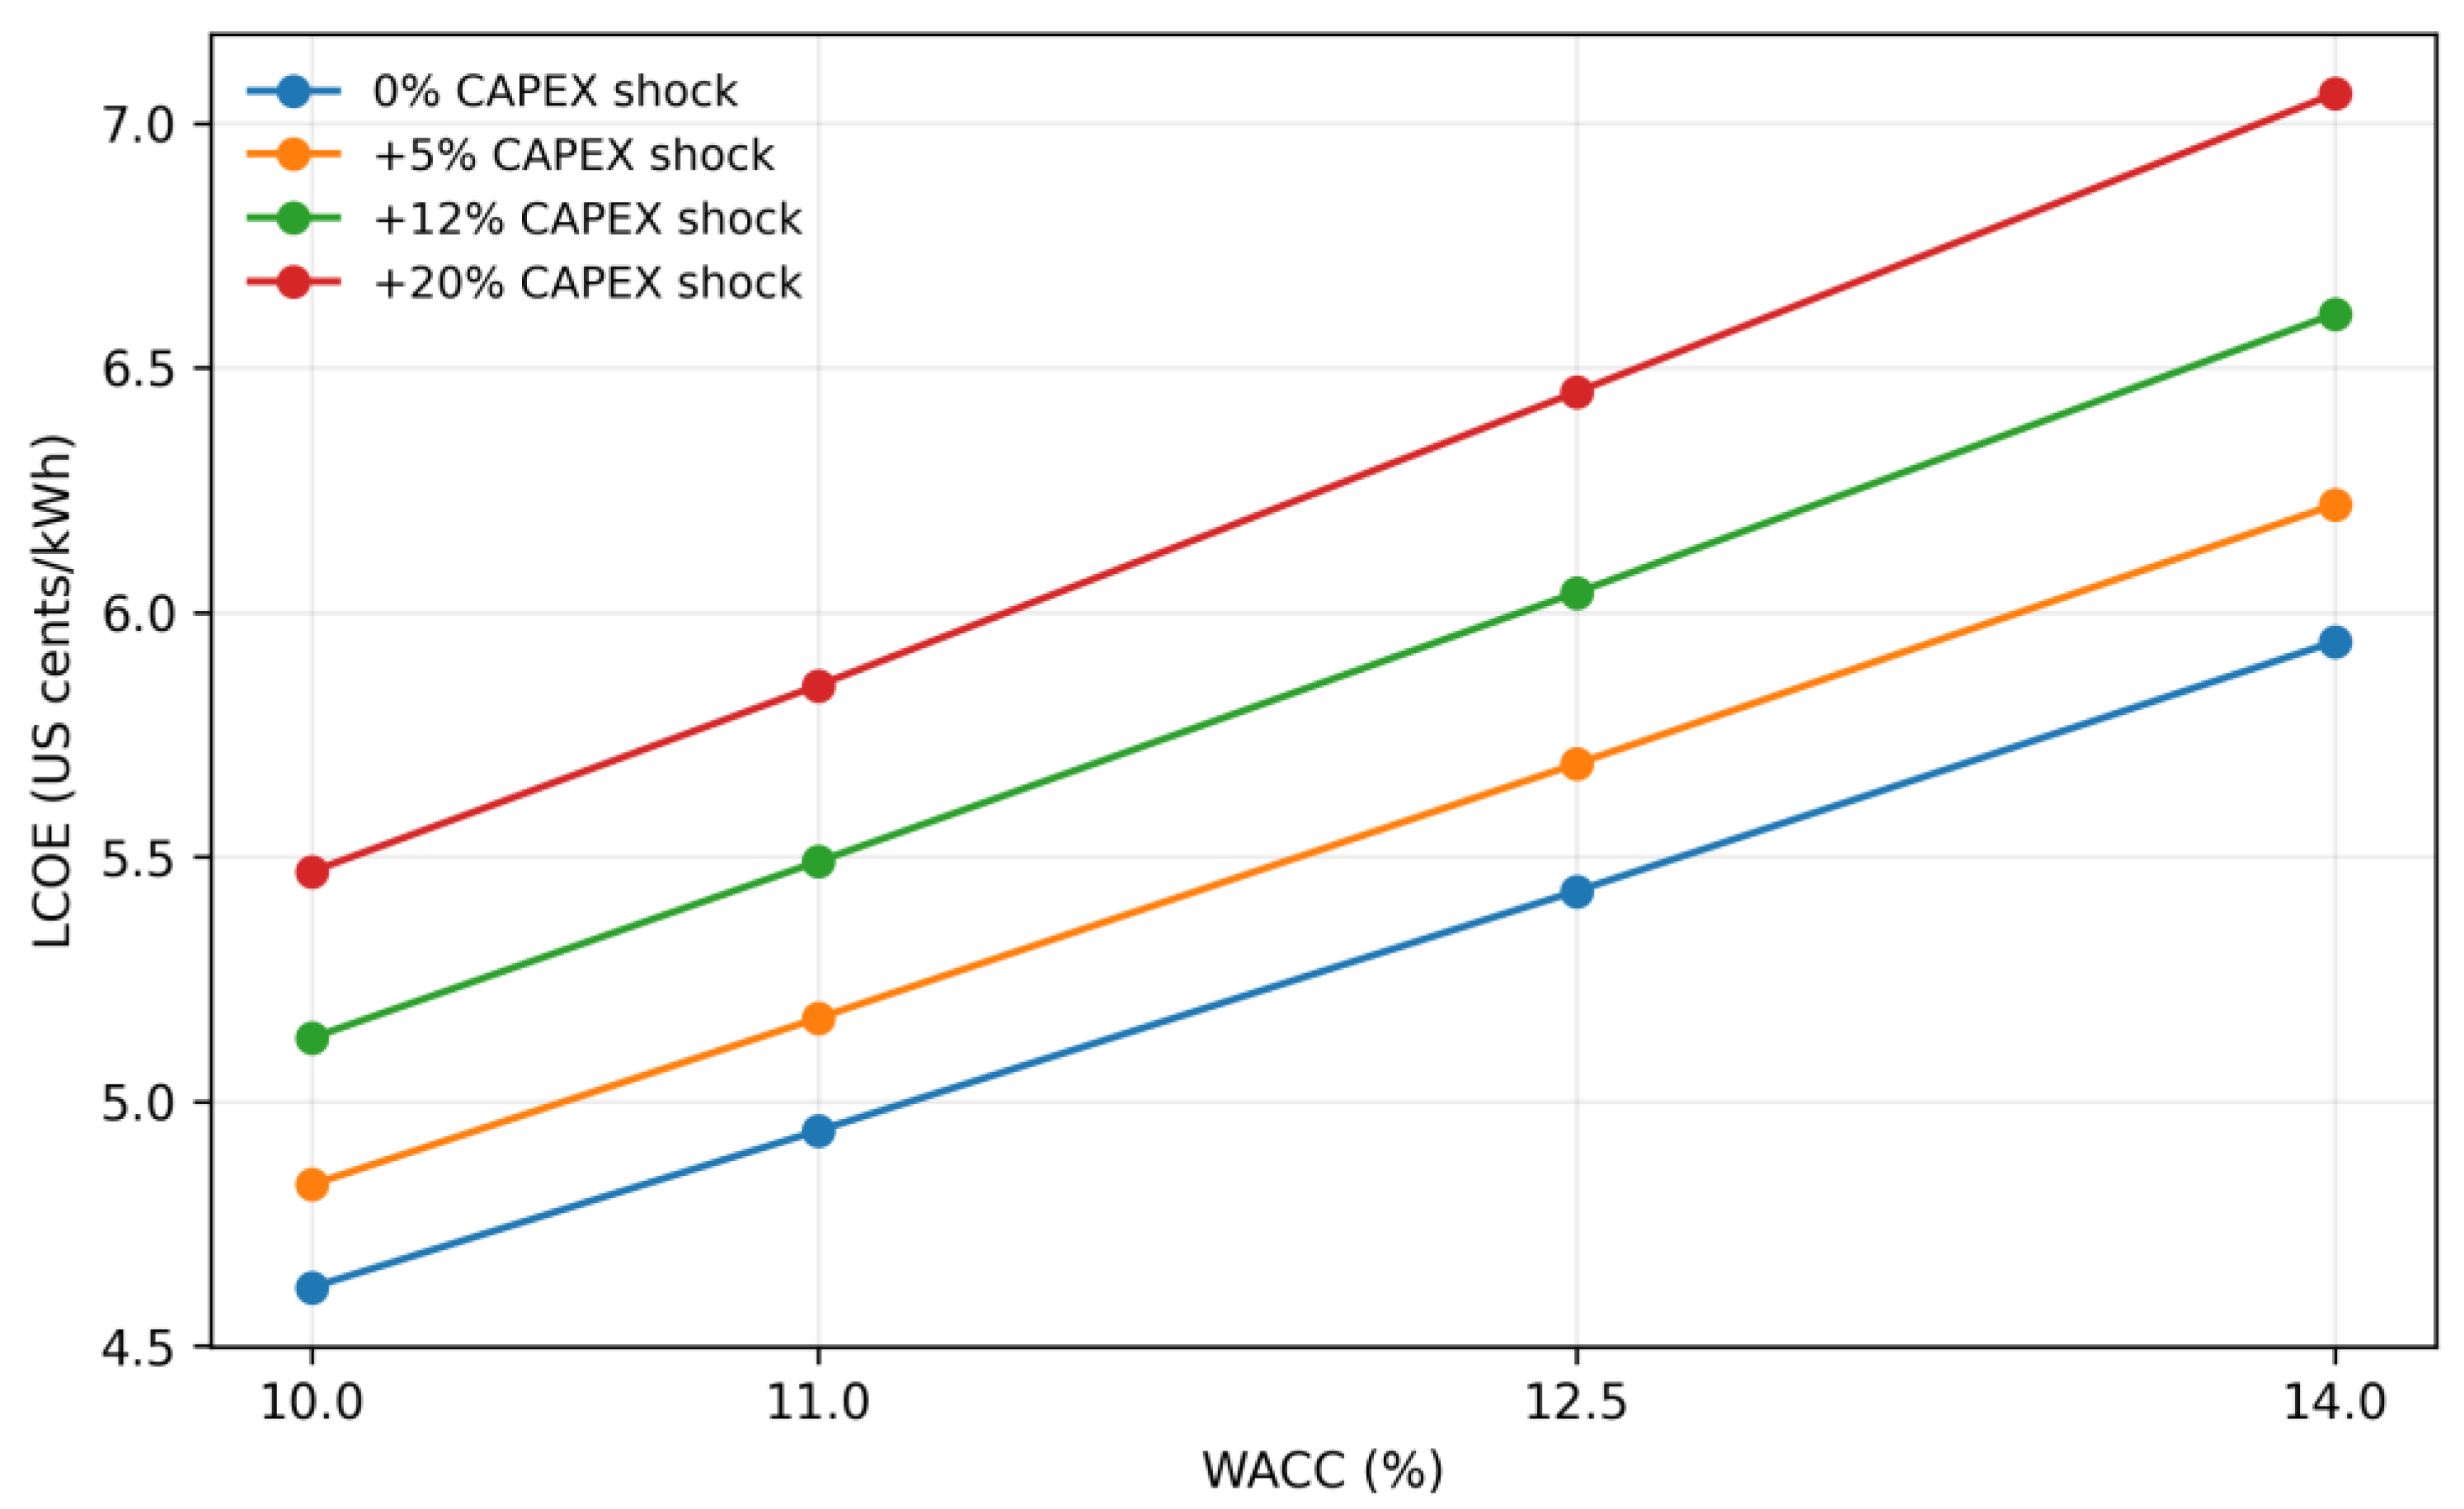
Holding WACC at 10% while increasing CAPEX by 20% raises LCOE from 4.62 to approximately 5.47 ¢/kWh, an increase of 18.4%. Holding CAPEX at its reference level while increasing WACC from 10% to 14% raises LCOE to approximately 5.94 ¢/kWh, an increase of 28.7%. Thus, under the central stress assumptions, deteriorating financing conditions exert a larger independent effect on LCOE than the physical CAPEX shock.
Table 4.
Two-way sensitivity of LCOE to CAPEX and WACC.
| CAPEX shock | WACC 10% | WACC 11% | WACC 12.5% | WACC 14% |
| 0% | 4.62 | 4.94 | 5.43 | 5.94 |
| +5% | 4.83 | 5.17 | 5.69 | 6.22 |
| +12% | 5.13 | 5.49 | 6.04 | 6.61 |
| +20% | 5.47 | 5.85 | 6.45 | 7.06 |
Figure 2.
CAPEX–WACC sensitivity of utility-scale solar PV LCOE.
5.4. Combined Amplification
The combined severe scenario increases LCOE by approximately 52.9%. The combined effect exceeds the sum that would result from applying the independently calculated absolute CAPEX and financing effects to the original reference LCOE because higher financing costs are applied to a larger capital requirement. The additional amplification is approximately 0.27 ¢/kWh, equivalent to roughly 5.8% of reference LCOE beyond the simple additive independent effects.
5.5. Robustness
Across 162 tested combinations of CAPEX, capacity factor, lifetime, degradation and reference WACC, the CAPEX-only severe effect ranges approximately 17.8–18.9%, the WACC-only effect ranges approximately 25.3–35.8%, and the combined effect ranges approximately 48.9–61.3%. The WACC effect exceeds the CAPEX effect in all 162 specifications. Increasing the severe CAPEX assumption from +20% to +25% raises the combined severe-case LCOE from approximately 7.06 to 7.34 ¢/kWh, corresponding to an increase of approximately 59% relative to the central reference case.
The robustness exercise provides an important qualification to the headline 52.9% result. That percentage is scenario-specific and should not be interpreted as a universal estimate of the cost of geopolitical escalation. Across the tested configurations, the combined severe effect spans a wider range, reflecting differences in the baseline project and financing environment. What is substantially more stable is the directional conclusion; both channels raise LCOE, their combination is more damaging than either channel alone, and the financing shock remains the larger independent effect in each tested specification.
This stability shifts the interpretation from a point estimate to a structural finding. Even under alternative assumptions concerning installed cost, solar productivity, asset life, degradation, and reference financing conditions, the model continues to identify the cost of capital as the more powerful severe-stress lever. The robustness analysis therefore supports the policy interpretation that reducing financing risk can materially improve resilience even when governments have limited ability to control global commodity prices or maritime disruptions. It also provides the basis for interpreting the findings in relation to investment under uncertainty; the conditions governing capital commitment remain economically consequential even when the underlying renewable resource and technology are unchanged.
6. Discussion
6.1. Renewable-Resource Advantage Does Not Guarantee Investment Resilience
The first major finding is that renewable-resource quality and technology maturity do not by themselves guarantee resilient investment conditions. The reference case produces a competitive LCOE because Egypt combines strong solar resources with the assumed baseline cost and financing conditions. Once CAPEX and WACC are stressed, however, LCOE rises materially even though irradiation, degradation, operating performance and project lifetime remain unchanged. The result isolates a central point for renewable investment analysis; project competitiveness can deteriorate because the economic environment surrounding capital formation worsens, not because the renewable technology becomes less productive.
This finding is consistent with the broader literature showing that geopolitical risk affects renewable transition outcomes in heterogeneous ways. Positive effects reported in some studies can be interpreted as evidence that geopolitical pressure strengthens incentives for diversification and domestic energy production (He et al., 2025). Negative effects reported elsewhere indicate that uncertainty, institutional constraints and market conditions can impede the translation of that strategic incentive into investment (Javed et al., 2025; Lin & Zhang, 2025; Shittu et al., 2025). Development-specific evidence is especially relevant to Egypt because Y. Li, Hanif, et al. (2026) find that geopolitical risk is more likely to hinder renewable progress in developing economies, where financial and institutional constraints are more binding.
The nonlinear evidence of Zhu et al. (2026) further helps interpret the scenario results. Their 2026 finding of an inverted U-shaped relationship implies that moderate geopolitical pressure can strengthen transition incentives before excessive risk becomes economically disruptive. The present study does not estimate such a threshold and should not be read as a direct test of that relationship. It instead provides a project-level mechanism that is compatible with it. As geopolitical stress intensifies, the strategic rationale for renewable deployment can remain strong while CAPEX and WACC deteriorate sufficiently to weaken project economics. This mechanism also helps reconcile the positive solar-transition effect reported by He et al. (2025) with studies documenting adverse or development-specific investment effects (Javed et al., 2025; Y. Li, Hanif, et al., 2026; Lin & Zhang, 2025; Shittu et al., 2025).
This distinction matters for policy because renewable potential and renewable bankability are not equivalent. High irradiation, falling module prices and ambitious deployment targets can coexist with financing or procurement conditions that delay projects or raise the price at which electricity must be sold. The result therefore supports a broader interpretation of energy transition resilience in which resource abundance is necessary but not sufficient; resilience also depends on whether projects remain financeable and constructible when external conditions deteriorate.
6.2. Financing as a Geopolitical Transmission Channel
The second major finding is that deterioration in financing conditions produces a larger independent effect on LCOE than the central physical CAPEX shock. This result is economically plausible because solar PV concentrates expenditure before electricity generation begins, so the price attached to upfront capital materially shapes lifetime generation cost. It is consistent with IEA evidence that financing can constitute around half or more of utility-scale PV LCOE in emerging and developing economies (IEA, 2024) and with recent empirical work showing elevated WACC across African power sectors and substantial cross-country and technology variation in renewable financing costs (Dato et al., 2025; Wildgruber et al., 2026).
The result also aligns closely with Wilson et al. (2025), who show that renewable power is more sensitive to the cost of capital than fossil generation. Their analysis demonstrates that changes in financing conditions can materially alter the relative competitiveness of solar PV even without a corresponding change in technology cost. This provides external support for treating WACC as a structural driver of LCOE rather than a secondary financial assumption.
Monroy Gomez and Jansen (2026) provide an especially useful project-level comparator. Their analysis of utility-scale solar PV in Brazil shows that financing costs became an increasingly important component of project economics even as CAPEX declined. The similarity is not that the Brazilian and Egyptian financing environments are identical, nor that the same WACC response should be expected. The important common finding is that favorable solar technology costs can be offset by expensive capital. The present study extends this insight by placing financing deterioration within an explicit geopolitical stress framework and comparing it directly with a physical CAPEX shock.
The African evidence further strengthens the interpretation. Dato et al. (2025) show that electricity-sector WACC across 48 African countries remains consistently above global and other regional benchmarks. Calcaterra et al. (2024) demonstrate that financing premia can materially affect both the affordability and pace of energy transition in developing economies. Wildgruber et al. (2026) show that renewable WACC varies systematically by country, year and technology. These studies collectively support the proposition that financing conditions are not an external detail of renewable deployment; they are part of the technology’s realized economic competitiveness.
Viewed through the theory of investment under uncertainty, the financing result is particularly important. The deterioration in project economics does not arise solely because the physical asset becomes more expensive; it also arises because the conditions governing the commitment of capital become less favorable. The finding that the WACC shock produces a larger independent effect than the CAPEX shock is consistent with the theoretical proposition that uncertainty and financing conditions can materially influence capital-intensive investment decisions (Dixit & Pindyck, 1994; Pindyck, 1991). The present analysis does not estimate the option value of waiting, but it demonstrates a project-level mechanism through which heightened risk can weaken the economic attractiveness of immediate renewable investment.
The financing result also changes how geopolitical exposure should be interpreted. A narrow supply security perspective would concentrate on whether modules, inverters or critical materials can physically reach Egypt. The model shows that a project may remain fully feasible in physical terms and still suffer substantial economic deterioration if the return required by lenders and equity investors rises. Renewable investment applications similarly show that financing, policy, exchange-rate and market uncertainties can affect investment value and timing in developing economies (Kim et al., 2017; Ofori et al., 2021; Or et al., 2024). Geopolitical resilience is therefore partly an issue of maintaining investability during periods of heightened uncertainty.
6.3. Physical and Financial Risks Are Mutually Reinforcing
The third major finding is that physical and financial risks should not be treated as independent additive shocks. Y. Li, Xia, et al. (2026) show how geopolitical risk can undermine shipping supply chain resilience through logistics disruption, freight volatility and customs inefficiency, while UNCTAD documents substantial Red Sea rerouting and transport-cost pressures (UNCTAD, 2025). PV-specific research similarly shows that concentrated production networks and trade disruptions can propagate shortages across multiple stages of the value chain (Cui et al., 2025; Gervais et al., 2025; W. Li et al., 2025). If financing conditions concurrently deteriorate, the higher financing rate applies to the enlarged capital requirement. Renewable investment resilience therefore requires attention to both physical supply chains and financial architecture.
Critical mineral evidence reinforces this interaction. Saadaoui et al. (2025) show that geopolitical risk can affect critical mineral prices, while Depraiter and Goutte (2025) find stronger connectedness among geopolitical risk, rare earth markets and clean technology markets during periods of elevated tension. These pressures can feed into equipment and project costs. At the same time, the uncertainty generated by the same geopolitical episode can influence country and project risk premia. A single geopolitical origin can therefore produce economically distinct physical and financial consequences.
The amplification observed in the combined scenarios has a straightforward project-finance interpretation. A higher CAPEX increases the amount of capital that must be recovered, while a higher WACC increases the financing burden attached to that capital. When both occur together, the project experiences more than a simple narrative accumulation of risks because the financing rate is applied to a larger upfront requirement. This does not imply a universal nonlinear geopolitical law. It is an arithmetic consequence of the project structure represented in the model and should be interpreted as evidence that concurrent shocks deserve explicit treatment rather than one-at-a-time sensitivity analysis.
The interaction also has practical implications for risk management. Procurement strategies that cap equipment-price exposure may still leave a project vulnerable if political or macroeconomic uncertainty raises financing costs before financial close. Conversely, concessional finance cannot fully neutralize a severe increase in imported equipment and logistics costs. Resilience strategies are therefore likely to be more effective when financial de-risking is coordinated with supplier diversification, contractual risk allocation, logistics planning and appropriate inventory or scheduling flexibility.
Recent PV supply chain research supports this balanced approach. Erol et al. (2024) emphasize organizational and sourcing capabilities that improve resilience, while Cui et al. (2025) and Chen et al. (2025) show that excessive isolation or localization can sacrifice the cost advantages created by internationally integrated production. The policy objective is therefore not to eliminate interdependence but to reduce vulnerability to concentrated points of failure while preserving the efficiencies that have contributed to falling PV costs.
6.4. The Inherent Paradox of Geopolitical Risk and Renewable Energy Investment
The results provide project-level content to the inherent paradox introduced at the beginning of the study. Geopolitical instability can increase the strategic value of renewable energy because renewable generation reduces recurrent exposure to internationally traded fossil fuels and fuel-price shocks (He et al., 2025; IRENA, 2026b; Tol, 2023; Vakulchuk et al., 2020). Yet the same instability can make renewable investment more expensive through supply chain and financing channels. The recent empirical literature strongly supports this non-uniform interpretation. Some studies identify geopolitical risk as a driver of renewable transition (He et al., 2025; Matallah et al., 2023), others find adverse effects on investment or transition performance (Javed et al., 2025; Lin & Zhang, 2025; Shittu et al., 2025), and recent cross-country evidence identifies nonlinear and development-specific responses (Y. Li, Hanif, et al., 2026; Zhu et al., 2026).
The present results help explain how these apparently contradictory findings can coexist. Aggregate transition outcomes reflect both strategic incentives and project-level constraints. A government may strengthen renewable targets because energy autonomy has become more valuable, while developers and financiers simultaneously face higher equipment costs, more uncertain delivery schedules or larger required returns. The same geopolitical episode can therefore push policy ambition and project economics in opposite directions. Whether observed deployment accelerates or slows depends on which force dominates and on the capacity of institutions and financial systems to absorb the shock.
The theory of investment under uncertainty provides a useful interpretation of this tension. When investment is substantially irreversible and can be deferred, greater uncertainty can increase the value of waiting for additional information before capital is committed (Dixit & Pindyck, 1994; Pindyck, 1991). Renewable energy applications similarly show that uncertainty can affect investment value and timing (Carozzani & D’Alpaos, 2025; Kim et al., 2017; Lazo & Watts, 2023; Y. Li, Pan, et al., 2026; Ofori et al., 2021; Or et al., 2024; Zhang et al., 2016). The present model does not demonstrate that Egyptian developers will postpone investment, nor does it estimate an optimal deferral threshold. It shows instead that geopolitical stress can materially worsen the CAPEX and financing conditions that enter project appraisal, creating economic circumstances under which the theoretical incentive to preserve flexibility becomes more plausible.
The paradox also clarifies why a short-run increase in renewable LCOE should not be interpreted as evidence against renewable deployment. Higher project cost under geopolitical stress does not eliminate the longer-run energy security value of reducing exposure to volatile fossil fuel markets. Equally, the strategic desirability of renewables does not make financing constraints or supply chain exposure disappear. A robust policy response must therefore recognize both sides of the relationship rather than portraying geopolitical instability as uniformly beneficial or uniformly harmful to renewable investment.
This interpretation also sharpens the paper’s contribution relative to the empirical geopolitical literature. The study does not seek to estimate whether the net aggregate effect of geopolitical risk on renewable transition is positive or negative. It identifies two project-level pathways through which adverse economic pressure can arise even when the strategic case for renewables is strengthening. In this sense, the CAPEX and WACC channels provide a microeconomic mechanism that can help interpret the heterogeneous signs reported in macro and panel studies.
7. Research and Policy Implications
The findings support a policy approach that treats renewable investment resilience as the joint product of financial conditions, supply chain preparedness and credible long-term policy. Because geopolitical stress can affect more than one project variable at the same time, measures directed at a single source of vulnerability may leave substantial residual exposure. The quantitative ranking nevertheless provides a basis for prioritization; under the modeled assumptions, the financial WACC channel exerts the larger independent effect and therefore deserves particular attention.
First, financial de-risking should be treated as a core component of renewable energy and energy security policy. Measures can include guarantees, blended and concessional finance, political risk mitigation, currency risk management, predictable regulatory frameworks and stable project revenue arrangements (Calcaterra et al., 2024; Dato et al., 2025; IEA, 2024; IRENA, 2026b). These instruments can reduce the premium investors attach to uncertainty and improve the conditions under which capital is mobilized. From the perspective of the theory of investment under uncertainty, credible arrangements can also reduce uncertainty surrounding the terms on which irreversible capital is committed.
Stable auction and PPA frameworks are especially important because they influence the predictability of future cash flows. Transparent permitting, credible offtake arrangements, timely payment mechanisms and consistent regulatory treatment can reduce project-specific risk even when broader geopolitical conditions cannot be controlled. Such measures do not eliminate external instability; they reduce the extent to which that instability is transmitted into the financing terms of domestic renewable projects.
Second, supply chain resilience remains essential. Supplier diversification, improved procurement strategies, selective development of domestic manufacturing capacity, logistics redundancy and improved inventory planning can reduce exposure to single-source or single-route disruptions. Recent PV research supports diversification and resilience building but also cautions that highly isolationist localization strategies can introduce significant cost inefficiencies (Chen et al., 2025; Cui et al., 2025; Erol et al., 2024; Gervais et al., 2025; W. Li et al., 2025). The policy objective should therefore be resilience and optionality rather than autarky.
Supply chain policy should also distinguish between components according to their strategic importance and substitutability. Full domestic replication of every stage of the PV value chain is neither necessary nor necessarily efficient. A more selective approach can identify equipment, services or logistics routes where diversification, regional sourcing, inventory management or domestic capability would materially reduce exposure to disruption. This is consistent with the evidence that geographic concentration creates vulnerability while international integration has also delivered substantial diffusion and cost benefits (Chen et al., 2025; Cui et al., 2025; W. Li et al., 2025).
Third, geopolitical stress testing should become part of renewable energy planning and project appraisal. Transition strategies often employ a single CAPEX and discount-rate assumption or vary one parameter at a time. The present results show why concurrent shocks deserve explicit attention. Public agencies, lenders and developers can evaluate projects under combined physical and financing stress to identify whether a project that appears competitive under central assumptions remains viable when geopolitical conditions deteriorate.
Stress testing can also improve the targeting of policy instruments. If project viability is most sensitive to WACC, guarantees, concessional capital or revenue stabilization may provide greater value than broad equipment subsidies. If physical exposure dominates in a particular technology or project, procurement diversification and logistics measures may deserve priority. Where both channels are material, coordinated interventions can prevent one form of de-risking from being undermined by deterioration in the other.
Finally, energy transition planning should integrate the strategic and investment sides of energy security. Geopolitical instability can strengthen the case for accelerating renewable deployment while simultaneously increasing the cost of doing so. Policy credibility becomes particularly valuable under these conditions because it helps prevent external uncertainty from being compounded by domestic uncertainty. For Egypt and comparable emerging economies, the objective is therefore not simply to expand renewable capacity, but to maintain the financial and physical conditions that allow investment to continue when the strategic value of renewables is highest.
Implications for Egypt
For Egypt, the findings suggest that energy transition resilience cannot be assessed solely through renewable-capacity targets, resource potential or technological costs. Recent Egypt-specific evidence indicates that geopolitical risk can weaken energy security over the long run even as renewable energy contributes positively to resilience (Hassanen et al., 2026). The present results add a project-level dimension to that finding. Egypt’s solar resource can remain unchanged while the economics of converting that resource into electricity deteriorate through higher CAPEX and WACC.
The distinction between renewable potential and renewable bankability is therefore central. Egypt can possess strong solar irradiation, available land, policy ambition and experience with utility-scale deployment while individual projects remain sensitive to the terms on which international and domestic capital is mobilized. The financing result is particularly relevant in light of wider African evidence showing elevated WACC and substantial financing premia (Calcaterra et al., 2024; Dato et al., 2025). Improving bankability can preserve more of the economic value created by Egypt’s natural-resource advantage.
The results also suggest that the Suez and Red Sea context should be considered in renewable planning beyond its conventional relevance to hydrocarbons and trade revenues. Maritime disruption can affect the delivery and cost of clean energy equipment, while the broader geopolitical episode can concurrently influence risk perception in financial markets. This creates a cross-sectoral policy problem involving energy, investment, trade, transport and financial institutions rather than a purely technological renewable-energy issue.
Egypt-specific evidence and the present project analysis are therefore complementary rather than competing. Hassanen et al. (2026) establish that geopolitical risk is relevant to national energy security. The present study shows how a geopolitical stress episode can be translated into the economics of a utility-scale solar project through physical and financial channels. Together, the two levels of analysis suggest that energy security policy should consider not only the composition of the energy system but also the resilience of the investment conditions required to expand that system.
The Egyptian case also has broader relevance for other renewable-rich emerging economies. Many such countries combine strong natural resources with imported equipment, foreign-currency exposure, high financing costs and sensitivity to global logistics. The precise parameter values will differ across markets, but the analytical lesson is transferable; abundant renewable resources do not automatically produce resilient renewable investment when the cost and availability of capital and technology inputs remain exposed to external shocks.
8. Limitations and Future Research
The geopolitical scenarios are calibrated stress tests rather than forecasts; the study does not claim that particular military or diplomatic developments will produce predetermined changes in Egyptian PV CAPEX or WACC. Physical supply side pressures are aggregated into CAPEX to avoid double counting, without separately estimating the contribution of each underlying mechanism. The model represents a generic utility-scale PV project rather than a specific Egyptian investment, while WACC is represented through scenario values rather than estimated econometrically as a causal response to geopolitical escalation. LCOE captures plant-level generation economics and does not incorporate wider electricity-system costs.
The scenarios are intentionally ordinal rather than probability weighted, which avoids false precision but prevents estimation of an expected LCOE conditional on the likelihood of each geopolitical state. In addition, the theory of investment under uncertainty provides an interpretive foundation rather than a formally tested real options model; the analysis does not estimate option values, investment triggers, or optimal deferral timing. Exchange-rate effects are also held outside the central model, although currency movements may interact with imported equipment costs, foreign-currency financing, WACC, and CAPEX in the Egyptian context. Future research could address these limitations using probabilistic geopolitical scenarios, stochastic commodity and freight modelling, dynamic WACC and exchange-rate estimation, project-specific financing data, and formal real options valuation.
Finally, the analysis focuses on utility-scale solar PV rather than the electricity system as a whole. Storage, transmission expansion, curtailment, and system-balancing requirements become increasingly important as variable renewable penetration rises. The results should therefore be interpreted as evidence of investment vulnerability at the generation-asset level. Future research could integrate geopolitical stress into capacity-expansion or power-system models to examine whether the relative importance of financial and physical vulnerabilities persists at system scale.
9. Conclusions
This study examined to what extent geopolitical escalation associated with the US–Israel–Iran conflict can affect utility-scale solar PV economics and renewable energy investment conditions in Egypt through two interconnected mechanisms, physical supply side pressures affecting CAPEX and financial risk pressures affecting WACC. Drawing on the theory of investment under uncertainty, a scenario-based techno-economic framework was developed to evaluate these channels independently and jointly while interpreting their implications for a capital-intensive and substantially irreversible investment.
The reference system produces an estimated LCOE of approximately 4.62 US cents/kWh. Under progressively adverse geopolitical stress assumptions, LCOE increases to approximately 5.17 cents/kWh under limited escalation, 6.04 cents/kWh under prolonged disruption and 7.06 cents/kWh under severe combined stress. The severe scenario therefore produces an increase of approximately 52.9% relative to the reference case despite unchanged solar-resource and technological conditions.
The decomposition analysis identifies financing as the stronger independent transmission mechanism. A 20% CAPEX shock increases LCOE by approximately 18.4%, whereas increasing WACC from 10% to 14% increases it by approximately 28.7%. This result remains consistent across the alternative reference specifications examined. Concurrent physical and financial deterioration further produces an amplification effect because higher financing costs are applied to a larger upfront capital requirement. The result is consistent with recent evidence emphasizing the sensitivity of renewable power to financing conditions and the importance of WACC in emerging and African electricity markets (Dato et al., 2025; Monroy Gomez & Jansen, 2026; Wildgruber et al., 2026; Wilson et al., 2025).
The findings are consistent with the broader theoretical expectations of the theory of investment under uncertainty, although the study does not constitute a direct test of real options theory. Geopolitical stress can deteriorate the economic conditions under which renewable capital is committed even as the strategic value of renewable energy increases. This provides a project-level explanation for why recent empirical research can report positive, negative, and nonlinear relationships between geopolitical risk and renewable transition outcomes (He et al., 2025; Javed et al., 2025; 2026; Lin & Zhang, 2025; Shittu et al., 2025; Zhu et al., 2026). The apparent contradiction can arise because stronger strategic incentives coexist with weaker financing and procurement conditions.
The contribution of the study therefore lies in integrating strands of literature that are often examined separately. Geopolitical research establishes that external risk affects renewable transition, supply chain research identifies physical vulnerabilities, renewable-finance research demonstrates the importance of WACC, and the theory of investment under uncertainty explains why deteriorating conditions matter for irreversible capital commitment. Bringing these elements into a common LCOE framework shows how geopolitical stress can be translated into project economics and allows the physical CAPEX channel and financial WACC channel to be compared directly.
For geopolitically exposed emerging economies like Egypt, the policy implication is that abundant renewable resources do not necessarily imply resilient renewable investment conditions. Financial de-risking and supply chain resilience should therefore be taken into account when formulating energy policy. Maintaining credible revenue arrangements, improving access to affordable capital, diversifying vulnerable procurement pathways and institutionalizing combined geopolitical stress testing can help preserve investment viability when external instability increases. Renewable energy can strengthen long-run energy security but realizing that strategic value depends on maintaining the conditions under which projects can continue to be financed and built.
Funding
This research received no external funding.
Data Availability Statement
This study is based on secondary data and published sources cited in the manuscript. The scenario assumptions and model parameters required to reproduce the reported calculations are provided in the Materials and Methods and Results sections. A supplementary calculation file may be provided with the final submission.
Conflicts of Interest
The author declares no conflicts of interest.
References
- Abdelmeguid, N., and D. Ibrahiem. 2025. Decarbonizing Egypt’s energy sector: Pathways for an accelerated energy transition. Review of Economics and Political Science 10, 303–322. [Google Scholar] [CrossRef]
- Baumeister, C., and J. D. Hamilton. 2019. Structural interpretation of vector autoregressions with incomplete identification: Revisiting the role of oil supply and demand shocks. American Economic Review 109, 1873–1910. [Google Scholar] [CrossRef]
- Bondarenko, Y., V. Lewis, M. Rottner, and Y. Schüler. 2024. Geopolitical risk perceptions. Journal of International Economics 152, 104005. [Google Scholar] [CrossRef]
- Calcaterra, M., L. Aleluia Reis, P. Fragkos, T. Briera, H. S. de Boer, F. Egli, J. Emmerling, G. Iyer, S. Mittal, F. H. J. Polzin, M. W. J. L. Sanders, T. S. Schmidt, A. Serebriakova, B. Steffen, D. J. van de Ven, D. P. van Vuuren, P. Waidelich, and M. Tavoni. 2024. Reducing the cost of capital to finance the energy transition in developing countries. Nature Energy 9, 1241–1251. [Google Scholar] [CrossRef]
- Caldara, D., M. Cavallo, and M. Iacoviello. 2019. Oil price elasticities and oil price fluctuations. Journal of Monetary Economics 103, 1–20. [Google Scholar] [CrossRef]
- Carozzani, A., and C. D’Alpaos. 2025. The real option approach to investment decisions in hybrid renewable energy systems: A systematic literature review. Energies 18, 5535. [Google Scholar] [CrossRef]
- Chatziantoniou, I., M. Filippidis, G. Filis, and D. Gabauer. 2021. A closer look into the global determinants of oil price volatility. Energy Economics 95, 105092. [Google Scholar] [CrossRef]
- Chen, Z., B. Gu, D. Yu, and C. Wang. 2025. Quantifying the accelerated diffusion and cost savings of global solar photovoltaic supply chains. iScience 28, 111610. [Google Scholar] [CrossRef]
- Cui, C., K. E. Lonergan, and G. Sansavini. 2025. Policy-driven transformation of global solar PV supply chains and resulting impacts. Nature Communications 16, 6742. [Google Scholar] [CrossRef]
- Dallmann, C., M. Schmidt, and D. Möst. 2022. Between path dependencies and renewable energy potentials: A case study of the Egyptian power system. Energy Strategy Reviews 41, 100848. [Google Scholar] [CrossRef]
- Dato, P., M. Dioha, H. Hessou, B. Houenou, B. Mukhaya, M. A. Okyere, and L. Odarno. 2025. Computation of weighted average cost of capital (WACC) in the power sector for African countries and the implications for country-specific electricity technology cost. Applied Energy 397, 126333. [Google Scholar] [CrossRef]
- Depraiter, L., and S. Goutte. 2025. Geopolitical risk and clean energy investments: Exploring the role of rare earths. International Review of Financial Analysis 100, 103965. [Google Scholar] [CrossRef]
- Dixit, A. K., and R. S. Pindyck. 1994. Investment under uncertainty. Princeton University Press. [Google Scholar] [CrossRef]
- Erol, I., I. Peker, T. Benli, I. M. Ar, and C. Searcy. 2024. Exploring the enablers for building resilience in solar photovoltaic energy supply chains. Operations Management Research 17, 1100–1125. [Google Scholar] [CrossRef]
- Flint, C. 2022. Introduction to geopolitics, 4th ed. Routledge. [Google Scholar]
- Flouros, F., V. Pistikou, and V. Plakandaras. 2022. Geopolitical risk as a determinant of renewable energy investments. Energies 15, 1498. [Google Scholar] [CrossRef]
- Gad, K. S., G. Crevani, and E. Colombo. 2025. An integrated modelling framework to address the energy trilemma in Egypt and Nile East Basin. Energy Strategy Reviews 58, 101689. [Google Scholar] [CrossRef]
- Gervais, E., B. Sprecher, S. Nold, P. Brailovsky, and R. Kleijn. 2025. Tracing the propagation of disruptions in supply chain scenarios: A case study of photovoltaics diversification. Resources, Conservation and Recycling 212, 107948. [Google Scholar] [CrossRef]
- Hassanen, H. H. M., H. M. Hamouda, A. S. Hamid, M. R. El-Hawary, and H. T. S. M. Abdelaal. 2026. Geopolitical risk and energy security in Egypt: Evidence from 2000–2023. Sustainability 18, 4801. [Google Scholar] [CrossRef]
- He, Z.-W., C.-C. Lee, and S. S. Sharma. 2025. The impact of geopolitical risks on the renewable energy transition. Energy Economics 143, 108278. [Google Scholar] [CrossRef]
- International Energy Agency. 2021. What is the impact of increasing commodity and energy prices on solar PV, wind and biofuels? Available online: https://www.iea.org/articles/what-is-the-impact-of-increasing-commodity-and-energy-prices-on-solar-pv-wind-and-biofuels (accessed on 21 September 2026).
- International Energy Agency. 2024. Reducing the cost of capital: Strategies to unlock clean energy investment in emerging and developing economies. Available online: https://www.iea.org/reports/reducing-the-cost-of-capital (accessed on 21 September 2026).
- International Renewable Energy Agency. 2026a. Renewable power generation costs in 2025. Available online: https://www.irena.org/Publications/2026/Jul/Renewable-Power-Generation-Costs-in-2025 (accessed on 21 September 2026).
- International Renewable Energy Agency. 2026b. Transitioning away from fossil fuels: A roadmap powered by renewables, electrification and grid enhancement. Available online: https://www.irena.org/-/media/Files/IRENA/Agency/Publication/2026/May/IRENA_OUT_TAFF_RE_electrification_grids_2026.pdf (accessed on 21 September 2026).
- Javed, A., M. Usman, N. Abid, and A. Rapposelli. 2025. Unveiling the impact of geopolitical risk, climate policy uncertainty, environmental policy stringency, and financial efficiency on renewable energy investment in the USA: Evidence from novel dynamic simulated ARDL approach. Journal of Environmental Management 393, 127057. [Google Scholar] [CrossRef]
- Jorgenson, D. W. 1963. Capital theory and investment behavior. American Economic Review 53, 247–259. [Google Scholar]
- Kilian, L., M. Plante, and A. W. Richter. 2024. Geopolitical oil price risk and economic fluctuations. Working Paper No. 2403. Federal Reserve Bank of Dallas.
- Kim, K., H. Park, and H. Kim. 2017. Real options analysis for renewable energy investment decisions in developing countries. Renewable and Sustainable Energy Reviews 75, 918–926. [Google Scholar] [CrossRef]
- Lazo, J., and D. Watts. 2023. The use of real options approach in solar photovoltaic literature: A comprehensive review. Sustainable Energy Technologies and Assessments 57, 103204. [Google Scholar] [CrossRef]
- Li, F., C. Yang, Z. Li, and P. Failler. 2021. Does geopolitics have an impact on energy trade? Empirical research on emerging countries. Sustainability 13, 5199. [Google Scholar] [CrossRef]
- Li, W., M. Zhang, and M. Han. 2025. Geographical linkage and trade disruption within global photovoltaic supply chains. Geography and Sustainability 6, 100323. [Google Scholar] [CrossRef]
- Li, Y., M. W. Hanif, M. Wen, A. K. Khoso, and W. M. Khoso. 2026. Geopolitical risks and the global renewable energy transition: Implications for energy security and economic resilience. Energy Reports 15, 108875. [Google Scholar] [CrossRef]
- Li, Y., Z. Pan, Y. Chu, J. Yuan, Y. Shi, and Y. Li. 2026. Investment decision of concentrated solar power under uncertainty based on real options approach: A case study in Qinghai Province, China. Renewable Energy 256, 124299. [Google Scholar] [CrossRef]
- Li, Y., X. Xia, Y. Wang, and Q. Huang. 2026. Geopolitical risk and shipping supply chain resilience: Systemic characteristics, impact mechanisms, and the security of logistics nodes. Systems 14, 427. [Google Scholar] [CrossRef]
- Lin, B., and Z. Zhang. 2025. China’s renewable energy development in the crosshairs of geopolitical risk: Impact mechanisms, heterogeneity, and policy imperatives. Journal of Environmental Management 390, 126317. [Google Scholar] [CrossRef]
- Matallah, S., A. Matallah, and N. Hilmi. 2023. The transition to renewable energy is inevitable as geopolitical risks drag on: A closer empirical look at MENAT oil importers. Environmental Science and Pollution Research 30, 105293–105307. [Google Scholar] [CrossRef]
- Monroy Gomez, S., and M. Jansen. 2026. Risks, rates, and rays: Domestic financing shapes Brazil’s utility-scale solar PV costs in regulated auctions. Energy Economics 157, 109297. [Google Scholar] [CrossRef]
- Ofori, C. G., G. A. Bokpin, A. Q. Q. Aboagye, and A. Afful-Dadzie. 2021. A real options approach to investment timing decisions in utility-scale renewable energy in Ghana. Energy 235, 121366. [Google Scholar] [CrossRef]
- Or, B., G. Bilgin, E. C. Akcay, I. Dikmen, and M. T. Birgonul. 2024. Real options valuation of photovoltaic investments: A case from Turkey. Renewable and Sustainable Energy Reviews 192, 114200. [Google Scholar] [CrossRef]
- Pinchetti, M. 2024. Geopolitical risk and inflation: The role of energy markets (CFM Discussion Paper No. 2431). Centre for Macroeconomics. [Google Scholar]
- Pindyck, R. S. 1991. Irreversibility, uncertainty, and investment. Journal of Economic Literature 29, 1110–1148. [Google Scholar]
- Saadaoui, J., R. Smyth, and J. Vespignani. 2025. Ensuring the security of the clean energy transition: Examining the impact of geopolitical risk on the price of critical minerals. Energy Economics 142, 108195. [Google Scholar] [CrossRef]
- Shittu, I., A. Saqib, C. F. Tang, and Y. Chen. 2025. Does global geopolitical risk jeopardize the clean energy transition? New evidence from a global panel. Renewable and Sustainable Energy Reviews 223, 116006. [Google Scholar] [CrossRef]
- Terrapon-Pfaff, J., J. Braun, S. R. Ersoy, M. Prantner, J. Kern, and P. Viebahn. 2025. Country risk impacts on export costs of green hydrogen and its synthetic downstream products from the Middle East and North Africa. Frontiers in Energy Research 13, 1546876. [Google Scholar] [CrossRef]
- Tol, R. S. J. 2023. Navigating the energy trilemma during geopolitical and environmental crises. (ADBI Working Paper No. 1372). Asian Development Bank Institute. [Google Scholar] [CrossRef]
- United Nations Conference on Trade and Development. 2025. Review of maritime transport 2025: Staying the course in turbulent waters. Available online: https://unctad.org/publication/review-maritime-transport-2025 (accessed on 21 September 2026).
- Vakulchuk, R., I. Overland, and D. Scholten. 2020. Renewable energy and geopolitics: A review. Renewable and Sustainable Energy Reviews 122, 109547. [Google Scholar] [CrossRef]
- Verduzco-Bustos, G., and F. Zanetti. 2025. The effects of geopolitical oil price shocks. (CESifo Working Paper No. 12606). CESifo. [Google Scholar]
- Wildgruber, K., C. Thompson, and F. Egli. 2026. An empirically validated open-access approach for calculating the cost of capital of renewables. Energy Strategy Reviews 64, 102103. [Google Scholar] [CrossRef]
- Wilson, C., G. Shrimali, and B. Caldecott. 2025. Financing costs and the competitiveness of renewable power. iScience 28, 113777. [Google Scholar] [CrossRef]
- Zhang, M. M., P. Zhou, and D. Q. Zhou. 2016. A real options model for renewable energy investment with application to solar photovoltaic power generation in China. Energy Economics 59, 213–226. [Google Scholar] [CrossRef]
- Zhu, X., H. Fang, and J. Ma. 2026. Geopolitical risk and renewable energy transition: An economic analysis of the inverted U-shaped effect. Economic Analysis and Policy 92, 837–854. [Google Scholar] [CrossRef]
Figure 1.
LCOE across geopolitical stress scenarios.
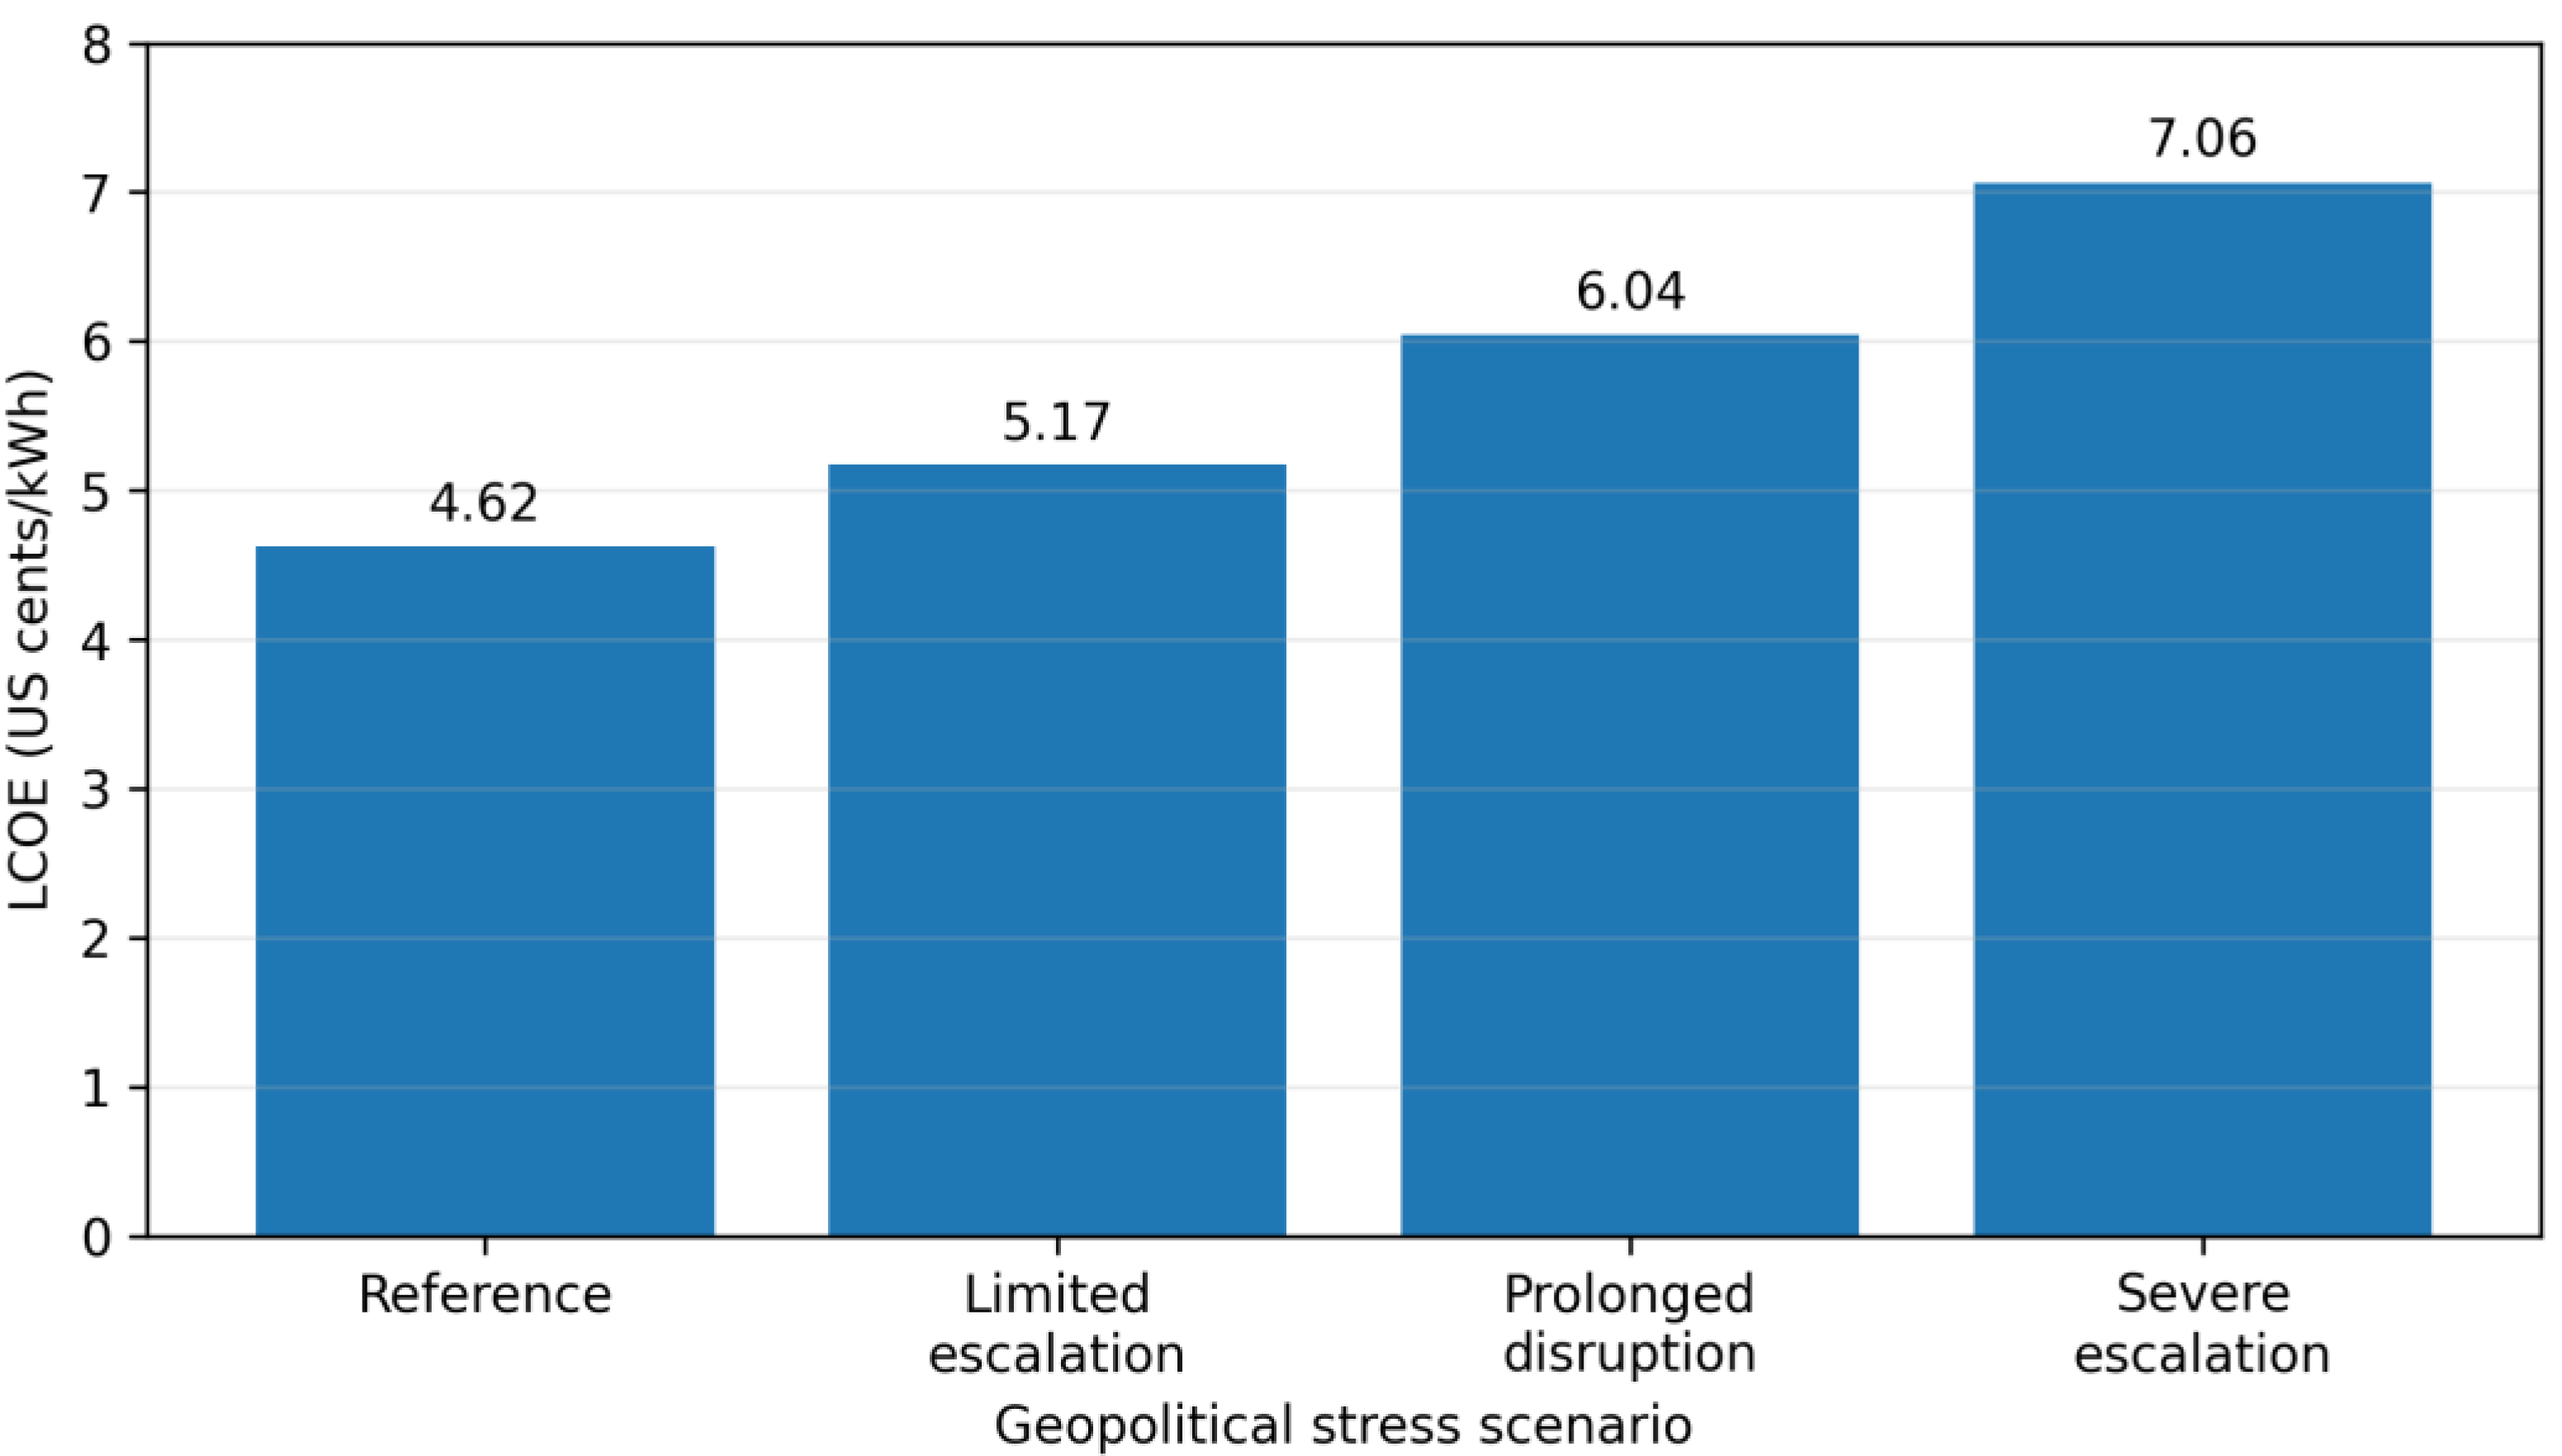
Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content. |
© 2026 by the authors. Licensee MDPI, Basel, Switzerland. This article is an open access article distributed under the terms and conditions of the Creative Commons Attribution (CC BY) license (http://creativecommons.org/licenses/by/4.0/).
Copyright: This open access article is published under a Creative Commons CC BY 4.0 license, which permit the free download, distribution, and reuse, provided that the author and preprint are cited in any reuse.