

Submitted:
22 September 2026
Posted:
23 September 2026
You are already at the latest version
Abstract
Geopolitical conflicts and the energy transition complicate risk linkages among conventional energy, new energy, ESG assets and gold. Using quantile time–frequency connectedness and complex network analysis, this study examines an ESG index, coal and natural gas equity indices, five new energy subsector indices, an aggregate new energy index and a gold ETF across market states and horizons. Under normal conditions, wind power, photovoltaics, natural gas and new energy vehicles are net transmitters, while the remaining markets are net receivers. Total spillovers rise sharply under extreme conditions, and short-term spillovers dominate across market states. Static estimates show stable transmission roles for photovoltaics, wind power, natural gas and gold across quantiles and frequency bands, alongside conditional switching in other markets. Dynamic estimates reveal additional variation over time. The Russia–Ukraine conflict is associated with a sustained increase in long-term connectedness, whereas COVID-19 primarily coincides with short-term volatility pulses. Network analysis identifies coal as a central node and photovoltaics as a major transmission hub within new energy. These findings inform market-state- and horizon-specific risk monitoring, asset allocation and crisis responses.
Keywords:
risk spillovers
; quantile time–frequency connectedness
; complex networks
; new energy subsectors
; ESG index
; Russia–Ukraine conflict
1. Introduction
Energy is not only the material foundation of production in modern society but also a key strategic instrument in national security and international relations. As global geopolitical conflicts intensify, energy availability and the capacity for diversified allocation have become core components of national competitiveness (Dao et al., 2025). Meanwhile, accelerating financialization has gradually transformed energy commodities into dual-purpose assets with both commodity and financial attributes. In this context, energy prices are no longer determined solely by physical supply and demand but are increasingly influenced by global liquidity, speculative positions and cross-market risk contagion (Cheng and Xiong, 2014). This financialization trend has increasingly blurred the boundaries between risks in energy markets and external financial markets. Bidirectional volatility spillovers and contagion occur between them, such that persistent fluctuations in one market significantly intensify fluctuations in the other, revealing the underlying mechanisms through which cross-market risk transmission affects energy pricing (Akusta and Gün, 2026).
The multiple, intertwined dimensions of energy-market volatility are currently reflected in the differentiated yet closely interrelated roles of three core asset groups. Conventional fossil fuels, represented by coal and natural gas, remain the stabilizing foundation of global energy supply, but their price fluctuations are closely linked to geopolitical risk, making them initial transmission nodes in the energy-risk network. New energy industries represented by wind power, photovoltaics, hydropower, nuclear power and new energy vehicles are expanding rapidly under carbon peaking and carbon neutrality strategies. However, substantial differences in technological maturity, policy dependence and supply-chain resilience lead to significantly different sensitivities to conventional energy price shocks. For example, renewable energy equipment has a positive bidirectional relationship with oil prices, whereas alternative fuels do not exhibit this relationship (Dinh, 2025). This internal heterogeneity means that treating new energy as a single sector can be highly misleading: individual markets may play diametrically opposed roles in the risk transmission network, and aggregation can substantially conceal their structural differences. Green financial assets represented by ESG thematic indices and traditional safe-haven assets represented by gold ETFs perform the respective functions of guiding capital allocation and hedging risk during severe energy-market turbulence. Research shows that incorporating ESG assets mitigates risk in green energy equity markets (Wu et al., 2024; Jiménez et al., 2026). Gold displays particularly pronounced dynamic safe-haven properties during crises, although its effectiveness differs markedly across market states and asset classes (Zheng et al., 2026). These three asset groups form a complex cross-market risk network through cost transmission, substitution effects, investor expectations and capital allocation. Conventional energy price shocks reach the green financial system after being amplified or buffered through ESG investment preferences and green capital allocation, while gold, as a safe-haven asset, may simultaneously absorb risk spillovers from both conventional and new energy. A comprehensive understanding of current risk linkages in the energy–financial system therefore requires a unified framework incorporating conventional energy markets, new energy subsectors, ESG green financial assets and gold, with systematic examination of their differentiated transmission paths and network structures across market states and time horizons.
Global climate governance and the extensive implementation of carbon peaking and carbon neutrality objectives have made structural transformation of energy systems a central issue in national economic policy. China is accelerating the large-scale development of new energy industries represented by wind power, photovoltaics, hydropower, nuclear power and new energy vehicles, seeking a green, low-carbon transition while safeguarding energy security. Conventional energy nevertheless retains a foundational position in the current energy supply structure (Jin et al., 2024). Its price fluctuations profoundly affect the risk–return characteristics of new energy markets through cost transmission, substitution effects and investor expectations. Meanwhile, gold is a distinctive asset combining commodity, financial and safe-haven attributes. Under multiple uncertainty shocks, its defensive function is further strengthened through inflation hedging and risk avoidance (Li and Li, 2026). In this environment of overlapping risks, the mechanisms linking conventional energy, new energy subsectors and gold are no longer merely an asset-pricing issue. They have become a major practical concern directly affecting national energy security strategies and the prevention of systemic financial market risk.
A review of the literature shows that existing studies have established important foundations in several areas. As ESG investment has become increasingly widespread, researchers have begun to examine linkages between ESG indices and new energy (Ahad et al., 2024). Wu et al. (2024) find that clean energy and ESG markets are major net transmitters under different conditions, that cross-market spillovers are higher in extreme than in normal markets, and that dependence between these two markets weakens after the Russia–Ukraine conflict while dependence within conventional energy strengthens. Jiménez et al. (2026) likewise find that extreme events, including COVID-19 and geopolitical conflicts, significantly alter the correlation structure between ESG and new energy assets, causing a sharp increase in tail dependence. However, most existing studies treat new energy as an aggregate sector and do not examine in depth the differentiated transmission paths linking its subsectors with ESG indices. Studies based on VAR models, the DY spillover index and copulas have also verified significant transmission from oil and natural gas prices to new energy equity returns. Du and Xu (2024) find significant time-varying spillovers between clean and conventional energy markets, with markedly greater intensity during extreme events. Cunado et al. (2024) examine gold's safe-haven function during energy-market turbulence and find that gold effectively hedges the downside risk of energy assets in extreme downside markets, although its safe-haven properties vary significantly across market conditions and frequency bands.
Existing studies have made important contributions in their research coverage and methods, but three limitations remain. First, regarding research coverage, the vast majority treat new energy as an aggregate sector and do not investigate in depth the differentiated transmission paths connecting its subsectors—such as photovoltaics, wind power, nuclear power, hydropower and new energy vehicles—with ESG indices, conventional energy and gold. These subsectors differ substantially in technological maturity, policy dependence, supply-chain length and capital intensity, necessarily producing heterogeneous responses to risk. Aggregation obscures considerable valuable structural information and may also lead to systematic misclassification of the risk transmission role of new energy. Second, mainstream methodological tools have limitations. Most focus on conditional correlations around the mean and struggle to capture tail-risk spillovers under extreme market conditions, even though systemic risk often accumulates and develops in the tails. These methods also typically fail to distinguish short-term market shocks from long-term structural risk transmission. Their limited ability to identify risk duration and changes in the structural baseline makes it difficult to meet regulators' need for differentiated interventions across horizons. Third, in characterizing crisis dynamics, existing studies generally treat geopolitical events such as the Russia–Ukraine conflict as short-term pulse shocks and lack systematic tests of whether they cause an irreversible structural upward shift in the central level of energy-network risk connectedness. The absence of this assessment directly affects the reliability of long-term energy strategies and asset-allocation decisions across cycles. If a geopolitical conflict is indeed a crisis involving a structural upward shift, the baseline of energy-market connectedness has changed permanently, rather than returning to its previous state after a one-off disturbance.
This study addresses these limitations through three targeted improvements. First, in its research coverage, it is the first to disaggregate new energy into five subsectors—nuclear power, hydropower, photovoltaics, wind power and new energy vehicles—and incorporate them alongside an ESG thematic index, coal, natural gas and a gold ETF in a unified analytical framework. This permits systematic comparison of their differentiated roles in the risk transmission network and addresses the limitations of aggregate analysis. Second, it employs the quantile time–frequency connectedness method proposed by Chatziantoniou et al. (2022), combining QVAR with VAR spectral decomposition. The method decomposes spillovers simultaneously across quantile levels corresponding to normal, extreme downside and extreme upside conditions, and across short- and long-term frequency bands. It thus precisely captures tail-risk heterogeneity and horizon dependence, overcoming the blind spots of conventional methods in the joint quantile and frequency dimensions. Third, in assessing external shocks, the study combines complex network analysis with time–frequency connectedness. By comparing systematic changes in long-term spillovers before and after the conflict, it quantitatively tests whether the Russia–Ukraine conflict produces an irreversible structural upward shift in the central level of energy-network volatility, thereby distinguishing a short-term pulse crisis from a crisis involving a long-term structural upward shift.
The contributions of this study are threefold. First, it moves beyond the conventional treatment of new energy as an aggregate sector and, for the first time, incorporates ESG, conventional energy, new energy subsectors and a gold ETF within one framework, producing complex network maps covering these four asset groups. Under normal market conditions, wind power, photovoltaics, natural gas and new energy vehicles are net transmitters, whereas ESG, nuclear power, hydropower, coal and gold are net receivers. This finding corrects the simplified view in the literature that new energy is a homogeneous passive receiver and reveals a functional division between subsectors dominated by risk transmission and those dominated by risk absorption. Second, the study moves beyond conventional mean-based analysis and, for the first time, characterizes the boundaries of conditional role switching and the core of cross-condition stability in a joint quantile and time–frequency framework. Whereas existing research largely assigns static roles at the mean, QVAR and spectral decomposition show that most sectors switch significantly between net transmission and net reception as market states and frequency bands change. In the static estimates, photovoltaics, wind power, natural gas and gold maintain stable roles across quantiles and frequency bands. This transforms the concept of a risk transmission role from a static label into a dynamic function, providing actionable criteria for investors to track role switching in extreme markets and anchor long-term allocations in assets with stable roles. Third, the study departs from the homogeneous treatment of geopolitical events as short-term pulses and, for the first time, distinguishes and empirically tests two heterogeneous crisis transmission mechanisms: short-term pulses and long-term structural upward shifts. Comparing systematic changes in long-term spillovers before and after the Russia–Ukraine conflict confirms that the conflict is not a one-off disturbance but a pivotal event causing an irreversible structural upward shift in the central level of connectedness throughout the energy-risk network. Public health events such as COVID-19, by contrast, produce only sharp but temporary increases in short-term volatility. This distinction answers the strategic question of which crises alter the system's “foundations” and which merely disturb its “walls”, providing a theoretical basis for a differentiated policy toolkit. The study also identifies coal and gold as the net receivers in the extreme upside market, highlighting their distinctive function as core buffers against systemic risk.
2. Literature Review
Conventional energy markets, particularly crude oil and coal, form the core supply side of the global energy–financial system, and their transmission of risk to new energy was among the first issues to attract research attention. Methodologically, early studies mainly used standard VAR models and the spillover index framework proposed by Diebold and Yilmaz (2012), hereafter the DY index, emphasizing static spillover measurement at the mean. Later research gradually introduced more advanced tools, including time-varying parameters, quantile regression and frequency decomposition, to capture asymmetric transmission across market states and horizons.
The empirical findings broadly fall into three categories. The first concerns conventional energy as a net transmitter and new energy as a net receiver. Using a time-varying parameter vector autoregressive (TVP-VAR) model, Lin et al. (2024) find that crude oil price uncertainty has significantly asymmetric effects on ESG and new energy indices, with particularly pronounced spillovers during periods of elevated policy uncertainty. The markets exhibit a strong positive correlation, but transmission intensity changes dynamically with market conditions. Li et al. (2023) use time-domain, extreme-condition and frequency-domain spillover models to examine three clean energy subsectors—clean fuels, renewable energy and energy efficiency—alongside conventional energy and metals. They find that energy efficiency is a net risk transmitter under normal and extreme conditions and over short and long horizons, whereas conventional energy and metals receive risk, suggesting that frequency decomposition can change assessments of sectoral roles. Zhang and Wang (2025) uses QVAR-DY and TVP-VAR models to systematically investigate spillovers between the import prices of four new energy minerals—cobalt, nickel, copper and silicon—and seven green equity industries, including wind power, photovoltaics, energy storage and new energy vehicles. Significant bidirectional spillovers exist between new energy minerals and green equity markets, and their intensity increases markedly under extreme conditions. The second category shows that new energy can switch to net transmission during particular periods. From an extreme volatility spillover perspective, Fasanya and Mubaiwa (2025) show that transmission between clean energy equities and fossil fuels is not fixed. During climate policy shocks or escalating geopolitical tensions, clean energy changes from its normal net-receiver role to a net transmitter, leading the diffusion of cross-market risk. Jiang et al. (2026) construct a complex network using the QVAR-DY spillover index to examine risk spillovers and linkages between Chinese green bonds and commodities. They find a relatively low total spillover level, but greater risk inflows under extreme conditions. Over longer horizons, green bonds can switch from net reception to net transmission and develop strong bidirectional links with non-ferrous metals. The third category focuses on differentiated relationships among individual markets. Taking a hierarchical perspective encompassing primary, secondary and new energy markets, Hui et al. (2025) use generalized variance decomposition to show that secondary and new energy markets occupy central network positions and play key transmission roles. Conventional and new energy exhibit a moderately positive relationship overall, but substantial differences exist among individual markets.
Research on the relationships of conventional energy with ESG indices and gold mainly employs the DY spillover index and its extensions, such as frequency-domain DY and quantile DY, supplemented by copula models of tail dependence, to investigate transmission paths from conventional energy to ESG assets and gold.
Regarding the empirical evidence, Kasraoui and Hemrit (2026) apply the quantile time–frequency method proposed by Chatziantoniou et al. (2022) and find significant bidirectional spillovers between oil and conventional energy on the one hand and ESG markets on the other. Spillover intensity increases sharply under extreme conditions: a weak negative correlation in normal markets becomes strongly positive in extreme states. Examining emerging-market ESG leaders, conventional equity indices and commodities with a DCC-GARCH model, de Boyrie and Pavlova (2024) find that ESG indices are more resilient to commodity shocks in risk management. Conventional energy and ESG have a weak, insignificant relationship at the mean but a moderately positive relationship in volatility, with ESG playing a buffering role. Elsayed et al. (2026) are the first to test the hedging potential of ESG futures against highly polluting energy futures. They find that ESG futures function effectively as safe havens during downside risk in energy markets, particularly over short horizons, providing direct evidence for the use of ESG derivatives in energy-risk management. For gold, Cunado et al. (2024) use wavelet transforms and quantile regression to investigate its safe-haven function during energy-market turbulence. Gold effectively hedges energy assets' downside risk in extreme downside markets, but its safe-haven properties vary significantly across market states and frequency bands. Gold and energy are significantly negatively correlated over long horizons, whereas their short-term correlation is insignificant or even positive. Ha et al. (2022) additionally use a TVP-VAR extended joint connectedness approach to analyze linkages among four markets—energy, crude oil, gold and silver. They find that health shocks significantly affect system-wide dynamic connectedness, which peaks during COVID-19.
Methodologically, research on heterogeneity within new energy and its relationship with ESG has gradually moved from aggregate sector analysis to subsector comparisons, using panel regression, TVP-VAR models and copula-based tail-dependence models.
In the empirical literature, Wu et al. (2024) employ quantile connectedness measures and develop a QVAR-MST method to investigate spillovers and dependence between green financial markets—clean energy, ESG, green bonds, green technology and carbon—and conventional energy markets—coal, crude oil and natural gas—under normal and extreme conditions. Jiménez et al. (2026) find that extreme events, such as COVID-19 and geopolitical conflicts, significantly alter the correlation structure between ESG and new energy assets and sharply increase tail dependence. Weak correlations in normal markets become strongly positive during crises, demonstrating an asymmetric strengthening of tail dependence. Using asymmetric dynamic volatility connectedness, Wu and Qin (2024) find that asymmetric volatility shock transmission between new energy and ESG equities is more persistent than in carbon and green bond markets. Following the COVID-19 outbreak, overall bad-volatility spillovers are also significantly greater than good-volatility spillovers.
For differentiated subsector analysis, Zhang et al. (2025) use an R-vine copula–CoVaR model to examine nonlinear spillovers from oil to five Chinese new energy equity subsectors: photovoltaics, new energy vehicles, energy storage, wind power and nuclear power. Oil generates significantly asymmetric risk spillovers to all five markets. Photovoltaics, energy storage and wind power are more sensitive to downward oil-price shocks, whereas new energy vehicles and nuclear power are more susceptible to the positive effects of upward oil-price shocks. Yang and Ferrer (2026) use a quantile connectedness framework to examine return spillovers among Chinese green bonds, five clean energy equity subsectors, and major financial assets and commodities, including gold, crude oil, conventional bonds and technology equities. Connectedness is moderate under normal conditions but almost doubles in extreme markets. Using quantile connectedness analysis, Yang et al. (2026) find significant structural differentiation within clean energy: nuclear power, wind power and solar energy are net transmitters of systemic risk in extreme crisis and boom states, whereas water and waste treatment have relatively defensive safe-haven allocation value. Mirza et al. (2026) find that environmental exposure has a substantially stronger effect on valuation among non-fossil energy firms than among fossil energy firms, indicating that ESG factors operate through fundamentally different mechanisms across energy subsectors. Nevertheless, research jointly incorporating new energy subsectors, conventional energy markets, ESG indices and gold remains extremely scarce. Most studies address only pairwise combinations of these groups and lack systematic network analysis spanning all four asset groups.
The field has followed a clear methodological progression. Diebold and Yilmaz (2012, 2014) develop the DY spillover index from the forecast-error variance decomposition of a vector autoregressive model to measure the intensity and direction of cross-market volatility spillovers. Their approach establishes a benchmark framework for measuring risk contagion but remains confined to the mean and does not distinguish frequency bands. Baruník and Křehlík (2018) subsequently introduce spectral decomposition into the spillover index, allowing spillovers to be examined over short, medium and long horizons. This reveals horizon-dependent heterogeneity but remains limited to the conditional mean. Building on this approach, Umar et al. (2021) replace the rolling windows of the conventional DY method with a TVP-VAR model, using Kalman filtering and forgetting factors to allow the variance–covariance matrix to change over time. This addresses the difficulty of selecting window length, the loss of observations and the inability to respond to market events in real time. Ando et al. (2022) then incorporate quantile regression into the spillover framework, enabling differentiated analysis across market states. This captures tail risk without simultaneously decomposing the frequency dimension. Chatziantoniou et al. (2022) further integrate spectral decomposition and quantile regression into a quantile time–frequency spillover model. By accommodating heterogeneity in both market states and horizons, it provides the most finely differentiated analytical tool currently available. In research on commodity futures during stressed and normal periods, Abricha et al. (2024) are the first to combine quantiles with futures of different maturities, demonstrating that average measures substantially underestimate extreme risk and that quantile methods are necessary to identify tail connectedness accurately. This provides important empirical support for quantile methods in commodity markets. Research on dynamic return and volatility connectedness between agricultural commodities and oil prices also separates oil-price shocks into three orthogonal categories—supply, demand and risk—providing a methodological example for precisely identifying differences in shock origins.
Taken together, existing studies generally begin with pairwise combinations of three broad groups—conventional energy, new energy and ESG/gold—and gradually extend to heterogeneity among markets within individual sectors. However, systematic research that simultaneously incorporates conventional energy markets, new energy markets, ESG indices and gold ETFs remains extremely scarce, leaving the structure of cross-sector and cross-subsector risk networks unknown. Methodological developments from the DY index to spectral decomposition, quantile regression and integrated quantile time–frequency models have enabled a transition from means to quantiles and from the time domain to joint time–frequency analysis. Nevertheless, applications of Chatziantoniou et al.'s (2022) method at the intersection of energy and ESG are still at an early stage. No study has simultaneously decomposed differentiated transmission paths across quantiles and frequency bands in a complex risk network composed of markets from several sectors. Existing studies also generally treat geopolitical events such as the Russia–Ukraine conflict as short-term pulse shocks to be excluded or controlled for. For example, Ha et al. (2022) divide their sample into pre- and post-pandemic periods using December 31, 2019, the date of the WHO's official announcement of COVID-19. There is a lack of systematic testing of whether such events cause an irreversible structural upward shift in the central level of connectedness among energy, ESG and gold, leaving insufficient empirical support for long-term energy allocation and risk management across cycles.
Accordingly, this study incorporates an ESG index, conventional energy subsectors (coal and natural gas), new energy subsectors (wind power, photovoltaics, hydropower, nuclear power and new energy vehicles) and a gold ETF within a unified framework, overcoming the limitations of pairwise sectoral analysis. Using the quantile time–frequency spillover index of Chatziantoniou et al. (2022), it systematically examines network structures and transmission paths across normal, extreme upside and extreme downside markets and over short and long horizons. It also systematically compares long-term spillovers before and after the conflict to test whether external shocks cause an irreversible increase in the central level of volatility, providing detailed empirical support for energy asset allocation and systemic risk oversight.
3. Methodology and Data
3.1. Quantile Time–Frequency Connectedness
Quantile time–frequency connectedness is an econometric framework for measuring risk or return contagion in a multivariate system under different market conditions (quantiles) and over different cycles (frequencies).
First, the N-dimensional quantile vector autoregressive model QVAR(p) at quantile τ in the time domain is expressed as follows:
Here, xt is an N×1 vector of endogenous variables, p is the lag order, and τ lies within [0,1]. The conditions τ > 0.5 (τ < 0.5) represent positive (negative) shocks. The term μt(τ) is an N×1 conditional intercept vector, is an N×N coefficient matrix, and μt(τ) is an N×1 error vector.
On this basis, the Wold theorem is used to transform the QVAR(p) model into an infinite-order quantile vector moving-average process QVMA(∞):
Here, denotes the impulse-response coefficients, indicating the extent to which affects .
Generalized forecast-error variance decomposition (GFEVD) is then performed to characterize the extent to which each variable’s H-step forecast-error variance is affected by its own shocks or those of other variables. Specifically, it captures the effect of shocks to variable j on variable i:
Since the row sums of are not equal to one, normalization is performed to obtain , such that and . The term measures the contribution of shocks to variable j to the forecast-error variance of variable i at the conditional quantile over the H-step forecast horizon. It therefore measures spillovers from variable j to variable i in the quantile time domain.
The normalized shares yield the directional and total spillover indices at different conditional quantiles. The term NPDCij is the net pairwise spillover index. If NPDCij > 0 (NPDCij < 0), the influence of variable j on variable i is greater (smaller) than the influence of variable i on variable j. The outward spillover index TOi measures the extent to which shocks to variable i are transmitted to other variables, while the inward spillover index FROMi indicates how much variable i receives from shocks to other variables. The net spillover index NETi is the difference between TOi and FROMi, representing the net influence of variable i on the entire network. If NETi > 0 (NETi < 0), the influence of variable i on other variables is greater (smaller) than their influence on variable i, making it a net risk transmitter (receiver). The total spillover index TCL measures overall spillovers in the system. A higher TCL indicates stronger tail-risk contagion linkages and greater tail-risk spillovers among conventional energy, new energy, ESG and gold.
Next, the spectral representation of the variance decomposition is used to decompose the time-domain spillover index into different frequency bands, thereby characterizing the frequency responses generated during the transmission of uncertainty shocks. First, consider the frequency response function:
Here, , and ω denotes frequency. The spectral density of at frequency ω can then be defined as the Fourier transform of :
Here, is the power spectrum, describing how the variance of is distributed across frequency components ω.
Frequency-domain generalized forecast-error variance decomposition combines the spectral density with generalized forecast-error variance decomposition:
Similar to the time-domain measure, is the normalized form of . At a given frequency, represents the portion of variable i in the spectrum that is attributable to shocks to variable j.
To further evaluate short- and long-term connectedness, define a frequency band and aggregate all frequencies within the specified range :
The directional and total spillover indices within a specific frequency band at different quantiles can therefore be obtained as follows:
3.2. Data and Descriptive Analysis
This study selects an ESG index, two conventional energy equity indices, six new energy equity indices and a gold ETF as the sample. The ESG index is the key variable of interest. We therefore select the Huazheng ESG thematic index (ESG), which covers Shanghai and Shenzhen A-shares in the Huazheng All Share Index universe, is adjusted quarterly and is suited to the Chinese market. For conventional energy, we select the equity indices of the dominant coal (COAL) and natural gas (NG) industries as representative variables. Since energy commodities such as oil and natural gas are linked to gold in investment portfolios (Shahzad et al., 2023), we also include the Huaan Gold ETF (XAU). For new energy, following Guo et al. (2025) and the industry classification of the CSI New Energy Index (code 000941), we divide Chinese new energy equities into two broad categories: new energy production and new energy storage and application. Nuclear power (NE), hydropower (HYDRO), photovoltaics (PV) and wind power (WP) are classified as production, while new energy vehicles (NEV) are classified as storage and application. We select equity indices for these industries to represent the corresponding new energy subsectors and use the CSI New Energy Index (NESE) to represent the aggregate new energy market. The sample period extends from April 1, 2019, to April 3, 2026. After excluding non-trading days, 1,702 daily observations are obtained, and logarithmic returns are calculated from these daily closing-price series.
Figure 1 displays the logarithmic return series for all variables. ESG and XAU fluctuate relatively little, whereas the other variables exhibit more pronounced fluctuations, particularly between 2021 and 2023. These fluctuations also show a degree of similarity.
Table 1 presents descriptive statistics for the logarithmic return series. All mean returns are close to zero. NE and COAL have negative mean returns, while the remaining variables have non-negative mean returns at the reported precision, with PV and WP recording the joint highest mean return (0.114). The volatility indicated by the reported return variances is corroborated by the movements in Figure 1; both demonstrate pronounced fluctuations. Apart from NESE, NE and HYDRO, whose return series are right-skewed, all remaining series are left-skewed. Every return series displays a leptokurtic distribution. These characteristics agree with the Jarque–Bera normality test, which indicates that none of the return series is normally distributed. In addition, the Elliott–Rothenberg–Stock unit-root test shows that all return series are stationary.
4. Empirical Results
4.1. Static Risk Spillovers
Following the quantile time–frequency connectedness framework of Chatziantoniou et al. (2022), this study examines static risk spillovers within the system from short- and long-term frequency perspectives under three market conditions. Table 2, Table 3 and Table 4 report static spillover indices at the corresponding quantiles. TCI denotes the system's total spillover index, TO denotes a market's spillovers to other markets, FROM denotes the spillovers it receives from other markets, and NET, calculated as TO minus FROM, denotes its net spillover index. The first value in parentheses represents the short-term spillover from the column market to the row market, and the second represents the corresponding long-term value.
Table 2, Table 3 and Table 4 show that market states substantially affect the intensity of system-wide risk transmission. Under normal market conditions, TCI is 604.22, with a short-term contribution of 554.62 and a long-term contribution of only 49.59. This indicates relatively moderate transmission in stable periods, almost entirely dominated by short-term conditions, with limited transmission over longer horizons. Under extreme downside conditions, however, TCI rises to 868.49, short-term spillovers increase to 703.41, and long-term spillovers rise sharply to 165.07. During extreme market declines, risk contagion therefore intensifies significantly, systemic vulnerability is fully exposed, and the persistence of crisis shocks increases markedly. Under extreme upside conditions, TCI reaches 866.86, broadly comparable to the downside level, with short- and long-term spillovers of 755.93 and 110.74. Extreme market increases thus also generate strong risk transmission. Relative to normal markets, total spillover connectedness rises significantly in both extreme bear and bull markets, with a more pronounced increase in the absolute level and share of long-term spillovers during extreme downturns. Extreme negative shocks therefore produce not only immediate panic-driven transmission but also persistent risk comovement by changing expectations and risk preferences. This finding is highly consistent with Chatziantoniou et al.'s (2021) study of monetary policy transmission through interest rate swaps, which likewise confirms that financial assets exhibit their strongest connectedness at extreme quantiles. During crises, investor panic, information asymmetry and liquidity pressure sharply increase cross-market relationships (Forbes and Rigobon, 2002). The large increase in TCI from normal to extreme markets provides the market-state foundation for the subsequent identification of conditional changes in risk transmission roles.
Directional spillovers show significant differences in the roles played by individual markets, with these roles changing across market states. Under normal conditions, wind power, photovoltaics, natural gas and new energy vehicles are the main risk transmitters, with TO values of 103.32, 102.26, 87.16 and 87.25, respectively, and positive NET values. These clean energy and related markets therefore already have a strong capacity to transmit risk during stable periods. Photovoltaics and wind power are highly affected by policy changes, including subsidy phase-outs and grid integration and renewable-energy absorption requirements. The new energy vehicle supply chain spans upstream lithium and cobalt resources, midstream battery manufacturing and downstream vehicle sales, allowing fluctuations in business conditions to spill outward through intermediate demand and inventory cycles. Natural gas, as a source of balancing power, transmits price fluctuations directly to wholesale electricity markets, subsequently affecting expected returns on new energy generation projects (Fasanya and Mubaiwa, 2025; Lin and Li, 2026). This finding echoes Yang and Ferrer's (2026) quantile connectedness analysis of Chinese green financial markets, which also identifies clean energy subsectors as net transmitters under normal conditions. Similarly, Chatziantoniou et al. (2022), in examining quantile time–frequency price connectedness among green bonds, green equities, sustainable investment and clean energy markets, find that clean energy assets act as net risk transmitters at most quantiles. An explanation is provided by research on contagion from air-pollution control policies: among 12 energy subsectors, photovoltaic generation is most vulnerable to policy disturbances, followed by wind power and fuel cells, whereas coal is least vulnerable (Hsiao et al., 2026). Meanwhile, ESG, nuclear power, hydropower, coal and gold are net receivers. Coal and gold have relatively low TO and FROM values, reflecting their relative independence from the system under normal conditions, weaker transmission capacity and certain safe-haven properties. Nuclear power and hydropower thus have net spillover directions exactly opposite to those of photovoltaics and wind power, despite all being new energy subsectors. This demonstrates the need to distinguish five subsectors: aggregation offsets positive and negative positions, substantially underestimating transmission from photovoltaics and wind power while concealing the risk-reception functions of nuclear power and hydropower.
In extreme downside markets, every market's reported inward spillover index is at least 85, indicating that almost all assets experience substantial risk penetration from within the system. New energy vehicles, photovoltaics, wind power and natural gas retain positive net spillovers, with photovoltaics overtaking wind power as the strongest transmission source. Net inflows to coal and gold expand further, with NET values of −11.99 and −14.53, highlighting their roles as systemic risk buffers during extreme declines. This result agrees with Wu et al. (2024), whose quantile connectedness analysis of green finance and conventional energy finds significantly stronger cross-market spillovers under extreme than normal conditions. Cunado et al. (2024) also identify gold's safe-haven function during energy-market turbulence, finding that it effectively hedges energy assets' downside risk in extreme downside markets. The present study extends the robustness of this safe-haven function from a two-market setting to a multi-sector network containing five new energy subsectors. In the static comparisons, photovoltaics, wind power and natural gas remain net transmitters across market states, constituting stable sources of risk transmission. Coal and gold remain overall net receivers, forming stable pools of risk absorption, while hydropower, nuclear power and ESG display conditional switching as market states change. This joint characterization of cross-condition stability and conditional switching replaces static conceptions of risk transmission roles with a dynamic perspective, providing actionable criteria for tracking role changes and anchoring long-term allocations.
In extreme upside markets, hydropower, photovoltaics, aggregate new energy and natural gas become the main risk transmitters, with TO values of 93.17, 94.65, 91.41 and 91.10, respectively. Most markets' net spillover indices become positive or their net inflows decline, indicating broader and more balanced transmission during extreme increases. Hydropower switches from a net receiver under normal conditions to a net transmitter, while nuclear power moves from net reception towards neutrality. This switching pattern echoes Chatziantoniou et al.'s (2021) finding that net transmission mechanisms become more pronounced at higher quantiles, confirming conditional changes in risk transmission roles across market states. Coal and gold nevertheless remain net receivers, with NET values of −12.32 and −14.23, demonstrating their particularly prominent safe-haven properties in both extreme downside and extreme upside markets. Ha et al. (2022) find that gold hedges risk during uncertain periods, supporting its safe-haven role. He (2026) provides further support, identifying spillovers from carbon markets to clean energy and natural gas over both short and long horizons, and showing that climate policy implementation and related market events amplify energy-market contagion through carbon markets. From time- and frequency-domain perspectives, Bi et al. (2026) examine the effects of climate policy uncertainty on volatility spillovers between clean energy and metals. They find that wind energy is a net transmitter and solar energy dominates long-term connectedness. The static estimates indicate that photovoltaics and wind power consistently act as net transmitters across market states and constitute stable transmission sources, while coal and gold remain overall net receivers and stable risk-absorption pools. Hydropower, nuclear power and ESG, in contrast, exhibit conditional switching, with their roles changing dynamically across market states.
From the frequency perspective, short-term risk spillovers dominate under all market conditions. The short-term aggregate spillover component is much larger than the long-term component, indicating high-frequency, immediate transmission within the system and extremely rapid and strong responses to short-term shocks. This agrees with the central conclusion of Baruník and Křehlík (2018), who introduce spectral decomposition into the spillover index and show that financial-system connectedness is mainly driven by short-term frequencies. Jin et al. (2024) further investigate extreme spillovers in international energy markets through multilayer networks and likewise confirm the dominance of short-term transmission. Changes in long-term spillovers provide greater differentiation. Their shares are relatively small under normal conditions but increase significantly in both absolute and relative terms during extreme downturns. For example, long-term TCI rises from 49.59 to 165.07, showing that extreme negative shocks generate not only immediate panic-driven transmission but also persistent risk comovement through changes in expectations and risk preferences. This occurs because short-horizon traders focus mainly on high-frequency trading, whereas fund managers and large institutional investors tend to use low-frequency strategies, and long-term spillovers are more sensitive to crises than short- and medium-term spillovers (Jin et al., 2024). Examination of sectoral NET values further shows that photovoltaics, wind power, natural gas and gold retain the same net spillover signs over short and long horizons, displaying cross-frequency stability. Coal's long-term NET becomes positive in the extreme downside market, opposite to its negative short-term value, suggesting that it may switch from risk reception to transmission over a longer horizon during extreme declines. Investors should therefore reassess coal's changing role dynamically during prolonged extreme risk. Such frequency-dependent role differences have received limited systematic analysis. For instance, Li et al. (2023) find energy efficiency to be a net transmitter under normal, extreme, short- and long-term settings, whereas the present study identifies cross-frequency role differentiation in a wider range of subsectors.
This study further employs complex network analysis to investigate risk contagion paths within the system across frequency bands and market conditions. Based on the QVAR model's generalized forecast-error variance decomposition, individual markets are represented as nodes, with red indicating net reception and blue indicating net transmission. Cross-market volatility spillovers form the edges of the risk contagion network. Figure 2 presents the networks across frequency bands and market states. The first, second and third groups show spillovers at quantiles 0.05, 0.50 and 0.95, respectively.
Table 2, Table 3 and Table 4 and Figure 2 show that the network analysis corroborates the directional spillover results. The coal node is red across different frequency bands and most market states, with relatively thick connections. Its outward spillover edges to gold, aggregate new energy and photovoltaics are significantly stronger than those of other nodes, indicating that coal is the centre of the entire energy-risk network. China's coal-dominated energy structure transmits coal-price changes throughout the market through a five-stage chain. Highly unpredictable policy signals involving coal-price guidance, safety inspections and import quotas also make coal the node with the greatest information-carrying capacity (Sun et al., 2024; Wang et al., 2024). This agrees with Gao et al. (2025), whose frequency-domain analysis of fossil energy, new energy and environmental governance markets also identifies conventional energy, particularly coal, as a central transmission market. Within the broader asset network, coal and gold have thick bidirectional connections over both short and long horizons, indicating extremely strong direct spillovers. A possible explanation is that both have safe-haven attributes, prompting simultaneous capital allocation and risk comovement when uncertainty increases. Between conventional and new energy, spillovers from coal to photovoltaics and aggregate new energy are strong during extreme declines, indicating that conventional energy price shocks transmit most intensely to new energy generation during crises. This may reflect coal's pricing advantage as a foundational energy source, transmitted through electricity costs. Natural gas also has strong overall spillovers with photovoltaics, indicating substantial contagion between them. This may arise from the close operational complementarity between gas-fired balancing generation and solar power (Chen et al., 2024). By contrast, natural gas has a relatively weak relationship with the lithium-battery energy market, reflecting limited substitution between gas-fired electricity and power storage.
Within new energy, spillovers between photovoltaics and the aggregate new energy market are pronounced, and short-term connections are particularly thick under normal conditions. Photovoltaics therefore occupies a dominant hub position in internal new energy risk transmission. The photovoltaic supply chain is one of China's most globally competitive manufacturing chains, and its capacity and price signals are regarded as indicators of conditions across new energy industries (Deng et al., 2024). This is consistent with Yang et al. (2026), whose quantile connectedness analysis also identifies solar energy as a net transmitter of systemic risk under extreme conditions. Long-term connections between new energy vehicles and photovoltaics strengthen from previously weak levels, indicating that supply-chain relationships between lithium batteries and photovoltaics are gradually deepening over longer horizons. This further confirms the need to disaggregate new energy: without separating photovoltaics from the aggregate sector, its dominant internal spillover role would be concealed by the overall average, leading to serious misinterpretation of transmission paths among subsectors. Across extreme scenarios, hydropower and ESG change node colours, indicating that extreme market states significantly reshape transmission and that sectoral roles switch dynamically across scenarios. Overall, coal occupies the centre of the system, photovoltaics dominates spillovers within new energy, and both market conditions and horizons regulate the direction and intensity of transmission between conventional and new energy. This characterization of network topology supplies structural information omitted by aggregate new energy analysis and provides empirical targets for regulators seeking to identify systemically important nodes.
4.2. Dynamic Risk Spillovers
Figure 3a presents the evolution of total volatility connectedness at the 0.50 quantile, or median, under normal market conditions. Across the full sample, the red short-term volatility-spillover area forms a smooth, continuous band that closely follows the upper black boundary representing total connectedness. Short-term connectedness consistently dominates. By contrast, the green long-term area remains close to the bottom baseline for most of the sample, displaying only extremely small pulse-like increases in early 2020, around 2023 and during several isolated intervals.
Figure 3b depicts spillovers at the 0.05 quantile under extreme downside conditions. The red short-term area again forms the foundation of the black overall path. However, pulse peaks in the green long-term component become noticeably more frequent, and overall connectedness exceeds that at the median. This indicates that the potential accumulation of long-term structural risk is more active in the extreme downside market than under normal conditions.
Figure 3c presents the overall risk profile at the 0.95 quantile under extreme upside conditions. Total connectedness is significantly higher than at the median and remains almost consistently around 90%. The long-term contribution at this quantile is non-negligible, although short-term connectedness remains dominant. The key distinction concerns the differentiated long-term effects of two types of crisis. At the beginning of the COVID-19 outbreak in 2020, the red short-term area increases sharply, and total connectedness falls abruptly before rebounding, forming a flash-like shock pattern. The Russia–Ukraine conflict in 2022, by contrast, keeps the green area persistently elevated and closely intertwined with the red area, producing a high plateau in overall connectedness. The long-term volatility baseline therefore undergoes a marked systematic upward shift after the conflict. This difference arises from the mechanisms of the two crises. COVID-19 creates a demand-side vacuum: lockdowns instantly freeze energy consumption, but supply capacity remains intact and demand can recover rapidly when production resumes. The Russia–Ukraine conflict creates a supply-side rupture: sharply reduced Russian gas and coal exports force Europe to reconstruct supply chains through long-cycle investment, with effects unfolding over years. Long-term spillovers consequently undergo a structural and irreversible increase (Jiang et al., 2021; Kim et al., 2025). This finding echoes Lin et al. (2024), who find that crude oil price uncertainty has particularly pronounced effects on ESG and new energy indices when policy uncertainty is high. The present study extends the differentiated effects of geopolitical conflict from intensity to duration and structural change. Ha et al. (2022), analyzing energy, crude oil, gold and silver, likewise find that COVID-19's effects on system-wide dynamic connectedness peak in the short term before declining. By comparing long-term frequency baselines, this study confirms a fundamental distinction between geopolitical conflict and public health events: public health crises produce abrupt short-term pulses, whereas geopolitical conflicts generate long-term structural upward shifts. This distinction has rarely been tested systematically. The rise in long-term volatility in the first half of 2024 also reflects liquidity shocks arising from supply-side panic associated with escalating Middle Eastern tensions, including Iran's retaliation and the Red Sea crisis. These comparisons show that, at the extreme 0.95 quantile, public health emergencies primarily transmit intense, immediate panic, whereas persistent supply-side structural ruptures caused by geopolitical conflicts force short- and long-horizon capital into synchronized movements, generating sustained high risk connectedness.
Figure 4a shows the evolution of dynamic net directional volatility spillovers for each index at the 0.50 quantile, or median. Black, red and green denote the overall, short-term and long-term components, respectively. Consistent with the drivers of total connectedness, the overall net spillover paths of most indices are overwhelmingly driven by short-term dynamics, while the long-term area generally remains a minor component near the baseline. Several exceptions exist. Around 2026, ESG is a net volatility receiver over the long term but a net transmitter over the short term. Conversely, during approximately 2021–2025, NESE is a short-term net receiver but becomes a long-term net transmitter, primarily reflecting structural developments after the Russia–Ukraine conflict in 2022. ESG's role changes across horizons because greenwashing concerns and investment-style rotation generate outward return-volatility spillovers in the short term (Ampountolas and Saglam, 2026), whereas its low-volatility and high-quality characteristics make it a long-term haven for capital, absorbing risk from the system (Duong, 2026). This frequency-dependent differentiation agrees with Jiang et al.'s (2026) study of Chinese green bonds and commodities, which also shows that green bonds can switch from net reception to net transmission over longer horizons. Overall, no index maintains an exclusively transmitting or receiving role throughout the sample. Volatility transmission roles change over time, confirming conditional role switching in the time dimension. Wu and Qin (2024) find that overall bad-volatility spillovers between new energy and ESG equities significantly exceed good-volatility spillovers after COVID-19. Compared with their findings, the broader range of assets and denser network in this study reveal more frequent and complex conditional switching. Nevertheless, NEV, NG, PV and WP remain net volatility receivers for the overall network for much of the period.
Figure 4b presents net directional volatility spillovers at the 0.05 quantile under extreme downside conditions. The overall net spillover curves frequently move above and below zero, and their underlying paths are not driven solely by the short-term area. Instead, long-term net spillover pulses become pronounced and frequent, at certain points even becoming the main force determining the direction of the black overall curve for particular assets. At the beginning of the Russia–Ukraine conflict in 2022, PV and WP first jump in the short term, followed by increases in the long-term component. This clearly traces the transmission of geopolitical shocks from short-term sentiment to long-term structure. COAL also exhibits a marked distinction: its long-term spillovers tend to lie above zero, while short-term spillovers tend to lie below it. This temporal pattern of short-term leadership and long-term adjustment agrees with Deng and Xu (2024), whose time–frequency analysis of international oil prices and China's new energy supply chain finds that short-term spillovers respond before long-term spillovers.
Figure 4c shows dynamic net directional volatility spillovers at the 0.95 quantile under extreme upside conditions. The responses are exceptionally large and transmission roles reverse sharply. Overall net spillover curves switch frequently across extreme ranges, and their movements are almost entirely driven by short-term dynamics. There is no continuously stable net transmission or reception of volatility. This role switching under extreme conditions agrees with Yousfi and Bouzgarrou's (2024) findings for oil, clean energy and green equity markets. They likewise show that the net transmission directions of individual assets are highly unstable in extreme markets, presenting serious challenges for the design of tail-risk hedging strategies.
Figure 5a shows the evolution of net pairwise volatility spillovers at the 0.50 quantile, or median. Black, red and green represent the overall, short-term and long-term components, respectively. Under normal conditions, overall net spillovers for most asset pairs are firmly dominated by the underlying short-term path, while long-term fluctuations generally appear only as small local disturbances. Pairs within new energy are generally net receivers, whereas pairs involving XAU generally remain near zero, demonstrating gold's insulation within the normal-state micro-network as an independent safe-haven asset. This contrasts with Elsayed et al. (2026), who are the first to test ESG futures' hedging potential against highly polluting energy futures and find that they function effectively as safe havens during downside energy-market risk. Gold's insulation under normal conditions is more pronounced in this study, indicating substantial differences in the functions of safe-haven assets across market states.
Figure 5b displays net pairwise volatility spillovers at the 0.05 quantile under extreme downside conditions. Although the overall curves appear close to zero, the underlying short-term volatility is much greater than in normal markets. Short-term pulses become unusually frequent and intense, particularly around the Russia–Ukraine conflict in 2022 and around 2024. Without the support of a long-term directional force, however, even strong short-term pulses quickly return to zero and fail to generate a structural displacement. This highlights that the conflict's long-term upward-shift characteristic is reflected not in the intensity of individual pulses but in the overall increase in the long-term baseline.
Figure 5c presents net pairwise volatility spillovers at the 0.95 quantile under extreme upside conditions. The overall curves fluctuate sharply, and their paths are almost entirely driven by deep expansions of the long-term component. Unlike Figure 5a and Figure 5b, the short-term component in Figure 5c becomes secondary within the overall volatility structure, while synchronized trading and hedging by long-horizon institutions dominate. Pairs involving XAU exhibit exceptionally sharp long-term declines or extreme increases that cross zero. This indicates that gold's pairwise relationships with other risky assets are completely reshaped under extreme upside market conditions and that its safe-haven function undergoes dramatic, repeated role reversals during periods of extreme market stress. Initially, safe-haven demand increases gold holdings, making gold a net receiver. As the crisis deepens into the margin-call stage, investors are forced to sell gold for liquidity, reversing its role to net transmission. After panic peaks, gold is repurchased and its role reverses again. These repeated reversals reflect asymmetric fluctuations in gold's safe-haven function (Faraj et al., 2025). This finding logically corroborates Zheng et al. (2026), who find substantial variation in gold's safe-haven effectiveness during systemic crises. Gold's defensive function is not consistently effective under every extreme condition; its performance is significantly asymmetric across crisis stages. This cautions investors using gold to hedge portfolios in extreme markets. Gold's cross-condition stability primarily concerns its net-reception direction in the static comparisons, whereas its reception intensity varies substantially across crisis stages.
4.3. Comparison Before and After the Russia–Ukraine Conflict
Using the outbreak of the Russia–Ukraine conflict in 2022 as a clear dividing point, this study compares the stage-specific differences in energy-market volatility spillover mechanisms before and after the conflict across the quantiles shown in Figure 6. Although studies such as Jiménez et al. (2026) find that extreme events significantly alter the correlation structure between ESG and new energy assets and sharply increase tail dependence, most directly use events such as the Russia–Ukraine conflict as sample breakpoints or control variables, without ex post verification of the form of their effects.
Before the Russia–Ukraine conflict, all three panels exhibit stability within their respective market states. Under normal conditions, overall connectedness, shown in black, gradually falls from a high level and forms a trough. During this stage, the long-term green band at the bottom is extremely thin, and volatility is primarily driven by routine short-term trading forces, shown in orange in Figure 6, without a significant structural upward deviation. Under extreme downside and upside conditions, overall connectedness exceeds 80%, but the long-term volatility path remains relatively smooth and most short-term disturbances are smoothed by market liquidity. Overall, pre-conflict risk connectedness in energy markets is primarily driven by conventional supply–demand conditions and macroeconomic cycles. Long-term structural factors remain dormant, and spillovers exhibit clear cyclicality and predictability. This stable pre-conflict structure is consistent with Caldara et al.'s (2020) description of geopolitical risk as latent during non-conflict periods.
After the Russia–Ukraine conflict begins, spillover dynamics change qualitatively at all three quantiles, and the role of the long-term dimension is significantly amplified. This is most evident in the normal-market panel, where the black overall-connectedness line exhibits a clear step-like increase in early 2022 and continues fluctuating around this higher central level over subsequent years, without readily returning to the pre-conflict trough. The long-term green band also becomes substantially thicker. This indicates that the far-reaching effects of the geopolitical crisis, including energy decoupling and supply-chain restructuring, have become fully embedded in an irreversible long-term structural volatility baseline under normal conditions, forcing the central level of overall connectedness upward. This step-like increase contrasts sharply with the spike-shaped pulse during COVID-19 in 2020, confirming the proposed distinction between two crisis transmission patterns: COVID-19 generates short-term pulses, whereas the Russia–Ukraine conflict generates a long-term structural upward shift. The post-conflict increase in long-term spillovers is therefore a system-wide phenomenon across quantiles and frequency bands, rather than a local change confined to extreme markets. It provides important empirical support for long-term energy strategies and asset allocation across cycles.
In the extreme downside market, the conflict-induced change takes the form of dense pulse-like eruptions in the long-term area. During 2023–2025, peaks in the green bottom band frequently extend into the orange short-term area and even become the dominant source of volatility at particular times. This indicates that, in the downside market, subsequent developments triggered by the conflict, such as the EU gas-price cap, continually transmit to the system through long-horizon capital as frequent supply-disruption or policy risks. In the extreme upside market, the long-term band also becomes broader after the conflict, showing that long-horizon uncertainty is deeply intertwined with short-term sentiment under extreme market conditions and becomes a mainstay of persistently high connectedness. Compared with dormant long-term factors before the conflict, their post-conflict activation is system-wide. It is not confined to a particular quantile but represents a systemic transition spanning normal, extreme downside and extreme upside markets. This complements Chishti et al.'s (2026) findings on the dynamic effects of global common volatility on precious metals and energy. They find a clear post-conflict structural break in geopolitical effects at long-term frequencies, while this study extends that result from individual markets to a multi-market network and quantifies the systematic upward shift in long-term spillovers.
By systematically comparing long-term spillovers before and after the conflict, this section confirms that the Russia–Ukraine conflict is a system-wide pivotal event that reshapes long-term risk connectedness in the energy–financial network examined here. Its effects follow a long-term structural upward-shift pattern rather than the short-term pulse pattern assumed or implied in conventional research. Distinguishing these crisis patterns provides a theoretical basis for regulators to develop differentiated policy-response toolkits.
4.4. Robustness Checks
This study takes comprehensive steps to ensure the reliability and robustness of its conclusions. Specifically, rolling windows of 100 and 300 days are used to examine risk spillover indices in depth alongside the 200-day baseline. The corresponding results are reported in Table 5 and Table 6.
For the sample of ESG, conventional energy, new energy subsectors and gold, the alternative rolling windows yield total spillover indices of 622.47 and 598.77, broadly consistent with the baseline. More importantly, the directions of the overall net spillovers remain unchanged, and photovoltaics and wind power remain the leading net transmitters. Photovoltaics and wind power retain the highest positive NET values in both the 100- and 300-day windows, while nuclear power, coal and gold remain net receivers. This shows that the functional division between new energy transmission sources and absorption pools identified through sectoral disaggregation, together with the buffering roles of coal and gold, is robust to changes in the rolling-window parameter.
The dominance of short-term spillovers, the significant strengthening of long-term spillovers in extreme markets, and the step-like increase in long-term spillovers around the Russia–Ukraine conflict are also consistent across all three window settings. The study's core conclusions concerning mechanism identification and the distinction between crisis transmission patterns are therefore robust.
5. Conclusions and Policy Implications
This study addresses gaps in the literature by examining volatility connectedness and risk spillovers among ESG, conventional energy, new energy subsectors and gold. It also investigates the mechanisms through which extreme events affect these relationships and spillovers. The analysis helps clarify the dynamic transmission of risk among conventional and new energy subsectors and the precious metal gold. The empirical investigation uses quantile time–frequency connectedness and complex network analysis. Connectedness among the variables is moderate at the median quantile and increases significantly at the lower and upper quantiles. Across all three market states, short-term volatility transmission is stronger, while long-term transmission is weaker. Under normal conditions, wind power, photovoltaics, natural gas and new energy vehicles are net risk transmitters, whereas ESG, aggregate new energy, nuclear power, hydropower, coal and gold are net receivers. Under extreme downside conditions, wind power, photovoltaics, aggregate new energy, natural gas and new energy vehicles are net transmitters, while ESG, nuclear power, hydropower, coal and gold are net receivers. Under extreme upside conditions, ESG, nuclear power, hydropower, wind power, photovoltaics, aggregate new energy, natural gas and new energy vehicles are net transmitters, whereas coal and gold are net receivers. The transmission roles of conventional and new energy subsectors also change between short- and long-term frequency bands, although the static estimates show that photovoltaics, wind power, natural gas and gold retain their roles across quantiles and frequency bands. During extreme events, public health emergencies such as COVID-19 increase short-term volatility, whereas geopolitical conflicts, including the Russia–Ukraine conflict and escalating Middle Eastern tensions, increase long-term volatility. Before the Russia–Ukraine conflict, the connectedness structure is relatively simple, with short-term factors dominating routine fluctuations for most of the period. After the conflict, normal, extreme downside and extreme upside markets all exhibit a combination of an elevated long-term structural baseline and short-term high-frequency pulses. This transition indicates that the Russia–Ukraine conflict is a system-wide pivotal event reshaping long-term risk connectedness in the energy–financial network examined here.
Based on the systematic investigation of risk spillovers among ESG, conventional energy, new energy subsectors and gold, and the differentiated transmission roles across market states and frequency bands, this study proposes the following practical investment implications and policy recommendations. First, the transmission positions and net-transmitting properties of conventional and new energy subsectors at different quantiles provide a basis for differentiated sectoral allocation. At the median, wind power, photovoltaics, natural gas and new energy vehicles are net risk transmitters, indicating strong outward risk transmission, greater price-discovery efficiency and sufficient market activity during stable periods. Investors can moderately overweight these sectors under normal conditions to capture their return-leading advantages. In extreme downside markets, wind power, photovoltaics, aggregate new energy, natural gas and new energy vehicles transmit risk, whereas ESG, nuclear power, hydropower, coal and gold receive it. Investors should increase allocations to coal and gold during extreme declines, using their net-reception properties to hedge portfolio downside risk. They should also recognize that photovoltaics and wind power continue to spread risk during crises and control exposures to these sectors. In extreme upside markets, ESG, nuclear power, hydropower, wind power, photovoltaics, aggregate new energy, natural gas and new energy vehicles are all net transmitters, with only coal and gold remaining net receivers. Thus, most energy assets other than coal and gold transmit risk during extreme rallies. During market overheating, investors should allocate only to coal and gold to dampen extreme portfolio volatility and moderately reduce holdings of other energy assets. Second, frequency-domain results show that transmission roles can change between short and long horizons, but the static estimates show that the roles of photovoltaics, wind power, natural gas and gold remain unchanged across quantiles and frequency bands. This robustness provides investors with a stable allocation reference across cycles and market states. Photovoltaics and wind power can serve as core holdings in long-term strategic energy allocations, with systematic strategies designed around their stable risk characteristics. Natural gas also has a stable role and strong spillovers with photovoltaics because gas-fired and solar generation operate complementarily. Investors can combine natural gas and photovoltaics, using their complementarity in the electricity system to diversify risk. Third, transmission positions and network structures differ significantly across crisis stages. Policymakers should abandon a uniform crisis-response approach and develop mechanisms differentiated by crisis type. During public health crises, short-term shocks are severe but long-term effects are limited. Emergency measures should emphasize rapid short-term liquidity provision, temporary changes to trading arrangements, such as circuit breakers and short-selling restrictions, and targeted liquidity support for net-transmitting new energy sectors to prevent temporary panic from becoming systemic risk. During geopolitical crises, long-term volatility is elevated and structural effects persist. Emergency measures should prioritize energy supply security, including strategic petroleum reserve releases and expanded domestic production, diversified supply chains, and market-stabilization support for net receivers such as coal and gold, ensuring that they can function effectively as buffers during crises. Despite the progress made in identifying time–frequency spillover characteristics and differences under extreme market conditions, limitations and uncertainties remain concerning sample coverage and volatility calculation.
Author Contributions
Conceptualization, methodology and writing—original draft, Rong Li; data collection, data curation and formal analysis, Yuhan Li. All authors have read and agreed to the submitted version of the manuscript.
Funding
This research received no external funding.
Institutional Review Board Statement
Not applicable. This study uses financial market data and does not involve human participants or animals.
Informed Consent Statement
Not applicable.
Data Availability Statement
The data supporting the findings of this study are available from the corresponding author upon reasonable request.
Conflicts of Interest
The authors declare no conflicts of interest.
Declaration of Generative AI Use
OpenAI generative AI tools were used to assist with English translation, language editing and manuscript formatting. The authors are responsible for the content of the manuscript.
References
- Dao, T.; Awijen, H.; Ahmed, R.; Ameur, H. B. Understanding energy security in geopolitical contexts: Insights from decomposing energy diversification indexes. Energy Econ. 2025, 152, 108947. [Google Scholar] [CrossRef]
- Cheng, I. H.; Xiong, W. Financialization of Commodity Markets. Annu. Rev. Financ. Econ. 2014, 6(1), 419–441. [Google Scholar] [CrossRef]
- Akusta, A.; Gün, M. (Eds.) Financial Frontiers in Energy Markets; Springer Nature Switzerland, 2026. [Google Scholar] [CrossRef]
- Dinh, M. T. H. Interplay of Alternative Energy Sub-Sectors, Oil Prices, and Oil Volatility: Exploring Simultaneous Relationships. Int. J. Financ. Stud. 2025, 13(1), 23. [Google Scholar] [CrossRef]
- Jin, J.; Han, L.; Wu, L.; Zeng, H. Exploring the sources of systemic risk and trading strategies in energy and stock markets. Energy Econ. 2024, 139, 107873. [Google Scholar] [CrossRef]
- Li, S.; Li, H. Dual safe havens during turbulence? Wavelet-based TVP-VAR evidence from oil–gold dynamics under uncertainty shocks. Energy Strategy Rev. 2026, 64, 102139. [Google Scholar] [CrossRef]
- Ahad, M.; Imran, Z. A.; Shahzad, K. Safe haven between European ESG and energy sector under Russian-Ukraine war: Role of sustainable investments for portfolio diversification. Energy Econ. 2024, 138, 107853. [Google Scholar] [CrossRef]
- Wu, R.; Li, B.; Qin, Z. Spillovers and dependency between green finance and traditional energy markets under different market conditions. Energy Policy 2024, 192, 114263. [Google Scholar] [CrossRef]
- Jiménez, I.; Mora-Valencia, A.; Perote, J. Asymmetric effects on asymmetry: The resilience of ESG indices. Financ. Res. Lett. 2026, 98, 109737. [Google Scholar] [CrossRef]
- Du, R.; Xu, P. Time-Varying Spillover Effects Between Clean and Traditional Energy Under Multiple Uncertainty Risk: Evidence from the U.S. Market. Sustainability 2024, 16(21), 9164. [Google Scholar] [CrossRef]
- Zheng, H.; Wang, S.; Zhang, T.; Chen, S. Dynamic tail risk contagion in multi-asset markets: A DCC-MGH framework with CoEVaR analysis during systemic crises. Financ. Res. Lett. 2026, 90, 109397. [Google Scholar] [CrossRef]
- Cunado, J.; Gabauer, D.; Gupta, R. Realized volatility spillovers between energy and metal markets: a time-varying connectedness approach. Financ. Innov. 2024, 10(1), 12. [Google Scholar] [CrossRef]
- Ando, T.; Greenwood-Nimmo, M.; Shin, Y. Quantile Connectedness: Modeling Tail Behavior in the Topology of Financial Networks. Manag. Sci. 2022, 68(4), 2401–2431. [Google Scholar] [CrossRef]
- Antonakakis, N.; Chatziantoniou, I.; Gabauer, D. Refined Measures of Dynamic Connectedness based on Time-Varying Parameter Vector Autoregressions. J. Risk Financ. Manag. 2020, 13(4), 84. [Google Scholar] [CrossRef]
- Fasanya, I. O.; Mubaiwa, D. T. Dynamics of extreme spillovers between clean energy stocks and fossil fuels: The role of climate policy uncertainty and geopolitical risks. Energy 2025, 335, 138267. [Google Scholar] [CrossRef]
- Baruník, J.; Křehlík, T. Measuring the Frequency Dynamics of Financial Connectedness and Systemic Risk. J. Financ. Econom. 2018, 16(2), 271–296. [Google Scholar] [CrossRef]
- de Boyrie, M. E.; Pavlova, I. Connectedness with commodities in emerging markets: ESG leaders vs. conventional indexes. Res. Int. Bus. Financ. 2024, 71, 102456. [Google Scholar] [CrossRef]
- Elsayed, A. H.; Hoque, M. E.; Khalfaoui, R.; Mahi, M. A. Green guard or fossil fortress? Implications for environmental management. J. Environ. Manag. 2026, 413, 130257. [Google Scholar] [CrossRef]
- Chatziantoniou, I.; Gabauer, D.; Marfatia, H. A. Dynamic connectedness and spillovers across sectors: Evidence from the Indian stock market. Scott. J. Political Econ. 2021, 69(3), 283–300. [Google Scholar] [CrossRef]
- Chatziantoniou, I.; Abakah, E. J. A.; Gabauer, D.; Tiwari, A. K. Quantile time–frequency price connectedness between green bond, green equity, sustainable investments and clean energy markets. J. Clean. Prod. 2022, 361, 132088. [Google Scholar] [CrossRef]
- Diebold, F. X.; Yilmaz, K. Better to give than to receive: Predictive directional measurement of volatility spillovers. Int. J. Forecast. 2012, 28(1), 57–66. [Google Scholar] [CrossRef]
- Diebold, F. X.; Yılmaz, K. On the network topology of variance decompositions: Measuring the connectedness of financial firms. J. Econom. 2014, 182(1), 119–134. [Google Scholar] [CrossRef]
- Gao, W.; He, M.; Zhang, H. Risk connectedness and portfolios between fossil energy, new energy and environmental governance markets. Int. Rev. Financ. Anal. 2025, 104, 104234. [Google Scholar] [CrossRef]
- Kasraoui, N.; Hemrit, W. Where Is the World Heading? Quantile Time-Frequency Connectedness Among Oil, Conventional and ESG Stock Returns. J. Risk Financ. Manag. 2026, 19(2), 151. [Google Scholar] [CrossRef]
- Zhang, K.; Xu, X.; Zhao, M. Risk Spillover Effect from Oil to Chinese New-Energy-Related Stock Markets: An R-vine Copula-Based CoVaR Approach. Mathematics 2025, 13(12), 1934. [Google Scholar] [CrossRef]
- Yang, H.; Ferrer, R. Shock transmission among green financial instruments and major financial assets and commodities in China: A quantile connectedness analysis. Glob. Financ. J. 2026, 71, 101282. [Google Scholar] [CrossRef]
- Lin, L.; Jiang, Y.; Zhou, Z. Asymmetric spillover and network connectedness of policy uncertainty, fossil fuel energy, and global ESG investment. Appl. Energy 2024, 368, 123432. [Google Scholar] [CrossRef]
- Ha, L. T.; Thanh, T. T.; Linh, V. M. An exploration of sources of volatility in the energy market: An application of a TVP-VAR extended joint connected approach. Sustain. Energy Technol. Assess. 2022, 53, 102448. [Google Scholar] [CrossRef]
- Wu, R.; Qin, Z. Asymmetric volatility spillovers among new energy, ESG, green bond and carbon markets. Energy 2024, 292, 130504. [Google Scholar] [CrossRef]
- Umar, Z.; Jareño, F.; Escribano, A. Agricultural commodity markets and oil prices: An analysis of the dynamic return and volatility connectedness. Resour. Policy 2021, 73, 102147. [Google Scholar] [CrossRef]
- Abricha, A.; Ben Amar, A.; Bellalah, M. Commodity futures markets under stress and stress-free periods: Further insights from a quantile connectedness approach. Q. Rev. Econ. Financ. 2024, 93, 229–246. [Google Scholar] [CrossRef]
- Yang, H.; Ferrer, R. Shock transmission among green financial instruments and major financial assets and commodities in China: A quantile connectedness analysis. Glob. Financ. J. 2026, 71, 101282. [Google Scholar] [CrossRef]
- Mirza, N.; Horobet, A.; Tudor, C. D.; Radu, I. A. The green paradox: Does sustainability drive financial performance in energy? Rev. Manag. Sci. 2026, 20(10), 3779–3809. [Google Scholar] [CrossRef]
- Jiang, C.; Li, W.; Wang, Y.; Ding, R. A complex network analysis of risk spillover and linkage effects between green bonds and commodities under the characteristics of the Chinese market. Int. Rev. Econ. Amp Financ. 2026, 105, 104891. [Google Scholar] [CrossRef]
- Li, H.; Li, Y.; Zhang, H. The spillover effects among the traditional energy markets, metal markets and sub-sector clean energy markets. Energy 2023, 275, 127384. [Google Scholar] [CrossRef]
- Zhang, Qingjun; Wang, Fengyue. Risk spillovers from new energy mineral imports to green industries: Evidence from stock market industry indices. Ind. Technol. Econ. In Chinese.. 2025, 44(11), 64–74. [Google Scholar]
- Hui, Diaoyan; Wang, Zhi; He, Zhenhua. Spillover effects among carbon markets, green finance and energy markets from a time–frequency perspective. Soft Sci. In Chinese.. 2025, 39(6), 135–144. [Google Scholar] [CrossRef]
- Shahzad, U.; Mohammed, K. S.; Tiwari, S.; Nakonieczny, J.; Nesterowicz, R. Connectedness between geopolitical risk, financial instability indices and precious metals markets: Novel findings from Russia Ukraine conflict perspective. Resour. Policy 2023, 80, 103190. [Google Scholar] [CrossRef]
- Guo, Na; Wang, Peiyao; Liu, Jingshan; et al. Extreme risk spillovers between China’s carbon market and new energy stock market: An analysis from the perspectives of tail dependence and asymmetry. J. Hainan Univ. (Humanities & Social Sciences) In Chinese.. 2025, 43(5), 78–88. [Google Scholar] [CrossRef]
- Su, X.; Zhao, Y. What has the strongest connectedness with clean energy? Technology, substitutes, or raw materials. Energy Econ. 2023, 128, 107169. [Google Scholar] [CrossRef]
- Al-Khazaleh, S.; Badwan, N.; Almashaqbeh, M. RETRACTED: Financial contagion in financial markets: a systematic literature review and directions for future research. J. Money Laund. Control 2025, 28(3), 572–591. [Google Scholar] [CrossRef]
- Forbes, K. J.; Rigobon, R. No Contagion, Only Interdependence: Measuring Stock Market Comovements. J. Financ. 2002, 57(5), 2223–2261. [Google Scholar] [CrossRef]
- Hsiao, C. Y. L.; Liu, B.; Chiu, Y. B.; Chui, C. M. Contagion risks of air pollution control policies on the China energy stock returns. Int. Rev. Econ. Amp Financ. 2026, 109, 105358. [Google Scholar] [CrossRef]
- Kang, S. H.; Tiwari, A. K.; Albulescu, C. T.; Yoon, S. M. Exploring the time-frequency connectedness and network among crude oil and agriculture commodities V1. Energy Econ. 2019, 84, 104543. [Google Scholar] [CrossRef]
- Joint Research Group of the Center for Energy Security and National Development; National School of Development; Peking University; and the Department of Energy Economics; School of Economics; Renmin University of China; Wang Min. A study of subsidy shortfalls and extensive curtailment in China’s wind and photovoltaic power generation. Int. Econ. Rev. In Chinese.. 2018, (4), 67–85+6. [Google Scholar]
- Lin, B.; Li, J. Spot price fluctuations of battery-grade lithium carbonate and supply chain disruptions: The survival game of new energy enterprises. Renew. Energy 2026, 262, 125372. [Google Scholar] [CrossRef]
- Sun, Y.; Wen, G.; Dai, H.; Feng, Y.; Azaele, S.; Lin, W.; Zhou, F. Quantifying the Resilience of Coal Energy Supply in China Toward Carbon Neutrality. Research 2024, 7, 0398. [Google Scholar] [CrossRef]
- Wang, J.; Dai, P. F.; Chen, X. H.; Nguyen, D. K. Examining the linkage between economic policy uncertainty, coal price, and carbon pricing in China: Evidence from pilot carbon markets. J. Environ. Manag. 2024, 352, 120003. [Google Scholar] [CrossRef]
- Jiang, P.; Fan, Y. V.; Klemeš, J. J. Impacts of COVID-19 on energy demand and consumption: Challenges, lessons and emerging opportunities. Appl. Energy 2021, 285, 116441. [Google Scholar] [CrossRef]
- Kim, Y. J.; Min, K.; Cho, S. H. Energy transitions post–Russia–Ukraine war: challenges and policy implications in Germany and Italy. Electr. J. 2025, 38(4), 107518. [Google Scholar] [CrossRef]
- Ampountolas, A.; Saglam, Y. The market impact of greenwashing crackdowns: Evidence from ESG exchange-traded funds. J. Behav. Exp. Financ. 2026, 51, 101211. [Google Scholar] [CrossRef]
- Duong, A. T. T. ESG as a conditional risk buffer: Idiosyncratic volatility and tail losses across market regimes. Financ. Res. Lett. 2026, 92, 109588. [Google Scholar] [CrossRef]
- Faraj, H.; McMillan, D.; Al-Sabah, M. The diminishing lustre: Gold's market volatility and the fading safe haven effect. Glob. Financ. J. 2025, 67, 101145. [Google Scholar] [CrossRef]
- Bi, Z.; Wu, Q.; Luo, L. Climate policy uncertainty and the co-movement between clean energy and metal markets: A spillover perspective. Resour. Policy 2026, 112, 105818. [Google Scholar] [CrossRef]
- He, T. Asymmetric tail risk spillovers between carbon emission allowance and energy markets: evidence from China. Appl. Econ. 2026, 58(9), 1746–1763. [Google Scholar] [CrossRef]
- Jin, X.; Liu, Y.; Yu, J.; Chen, N. Extreme risk spillovers in international energy markets: New insights from multilayer networks in the frequency domain. Energy Econ. 2024, 139, 107908. [Google Scholar] [CrossRef]
- Chishti, M. Z.; Gubareva, M.; Özkan, O.; Xaisongkham, S.; Vo, X. V. Dynamic effects of the global common volatility on precious metals and energy markets: Fourier quantile-on-quantile and Fourier quantile regressions. J. Commod. Mark. 2026, 41, 100544. [Google Scholar] [CrossRef]
- Chen, J.; Chen, Y.; Zhou, W. Relation exploration between clean and fossil energy markets when experiencing climate change uncertainties: substitutes or complements? Humanit. Soc. Sci. Commun. 2024, 11(1), 691. [Google Scholar] [CrossRef]
- Suissi, N.; Mroua, M. The Effect of the Russia–Ukraine Invasion on Macroeconomic Variables, Investor Sentiment and Commodities: A Frequency Connectedness among G7. Ann. Financ. Econ. 2026, 21(02), 2650006. [Google Scholar] [CrossRef]
- Ando, T.; Greenwood-Nimmo, M.; Shin, Y. Quantile Connectedness: Modeling Tail Behavior in the Topology of Financial Networks. Manag. Sci. 2022, 68(4), 2401–2431. [Google Scholar] [CrossRef]
- Yousfi, M.; Bouzgarrou, H. Quantile network connectedness between oil, clean energy markets, and green equity with portfolio implications. Environ. Econ. Policy Stud. 2024, 27(4), 583–614. [Google Scholar] [CrossRef]
- Deng, X.; Xu, F. Connectedness between international oil and China's new energy industry chain: A time-frequency analysis based on TVP-VAR model. Energy Econ. 2024, 140, 107954. [Google Scholar] [CrossRef]
- Caldara, D.; Iacoviello, M.; Molligo, P.; Prestipino, A.; Raffo, A. The economic effects of trade policy uncertainty. J. Monet. Econ. 2020, 109, 38–59. [Google Scholar] [CrossRef]
Figure 1.
Logarithmic return series.
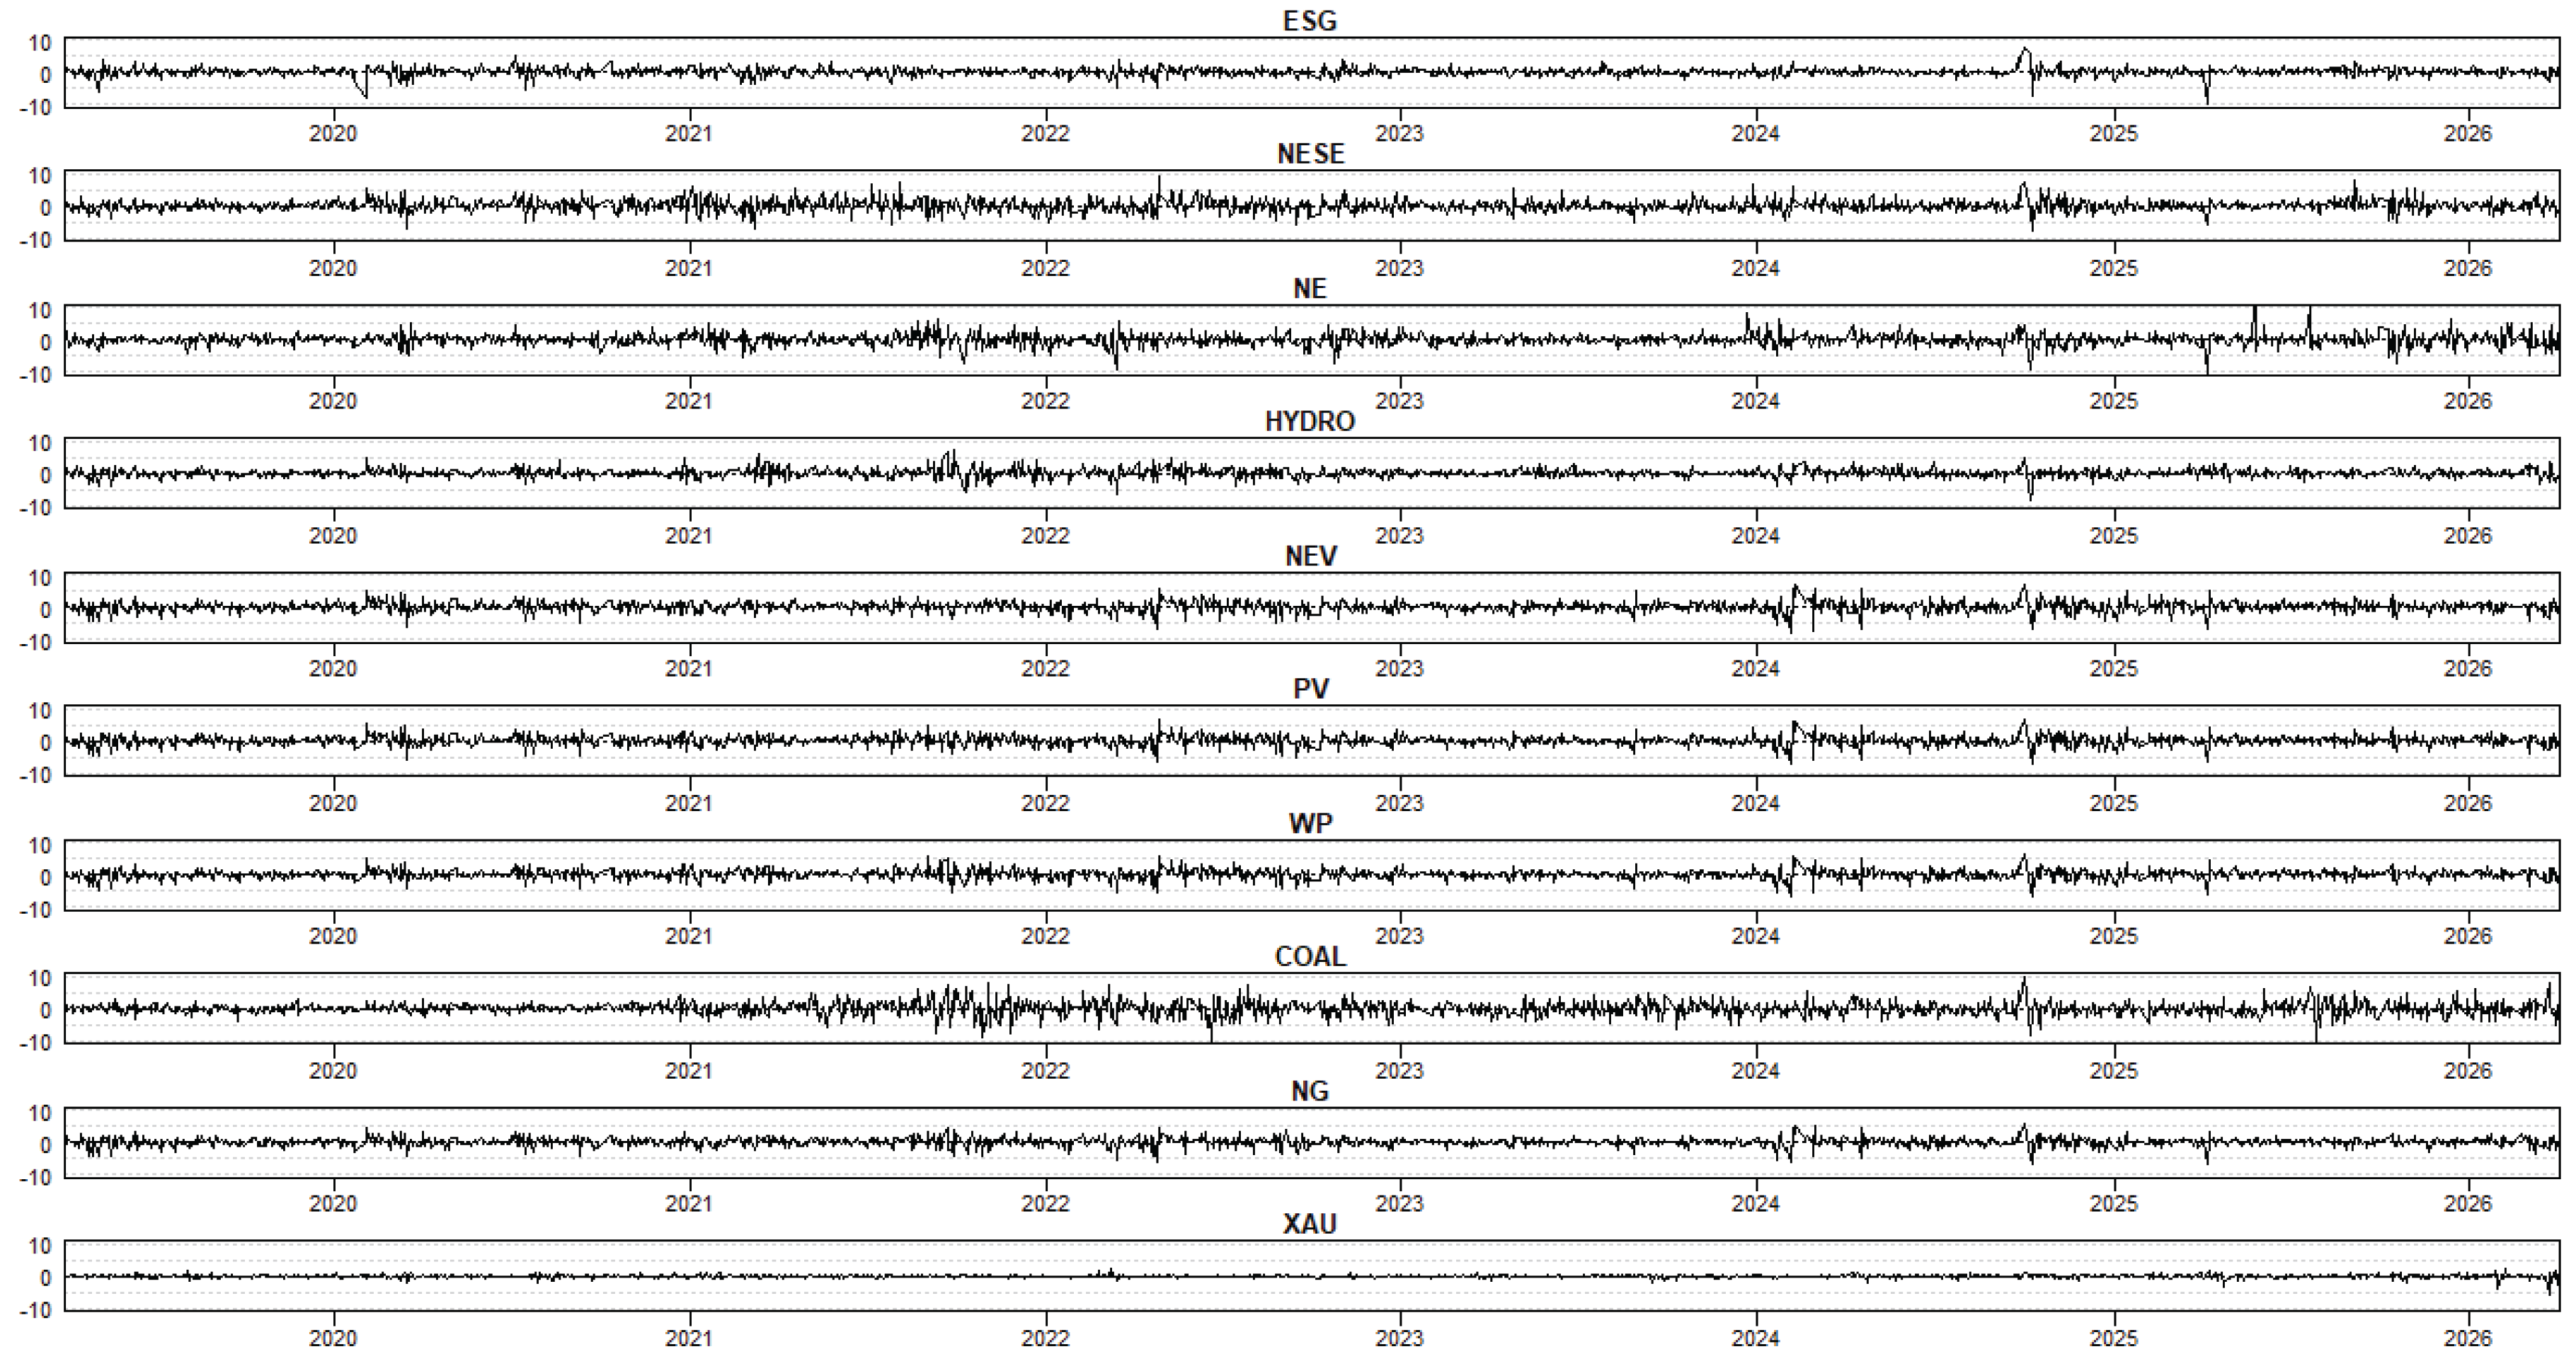
Figure 2.
Risk spillover networks across frequency bands and market conditions.
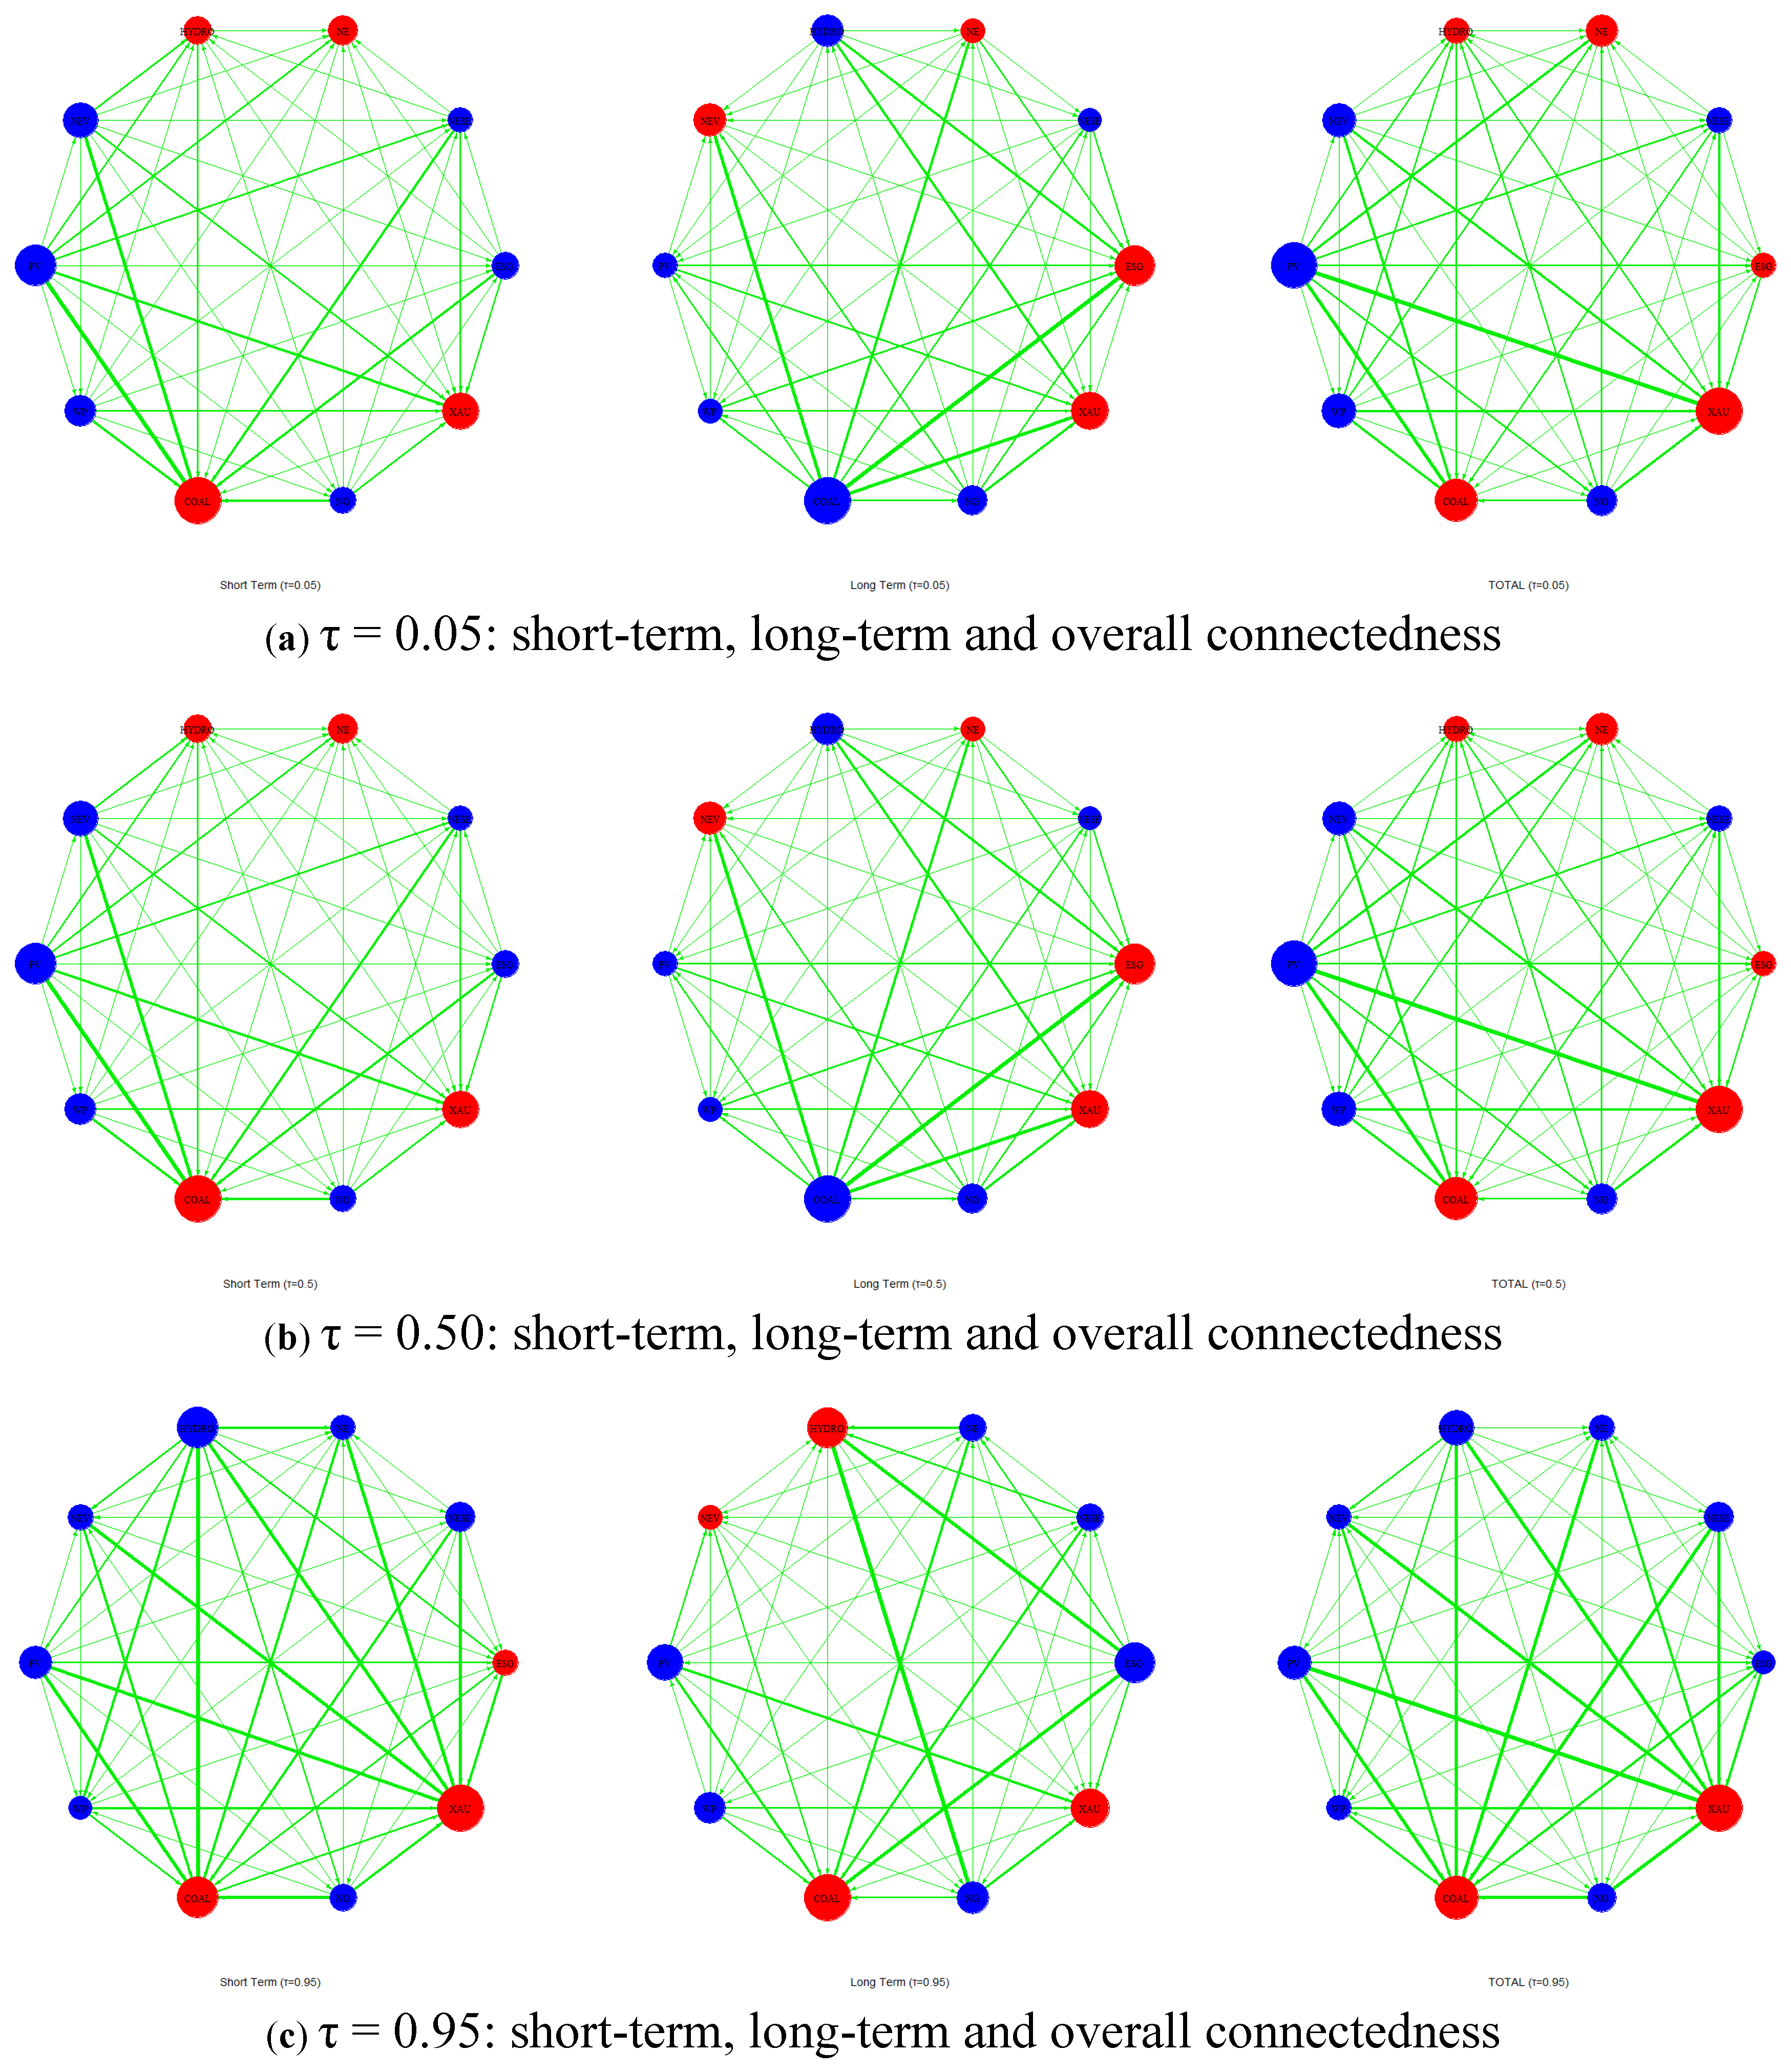
Figure 3.
(a) Total spillovers across frequency bands and market conditions (τ = 0.50). (b) Total spillovers across frequency bands and market conditions (τ = 0.05). (c) Total spillovers across frequency bands and market conditions (τ = 0.95).
Figure 3.
(a) Total spillovers across frequency bands and market conditions (τ = 0.50). (b) Total spillovers across frequency bands and market conditions (τ = 0.05). (c) Total spillovers across frequency bands and market conditions (τ = 0.95).
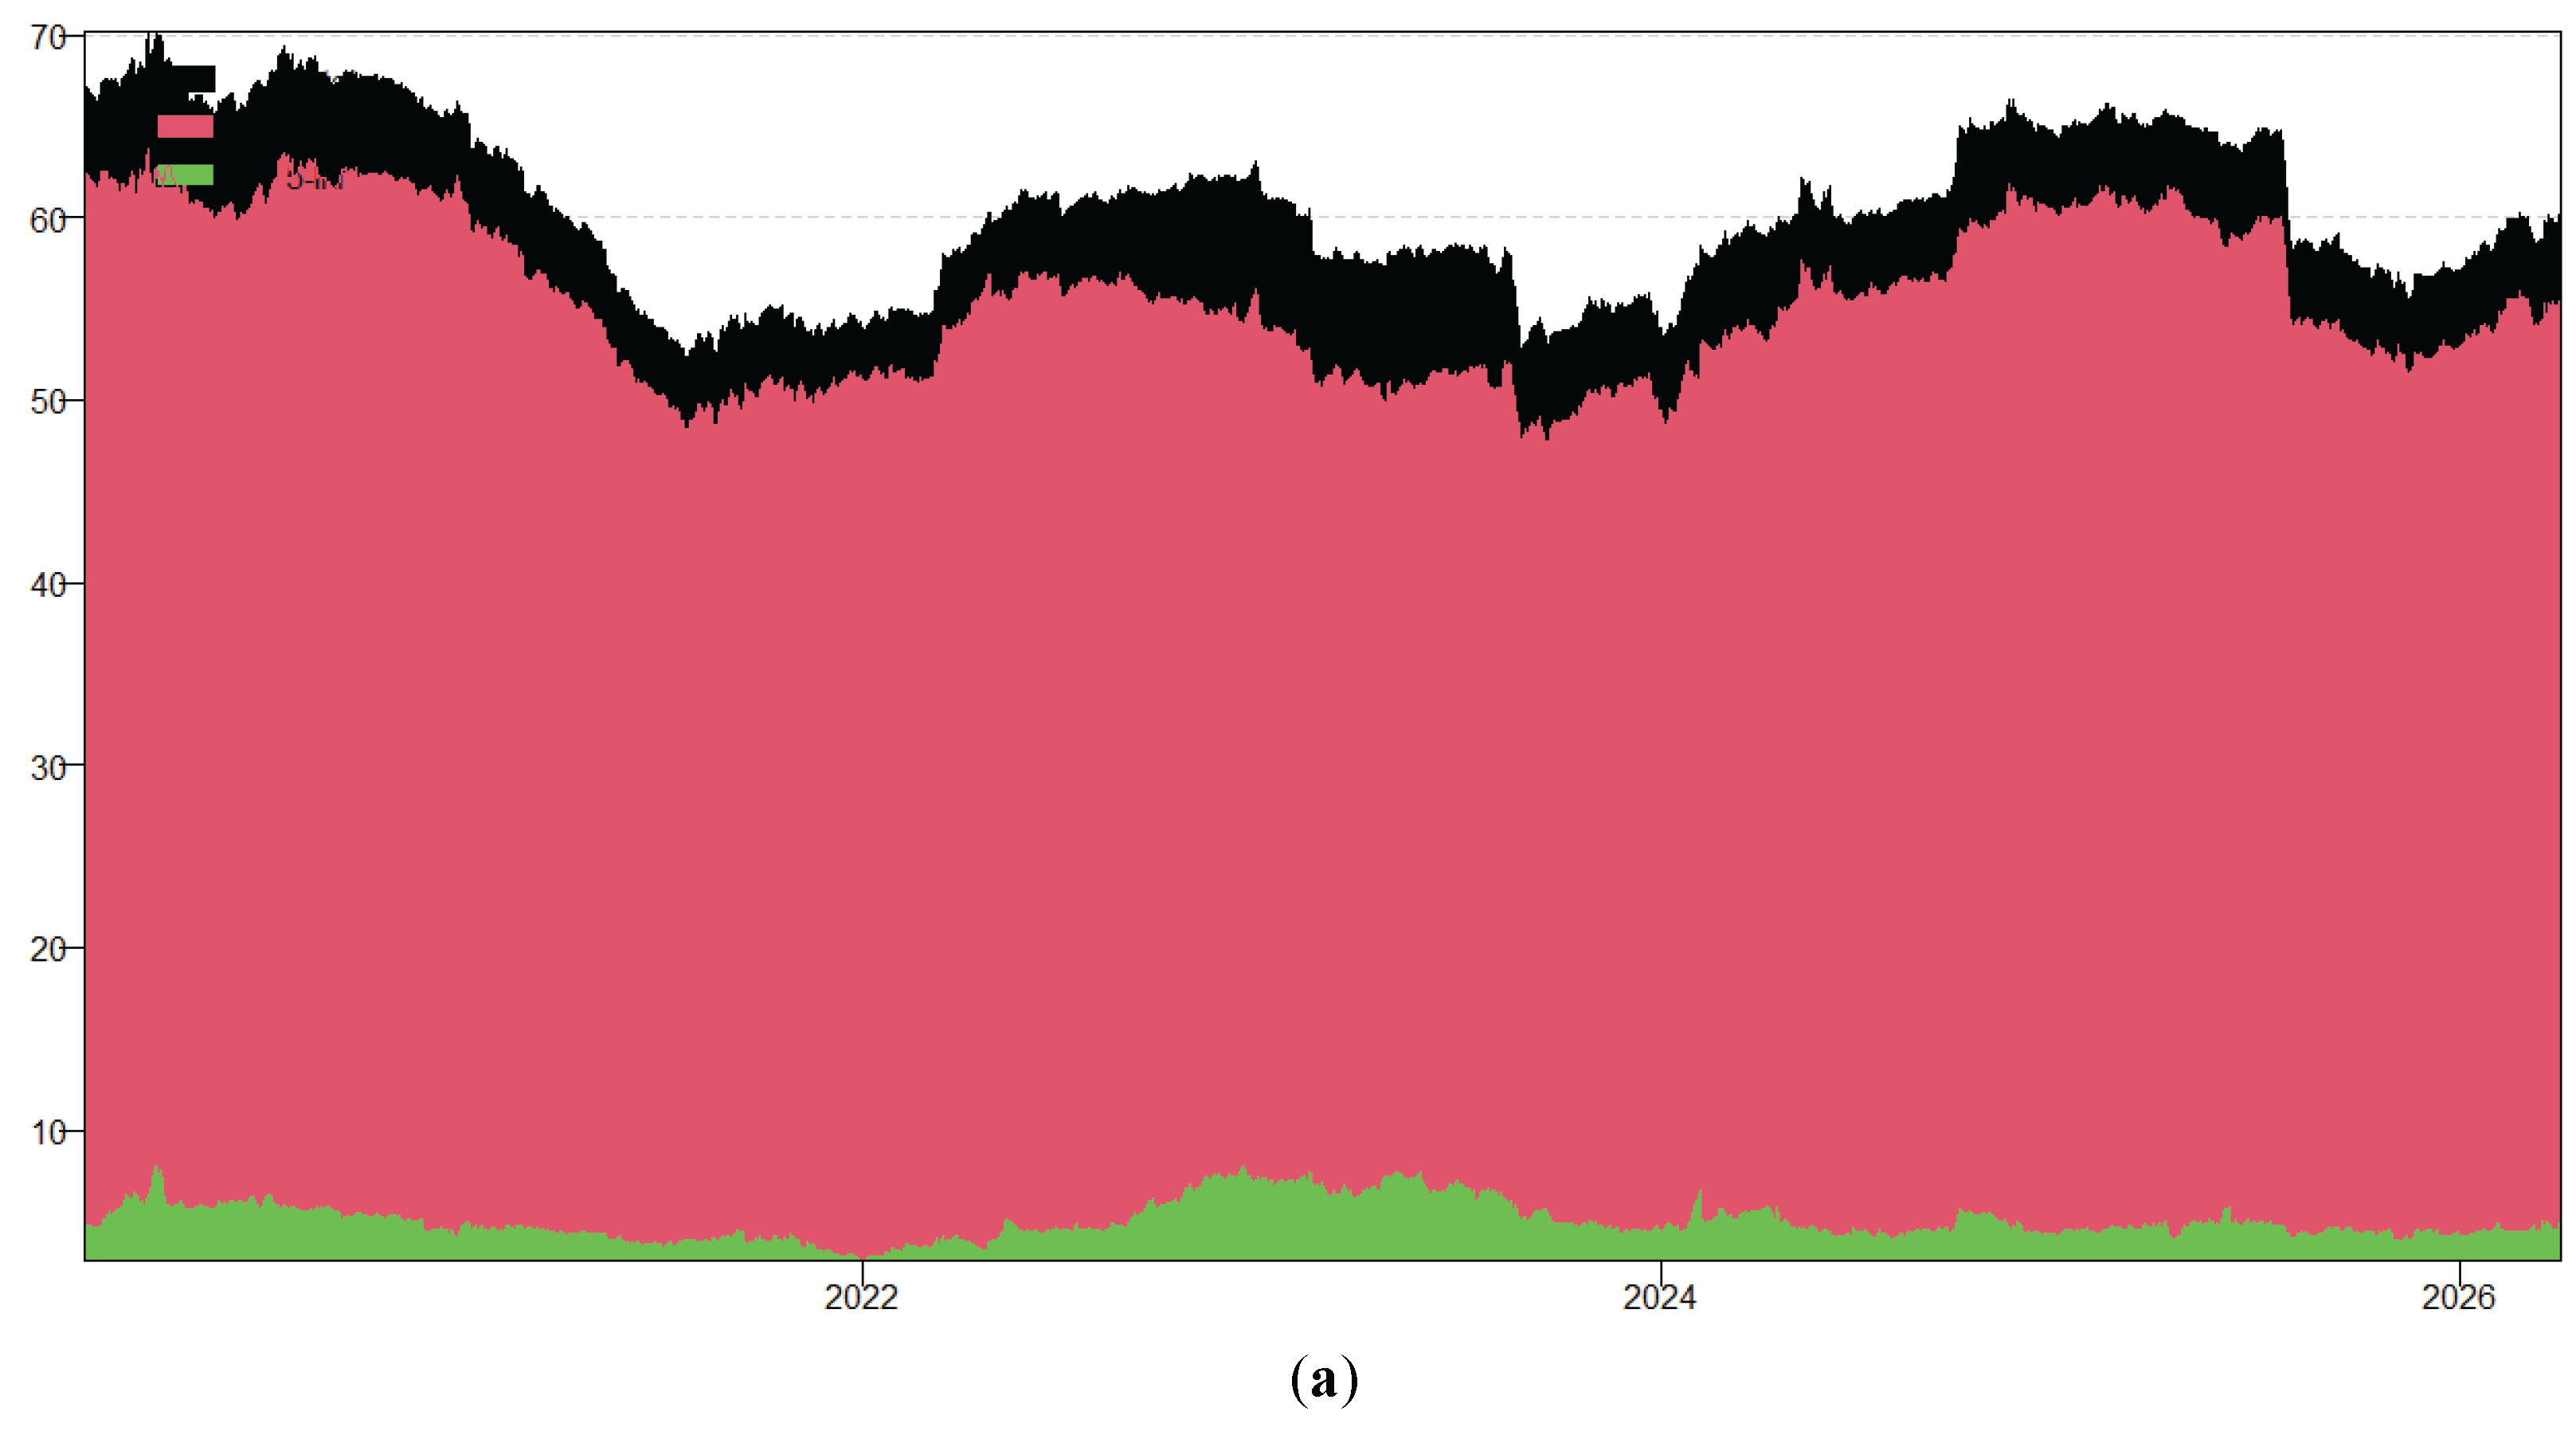
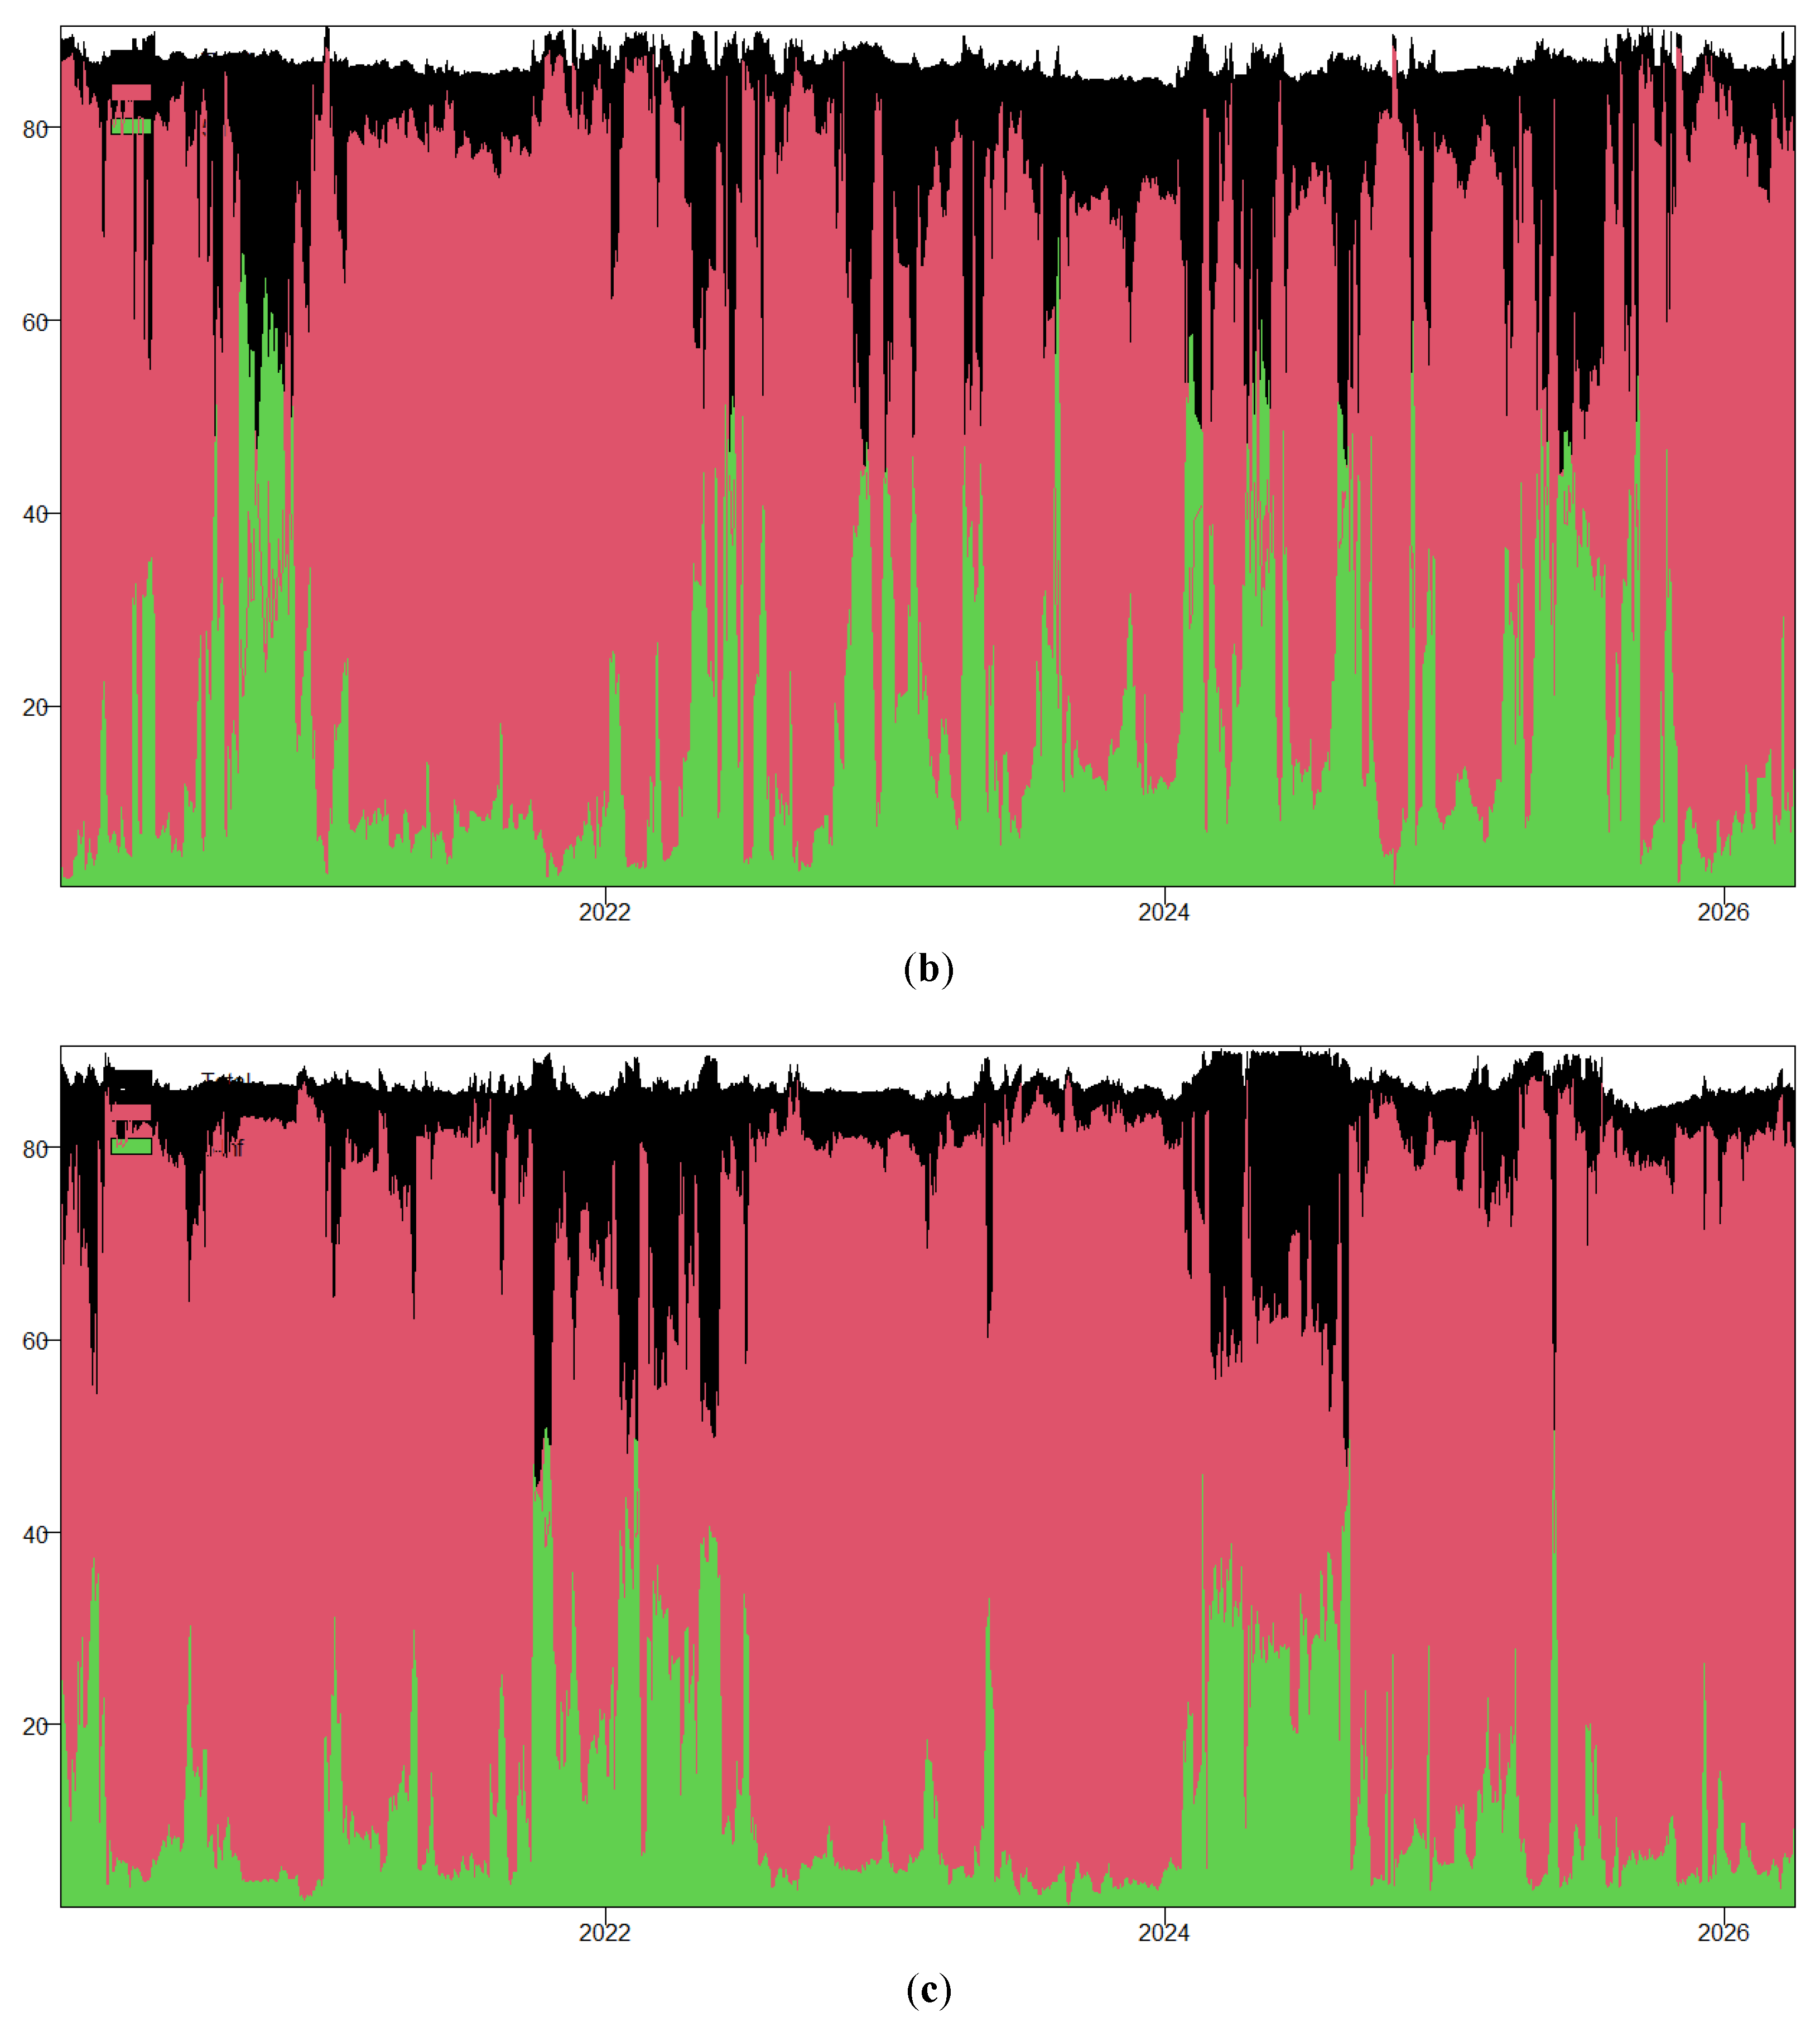
Figure 4.
(a) Net spillovers across frequency bands and market conditions (τ = 0.50). (b) Net spillovers across frequency bands and market conditions (τ = 0.05). (c) Net spillovers across frequency bands and market conditions (τ = 0.95).
Figure 4.
(a) Net spillovers across frequency bands and market conditions (τ = 0.50). (b) Net spillovers across frequency bands and market conditions (τ = 0.05). (c) Net spillovers across frequency bands and market conditions (τ = 0.95).
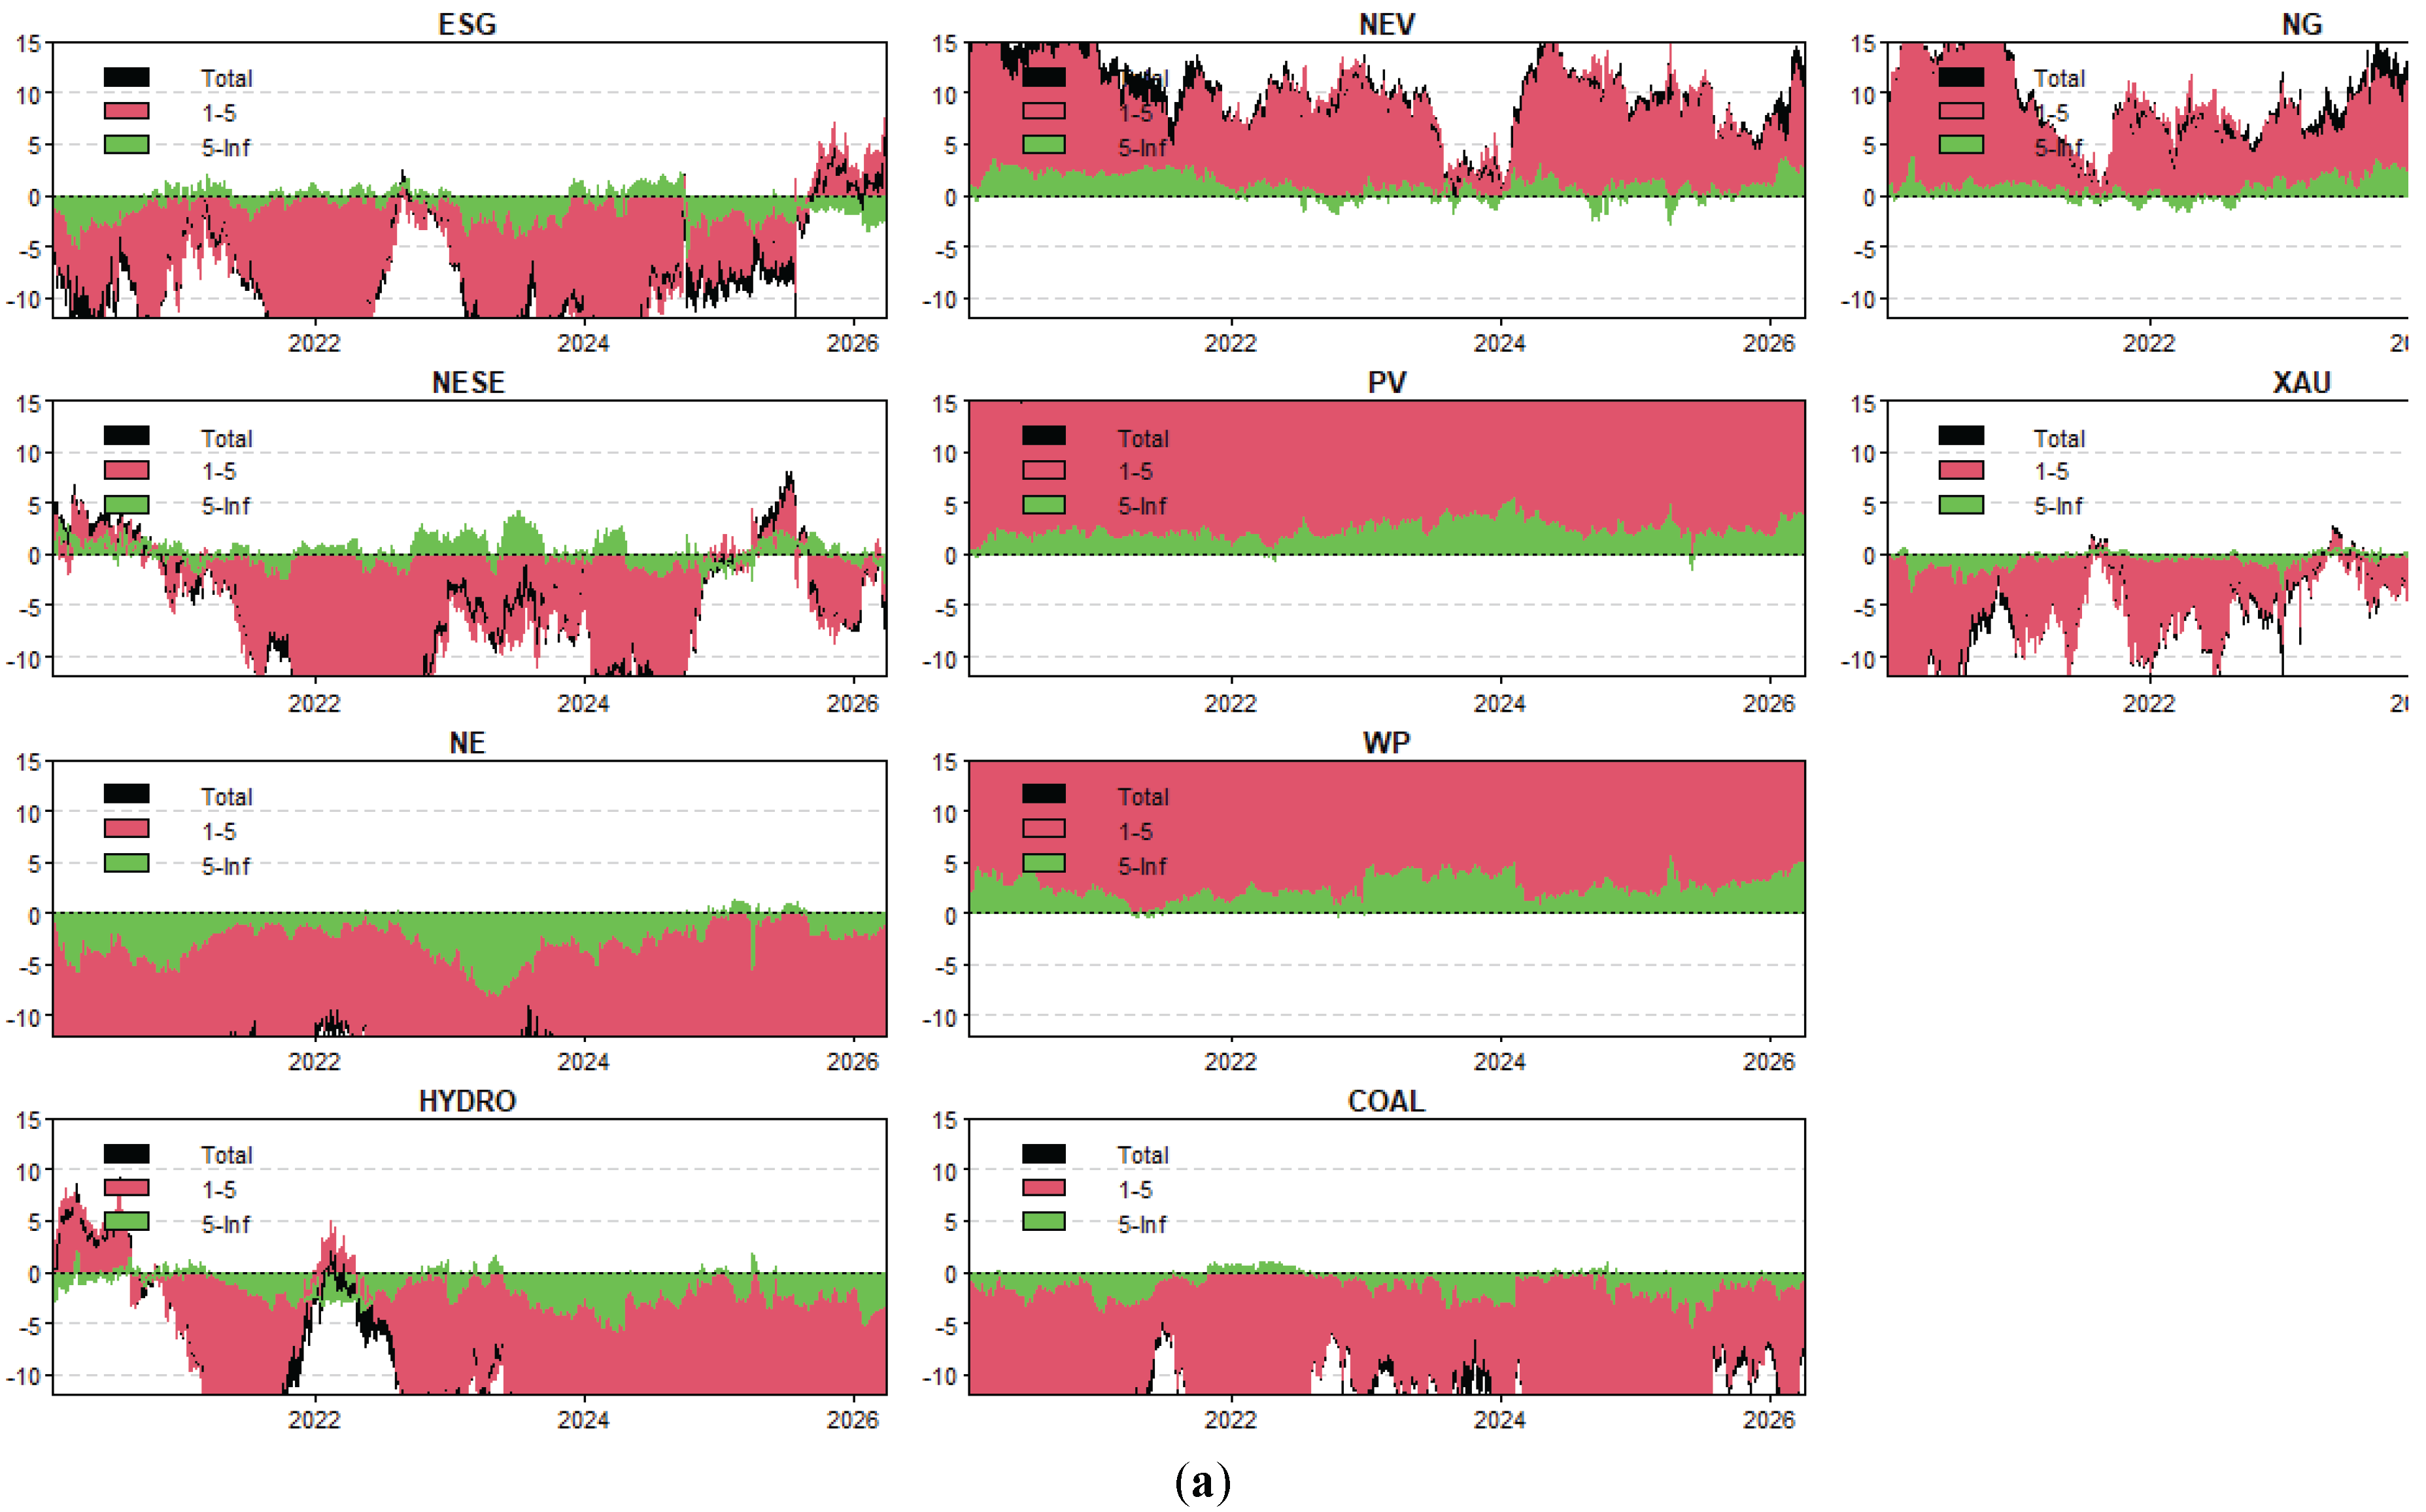
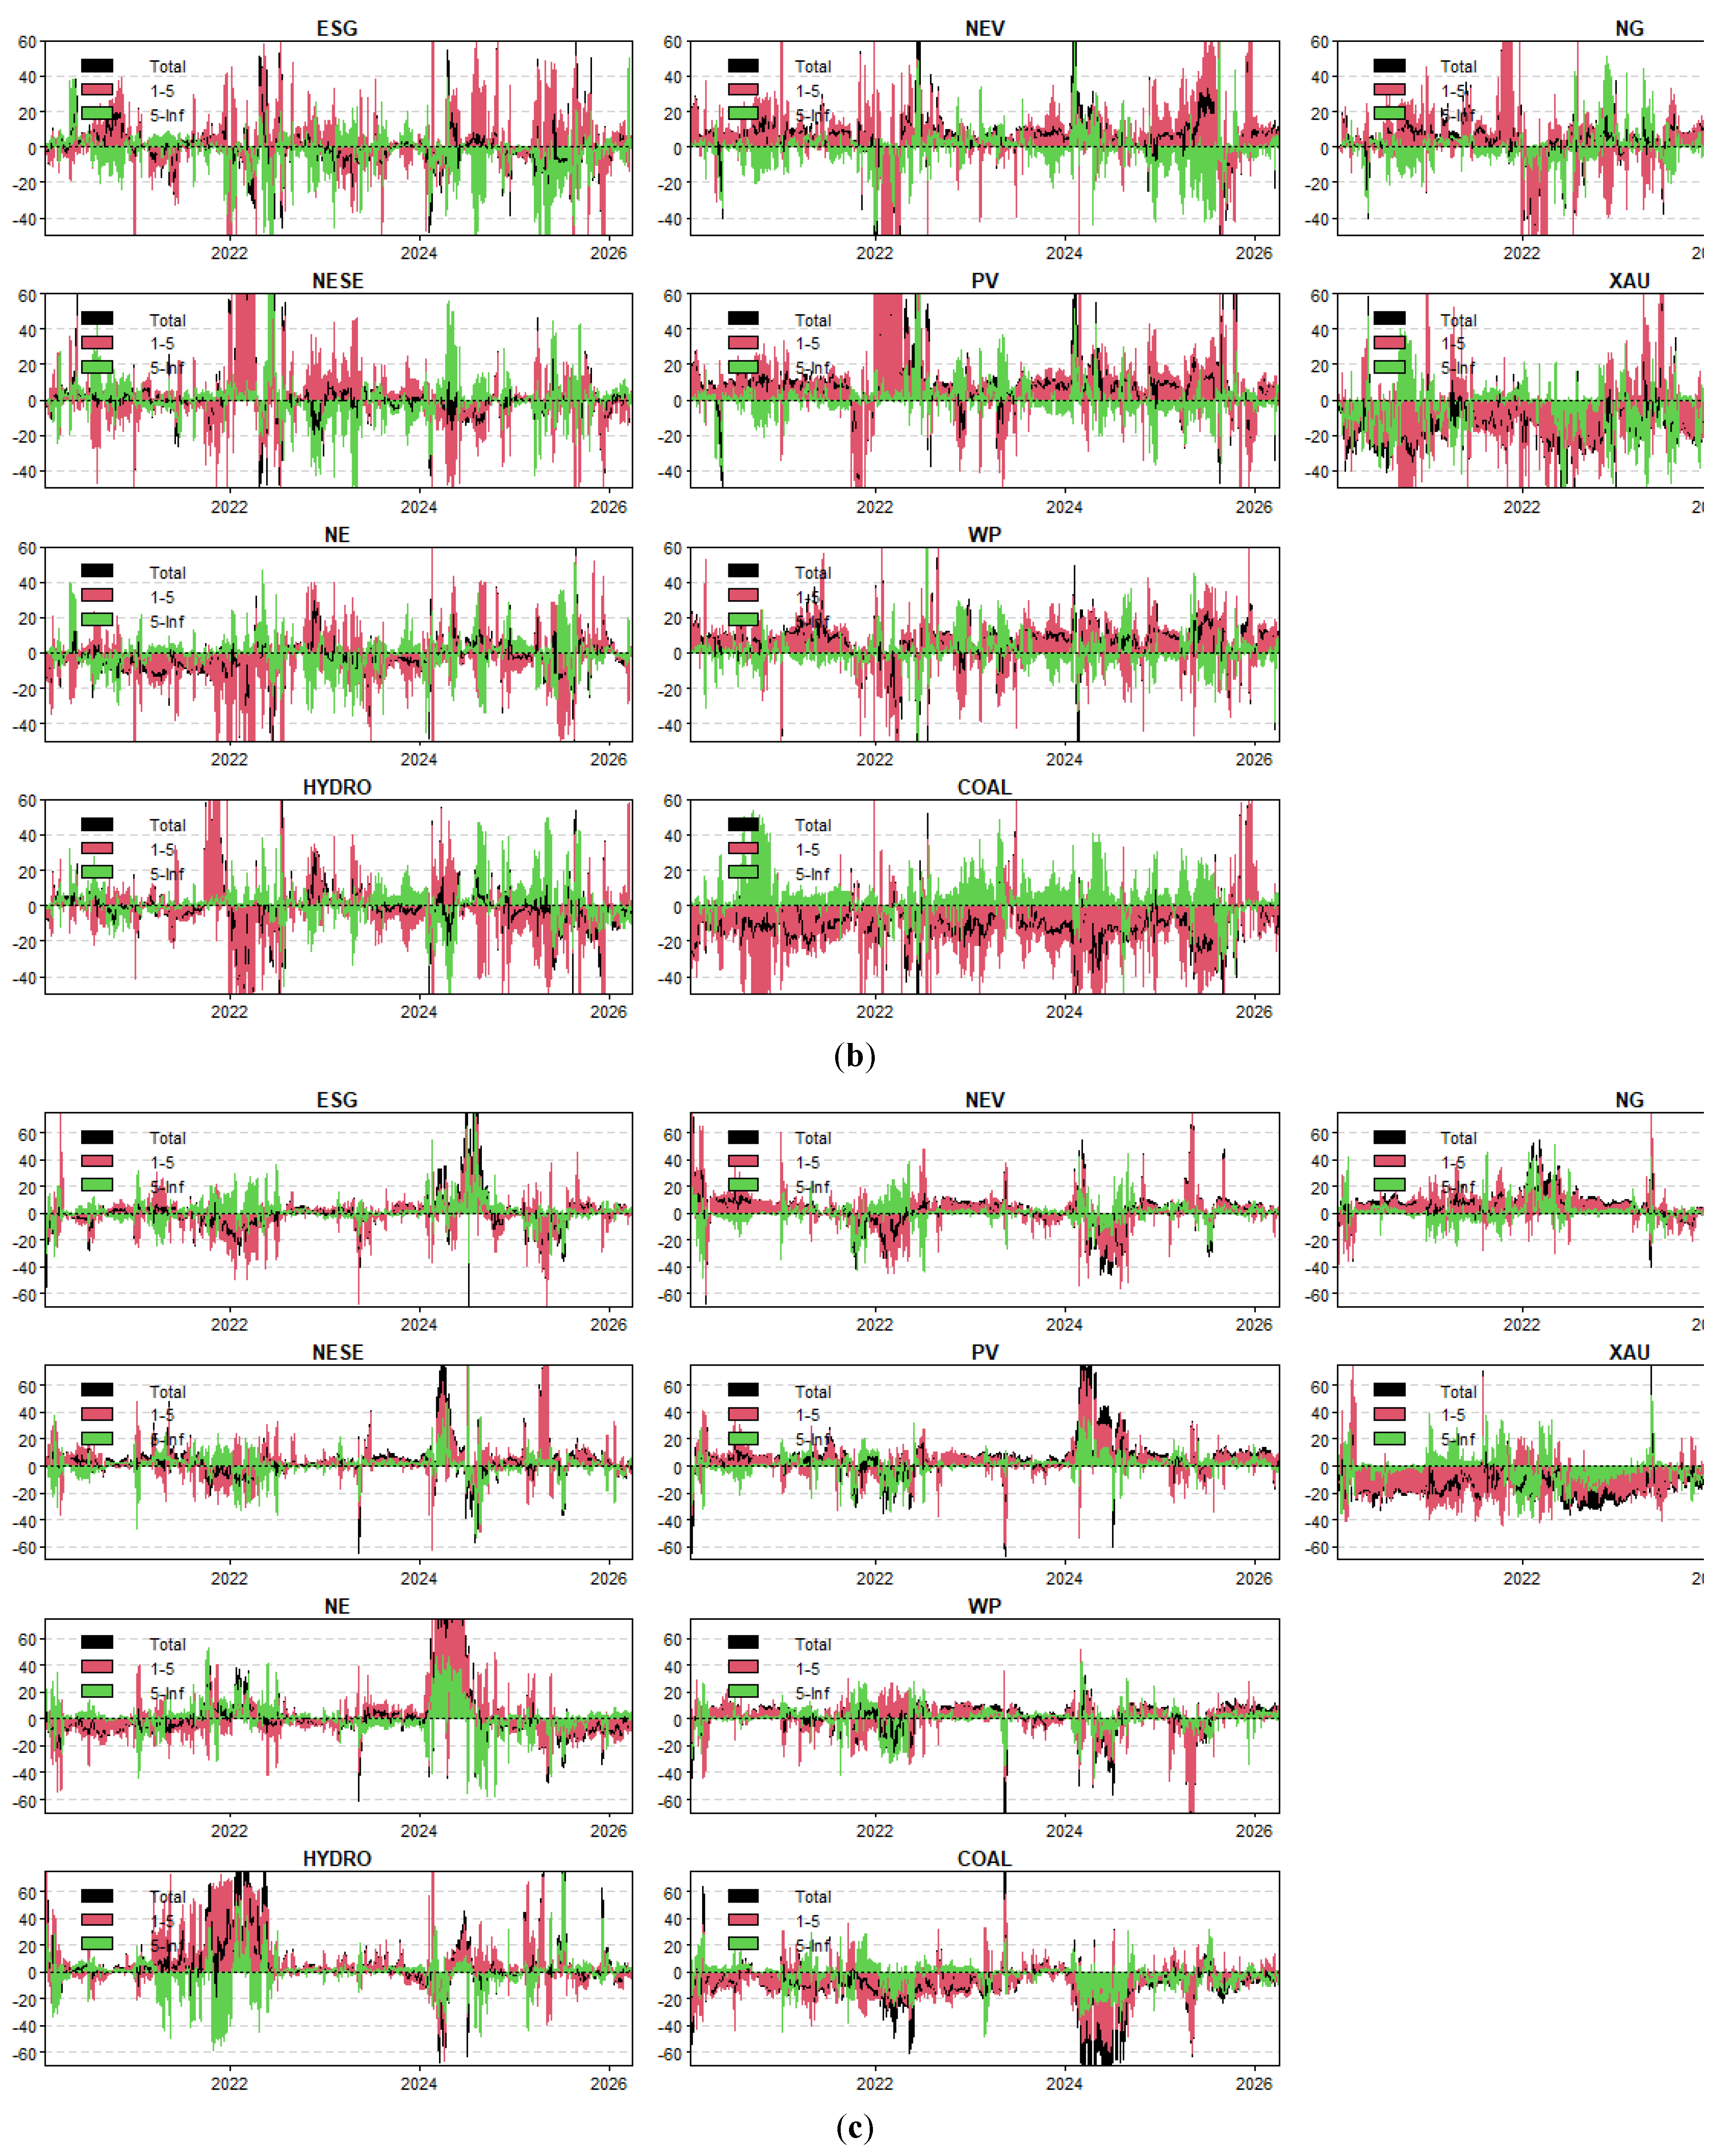
Figure 5.
(a) Net pairwise spillovers across frequency bands and market conditions (τ = 0.50). (b) Net pairwise spillovers across frequency bands and market conditions (τ = 0.05). (c) Net pairwise spillovers across frequency bands and market conditions (τ = 0.95).
Figure 5.
(a) Net pairwise spillovers across frequency bands and market conditions (τ = 0.50). (b) Net pairwise spillovers across frequency bands and market conditions (τ = 0.05). (c) Net pairwise spillovers across frequency bands and market conditions (τ = 0.95).
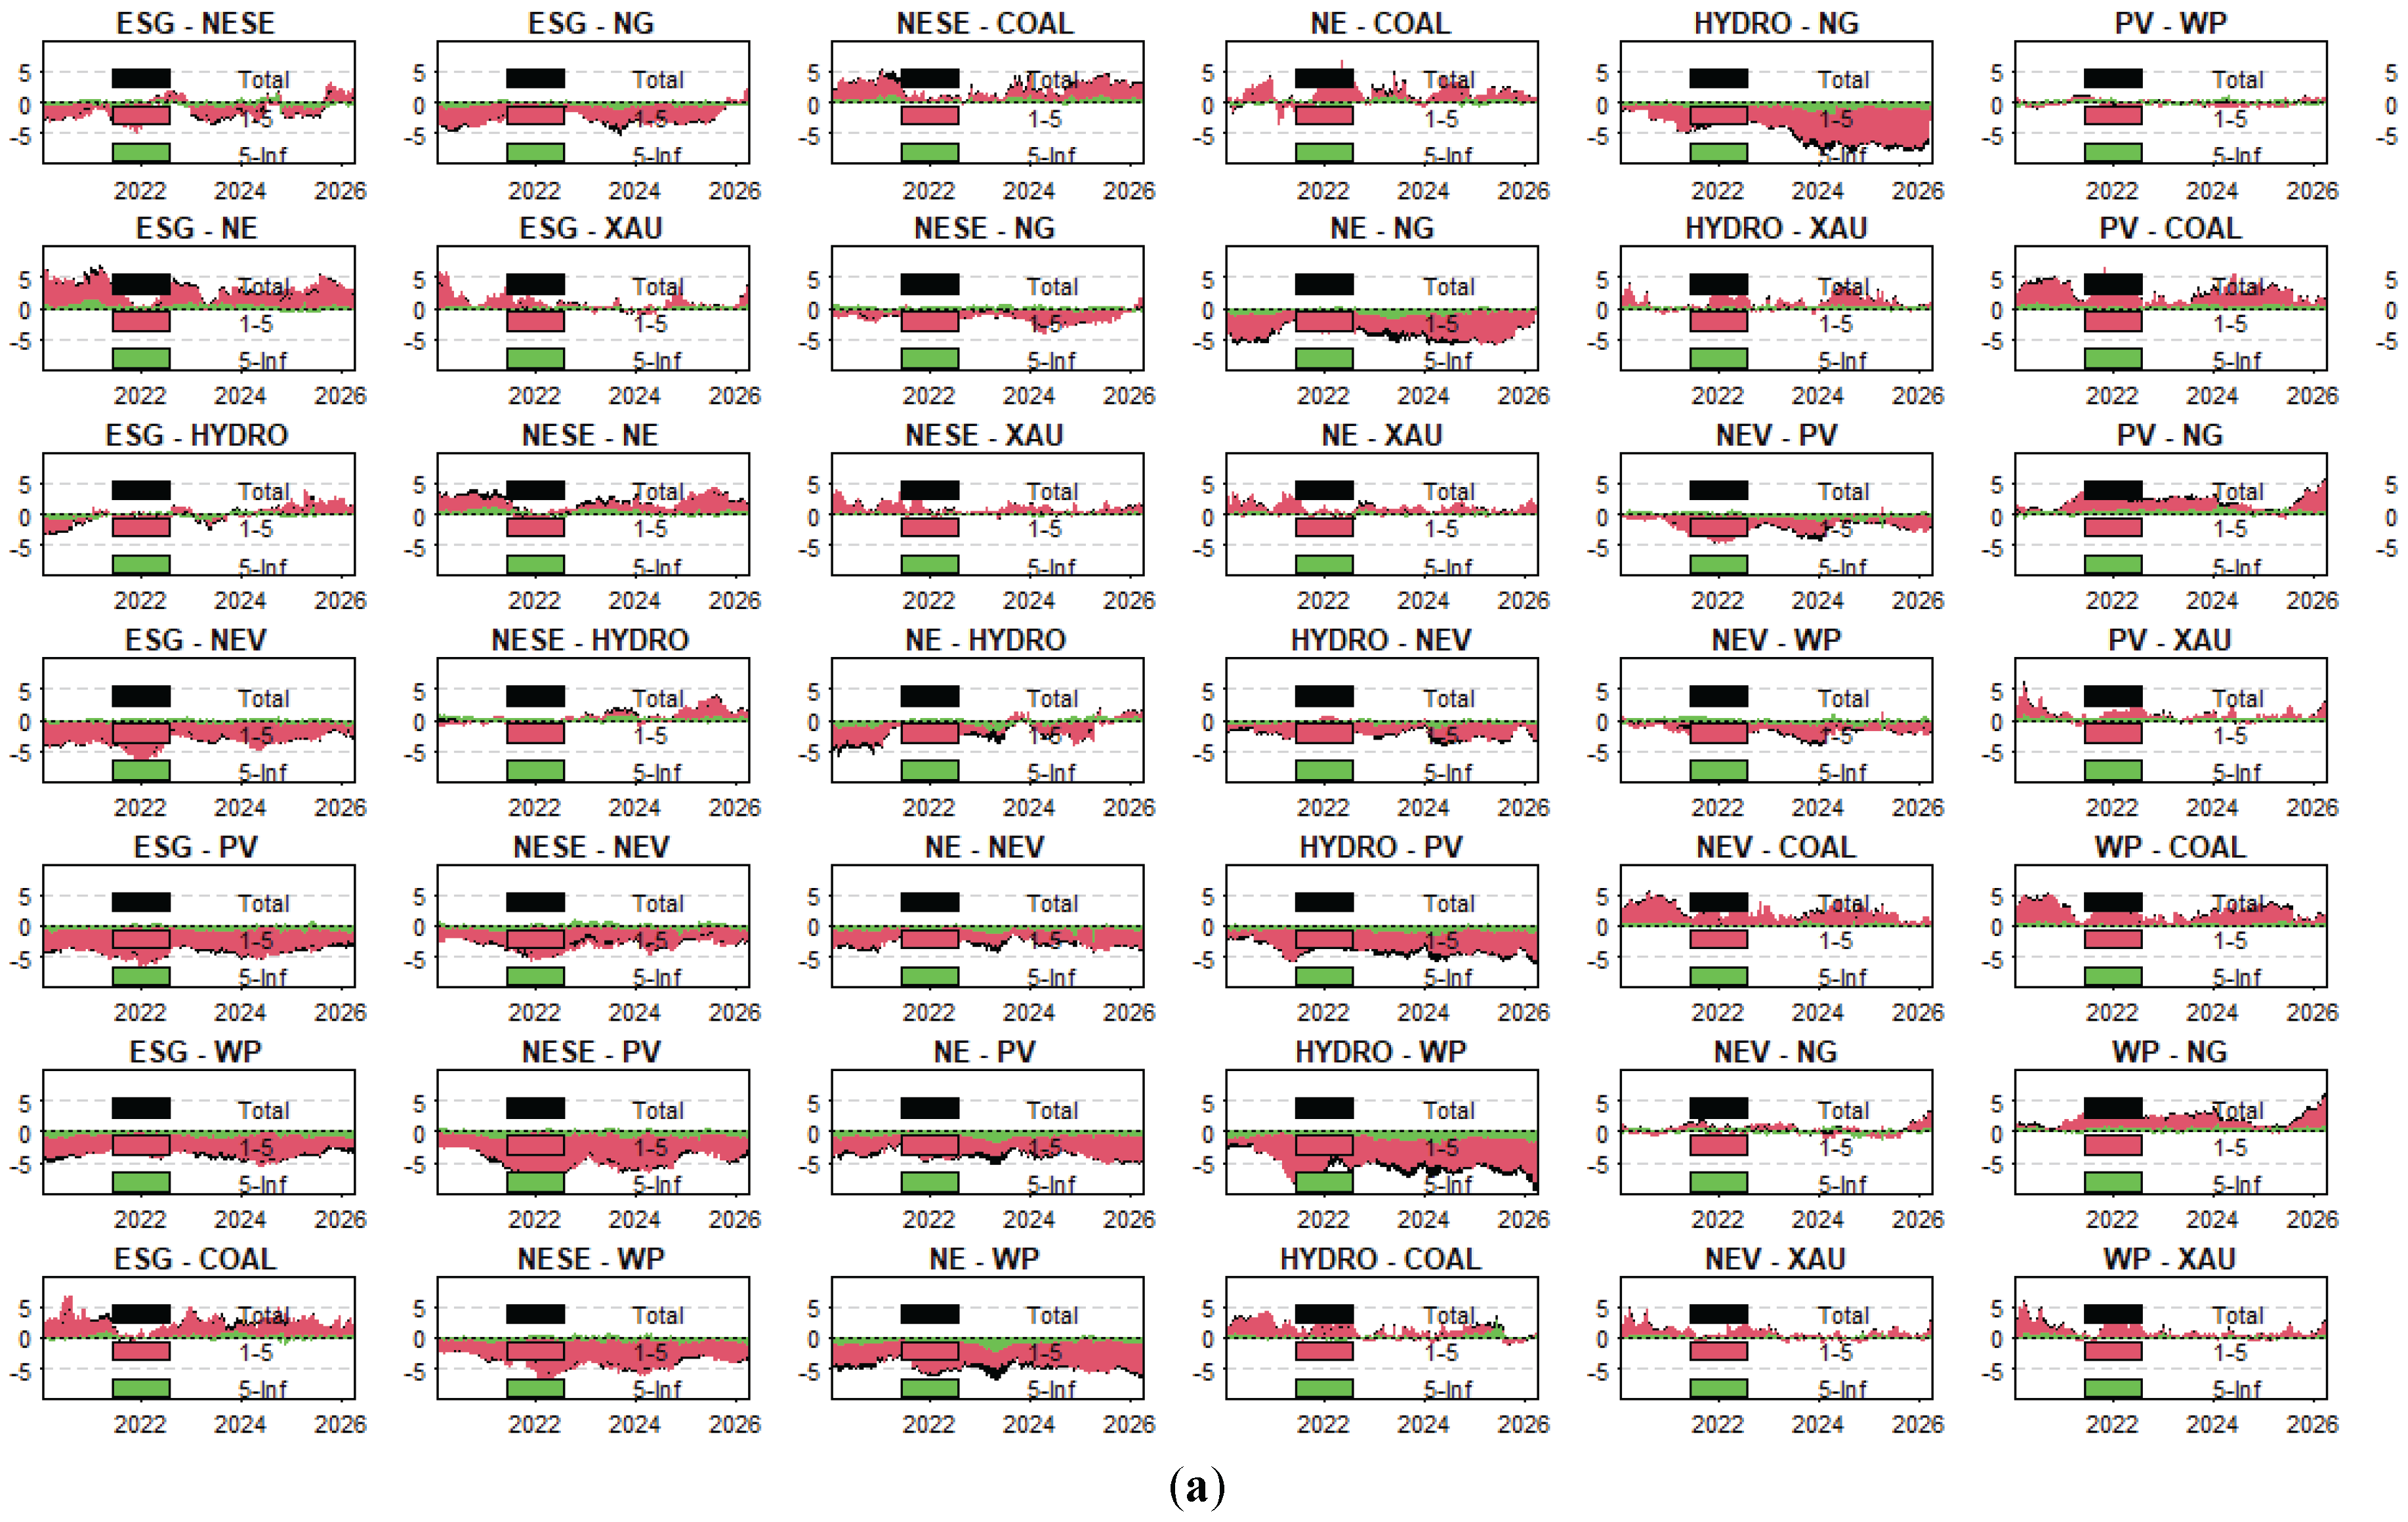
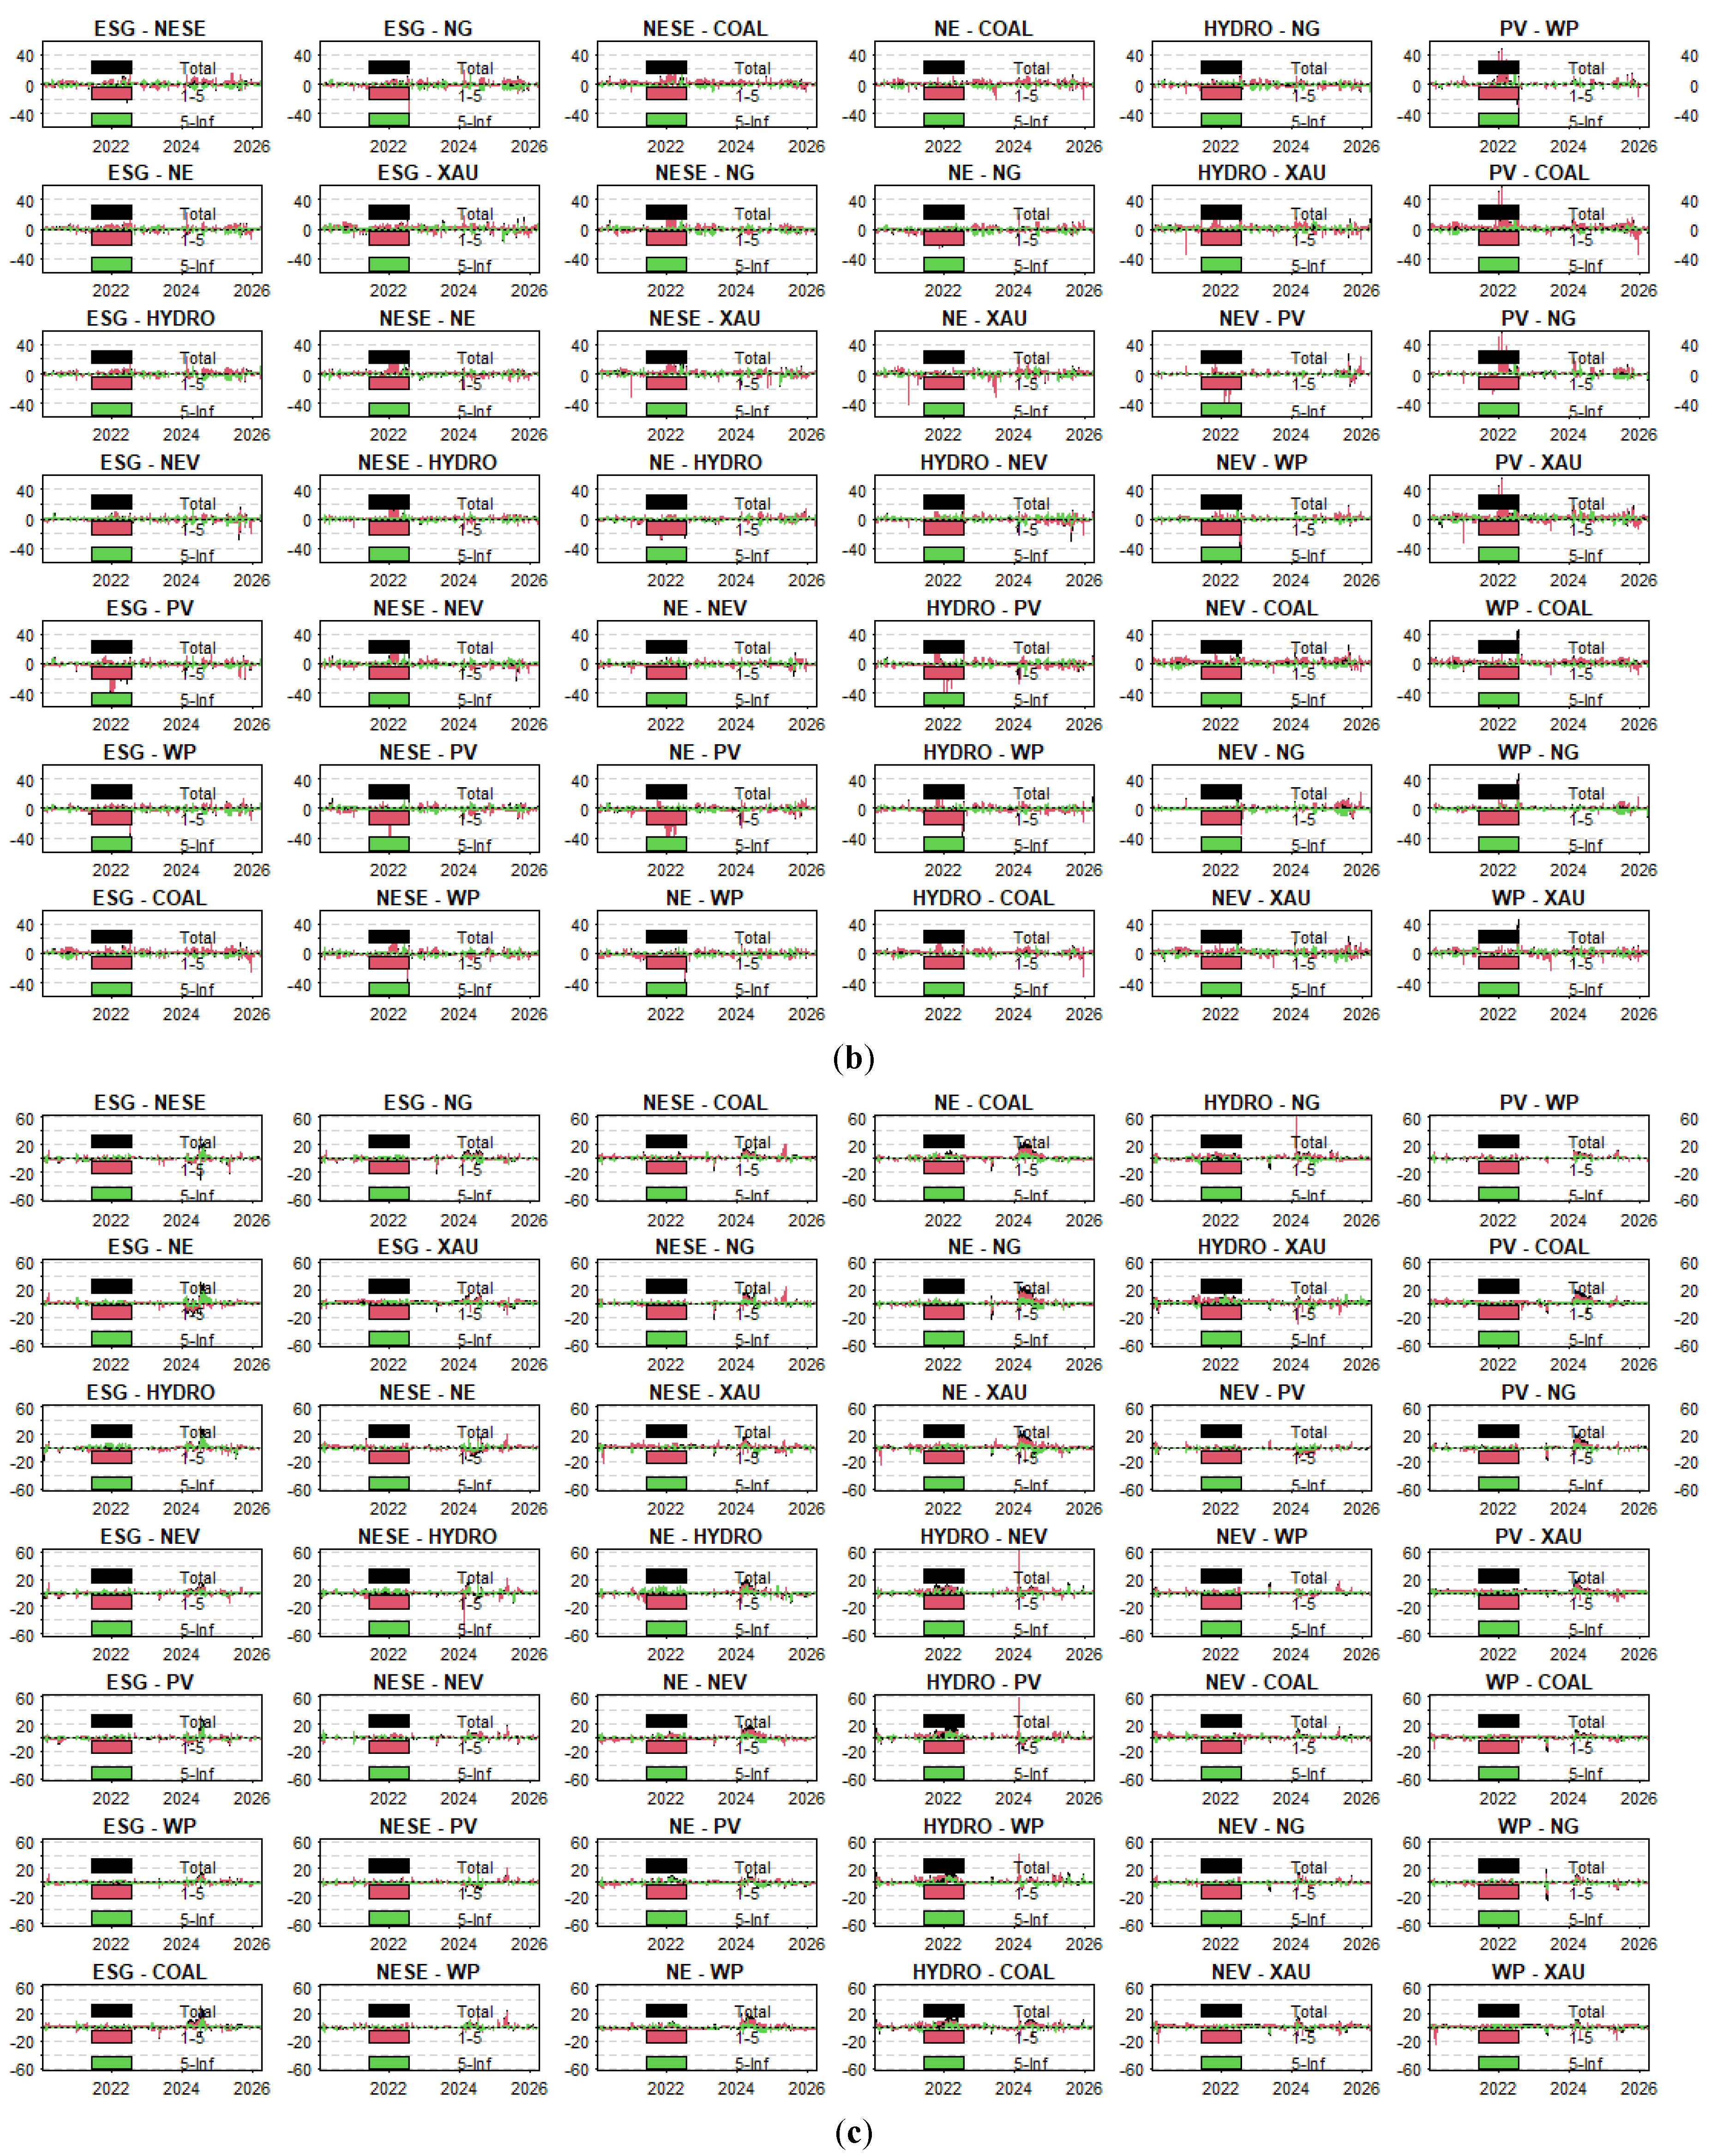
Figure 6.
Spillovers before and after the Russia–Ukraine conflict across frequency bands and market conditions.
Figure 6.
Spillovers before and after the Russia–Ukraine conflict across frequency bands and market conditions.
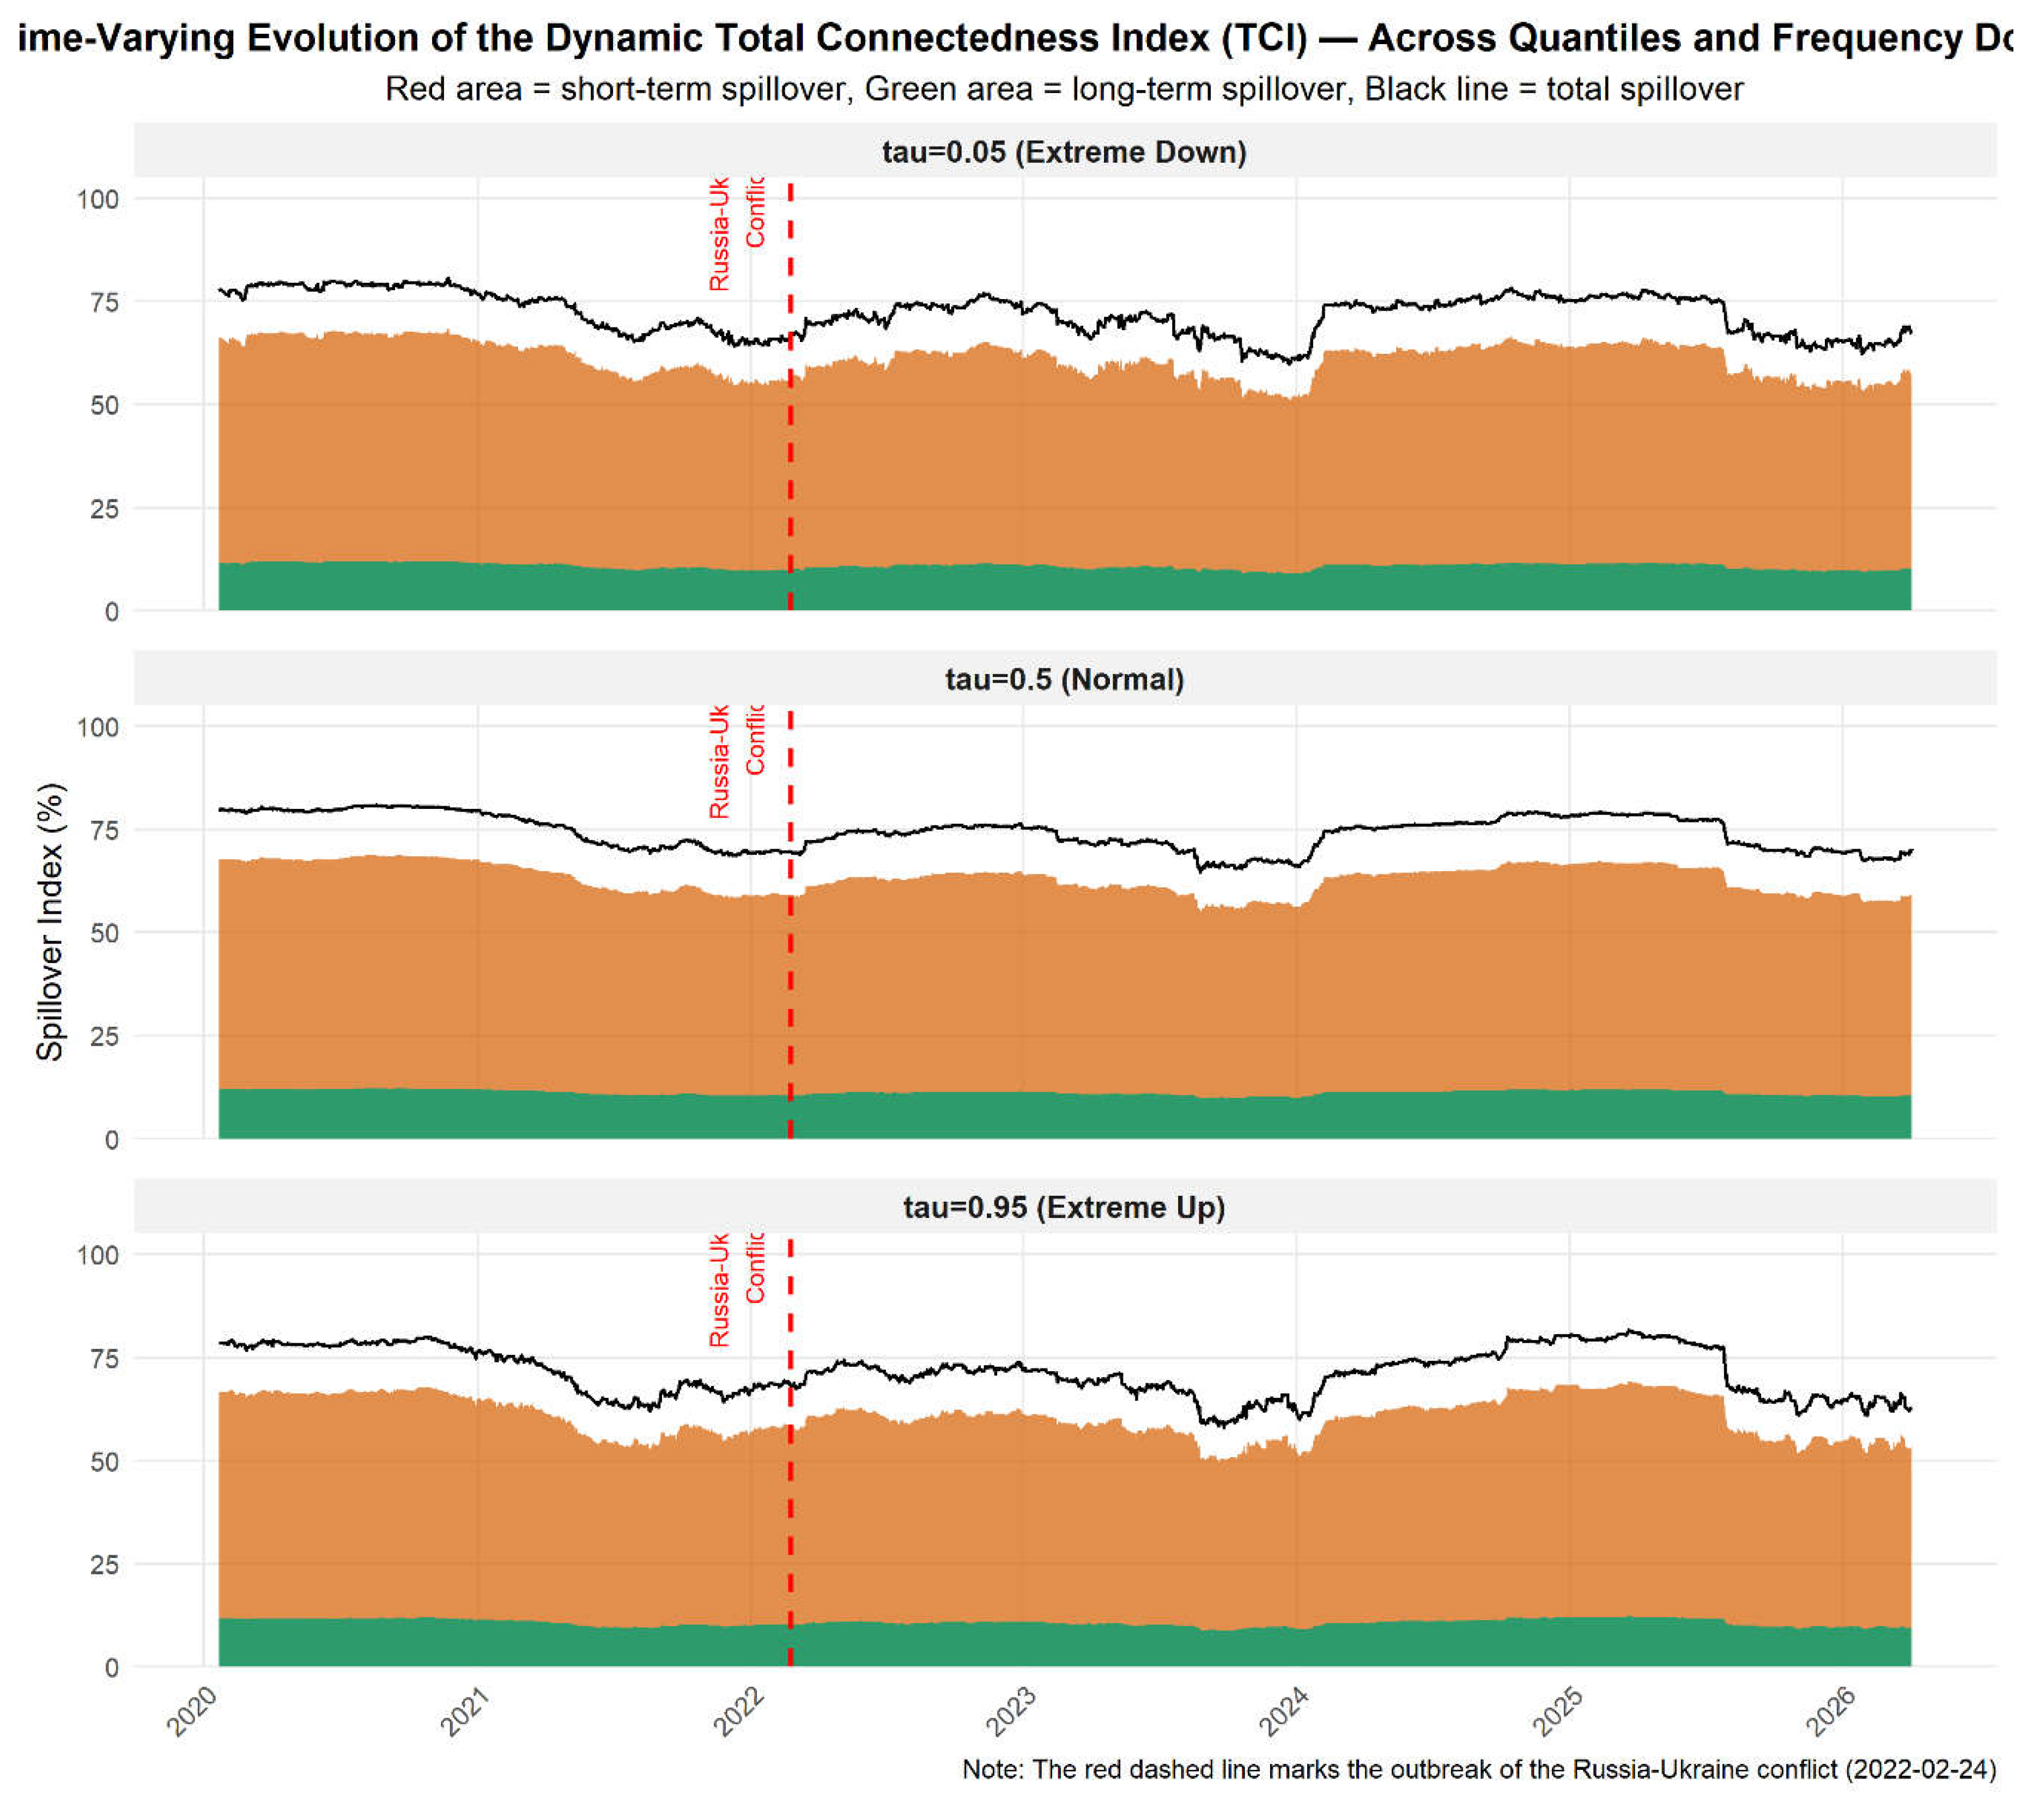

Table 1.
Descriptive statistics of logarithmic returns.
| Statistic | ESG | NESE | NE | HYDRO | NEV | PV | WP | COAL | NG | XAU |
| Mean | 0.009 (0.764) |
0.044 (0.314) |
-0.057 (0.193) |
0.108*** (0.001) |
0.113*** (0.004) |
0.114*** (0.003) |
0.114*** (0.001) |
-0.002 (0.968) |
0.097*** (0.003) |
0.000 (0.977) |
| Variance | 1.47 | 3.309 | 3.316 | 1.73 | 2.553 | 2.431 | 2.139 | 4.329 | 1.751 | 0.217 |
| Skewness | -0.520*** (0.000) |
0.277*** (0.000) |
0.402*** (0.000) |
0.090 (0.129) |
-0.367*** (0.000) |
-0.316*** (0.000) |
-0.262*** (0.000) |
-0.059 (0.316) |
-0.486*** (0.000) |
-2.090*** (0.000) |
| Excess kurtosis | 7.062*** (0.000) |
1.827*** (0.000) |
7.460*** (0.000) |
3.490*** (0.000) |
2.278*** (0.000) |
1.957*** (0.000) |
2.288*** (0.000) |
2.322*** (0.000) |
2.736*** (0.000) |
23.359*** (0.000) |
| JB | 3613.930*** (0.000) |
258.538*** (0.000) |
3992.045*** (0.000) |
866.132*** (0.000) |
406.001*** (0.000) |
299.959*** (0.000) |
390.716*** (0.000) |
383.225*** (0.000) |
597.869*** (0.000) |
39933.048*** (0.000) |
| ERS | -3.322*** (0.001) |
-3.668*** (0.000) |
-15.075*** (0.000) |
-4.530*** (0.000) |
-4.165*** (0.000) |
-3.756*** (0.000) |
-3.510*** (0.000) |
-7.924*** (0.000) |
-3.568*** (0.000) |
-19.535*** (0.000) |
| Q(20) | 8.711 (0.648) |
10.988 (0.402) |
11.699 (0.336) |
20.219** (0.016) |
16.550* (0.069) |
13.490 (0.200) |
23.537*** (0.004) |
23.495*** (0.004) |
40.041*** (0.000) |
22.725*** (0.005) |
| Q²(20) | 196.199*** (0.000) |
128.329*** (0.000) |
43.137*** (0.000) |
387.173*** (0.000) |
350.390*** (0.000) |
297.032*** (0.000) |
339.495*** (0.000) |
384.422*** (0.000) |
396.682*** (0.000) |
91.143*** (0.000) |
Note: ***, ** and * indicate significance at the 1%, 5% and 10% levels, respectively.
Table 2.
Static spillovers under normal market conditions (τ = 0.50).
| Receiver | ESG | NESE | NE | HYDRO | NEV | PV | WP | COAL | NG | XAU | FROM |
| ESG | — | 12.18 (11.19,0.99) |
7.15 (6.48,0.67) |
4.17 (3.76,0.41) |
10.94 (10.15,0.79) |
11.04 (10.2,0.84) |
9.91 (9.14,0.77) |
1.56 (1.39,0.17) |
9.14 (8.4,0.74) |
0.5 (0.44,0.06) |
66.58 (61.15,5.43) |
| NESE | 10.97 (10.08,0.89) |
— | 3.08 (2.85,0.23) |
3.81 (3.52,0.29) |
13.63 (12.64,0.99) |
16.52 (15.31,1.21) |
13.09 (12.16,0.93) |
1.19 (1.07,0.12) |
7.71 (7.18,0.53) |
0.46 (0.43,0.03) |
70.44 (65.23,5.21) |
| NE | 9.98 (9.16,0.82) |
4.83 (4.35,0.48) |
— | 7.63 (6.87,0.76) |
5.19 (4.71,0.48) |
6.63 (6.01,0.62) |
8.4 (7.62,0.78) |
2.21 (2.05,0.16) |
8.32 (7.54,0.78) |
0.59 (0.53,0.06) |
53.77 (48.83,4.94) |
| HYDRO | 4.16 (3.86,0.3) |
4.32 (3.9,0.42) |
5.86 (5.36,0.5) |
— | 6.86 (6.18,0.68) |
10.47 (9.47,1) |
14.79 (13.41,1.38) |
1.31 (1.22,0.09) |
15.11 (13.71,1.4) |
0.63 (0.58,0.05) |
63.51 (57.69,5.82) |
| NEV | 7.62 (6.96,0.66) |
10.85 (9.94,0.91) |
2.62 (2.45,0.17) |
4.95 (4.58,0.37) |
— | 19.48 (17.82,1.66) |
17.28 (15.85,1.43) |
0.93 (0.88,0.05) |
13.09 (12.01,1.08) |
0.37 (0.35,0.02) |
77.17 (70.83,6.34) |
| PV | 7.05 (6.47,0.58) |
11.76 (10.76,1) |
3.07 (2.86,0.21) |
6.7 (6.2,0.5) |
17.54 (16.03,1.51) |
— | 18.38 (16.91,1.47) |
0.9 (0.84,0.06) |
13.53 (12.46,1.07) |
0.41 (0.39,0.02) |
79.36 (72.94,6.42) |
| WP | 6.45 (5.98,0.47) |
9.28 (8.5,0.78) |
3.89 (3.64,0.25) |
9.35 (8.67,0.68) |
15.57 (14.24,1.33) |
18.33 (16.8,1.53) |
— | 0.88 (0.83,0.05) |
15.02 (13.87,1.15) |
0.39 (0.38,0.01) |
79.16 (72.91,6.25) |
| COAL | 3.69 (3.42,0.27) |
3.19 (2.84,0.35) |
3.54 (3.33,0.21) |
2.49 (2.33,0.16) |
2.94 (2.77,0.17) |
3.21 (3,0.21) |
3.02 (2.83,0.19) |
— | 4.14 (3.89,0.25) |
1.21 (1.08,0.13) |
27.42 (25.48,1.94) |
| NG | 6.73 (6.2,0.53) |
6.35 (5.81,0.54) |
4.38 (4.07,0.31) |
10.66 (9.75,0.91) |
13.55 (12.34,1.21) |
15.44 (14.09,1.35) |
17.11 (15.64,1.47) |
1.35 (1.23,0.12) |
— | 0.33 (0.31,0.02) |
75.91 (69.45,6.46) |
| XAU | 1.22 (1.16,0.06) |
1.2 (1.14,0.06) |
1.33 (1.23,0.1) |
1.46 (1.36,0.1) |
1.02 (0.95,0.07) |
1.13 (1.05,0.08) |
1.34 (1.24,0.1) |
1.09 (0.98,0.11) |
1.1 (1,0.1) |
— | 10.89 (10.11,0.78) |
| TO | 57.84 (53.28,4.56) |
63.96 (58.43,5.53) |
34.91 (32.27,2.64) |
51.23 (47.05,4.18) |
87.25 (80.02,7.23) |
102.26 (93.76,8.5) |
103.32 (94.8,8.52) |
11.42 (10.49,0.93) |
87.16 (80.05,7.11) |
4.87 (4.48,0.39) |
TCI |
| NET | -8.74 (-7.87,-0.87) |
-6.48 (-6.8,0.32) |
-18.86 (-16.56,-2.3) |
-12.29 (-10.65,-1.64) |
10.07 (9.18,0.89) |
22.9 (20.82,2.08) |
24.16 (21.89,2.27) |
-15.99 (-14.98,-1.01) |
11.25 (10.6,0.65) |
-6.02 (-5.63,-0.39) |
604.22 (554.62,49.59) |
Table 3.
Static spillovers under extreme downside market conditions (τ = 0.05).
| Receiver | ESG | NESE | NE | HYDRO | NEV | PV | WP | COAL | NG | XAU | FROM |
| ESG | — | 10.41 (8.1,2.31) |
9.7 (7.34,2.36) |
9.13 (6.89,2.24) |
10.52 (7.83,2.69) |
11.04 (8.37,2.67) |
10.2 (7.79,2.41) |
8.35 (6.53,1.82) |
10.08 (7.68,2.4) |
7.65 (5.83,1.82) |
87.07 (66.36,20.71) |
| NESE | 10.21 (8.36,1.85) |
— | 8.79 (7.08,1.71) |
9.1 (7.31,1.79) |
10.73 (8.64,2.09) |
12.05 (10.03,2.02) |
10.61 (8.72,1.89) |
7.92 (6.57,1.35) |
9.85 (8,1.85) |
7.5 (5.95,1.55) |
86.76 (70.66,16.1) |
| NE | 10.06 (8.16,1.9) |
9.51 (7.83,1.68) |
— | 9.97 (8.06,1.91) |
9.66 (7.62,2.04) |
10.38 (8.45,1.93) |
9.93 (8.08,1.85) |
8.78 (7.34,1.44) |
10.04 (8.12,1.92) |
8.58 (6.94,1.64) |
86.9 (70.59,16.31) |
| HYDRO | 9.22 (7.67,1.55) |
9.31 (7.86,1.45) |
9.44 (7.87,1.57) |
— | 10.04 (8.2,1.84) |
10.98 (9.2,1.78) |
10.85 (9.14,1.71) |
7.99 (6.86,1.13) |
11.04 (9.25,1.79) |
8.02 (6.73,1.29) |
86.88 (72.78,14.1) |
| NEV | 9.63 (7.16,2.47) |
10.32 (7.95,2.37) |
8.67 (6.4,2.27) |
9.15 (6.9,2.25) |
— | 12.31 (9.33,2.98) |
11.42 (8.63,2.79) |
7.67 (5.95,1.72) |
10.77 (8.05,2.72) |
7.62 (5.68,1.94) |
87.55 (66.05,21.5) |
| PV | 9.56 (6.47,0.58) |
10.65 (8.52,2.13) |
8.55 (6.61,1.94) |
9.73 (7.41,1.96) |
11.62 (8.98,2.64) |
— | 11.54 (9.1,2.44) |
7.75 (6.3,1.45) |
10.76 (8.43,2.33) |
7.31 (5.82,1.49) |
87.1 (68.54,18.56) |
| WP | 9.36 (7.42,1.94) |
10.14 (8.19,1.95) |
8.7 (6.91,1.79) |
9.73 (7.88,1.85) |
11.48 (8.98,2.5) |
12.38 (9.86,2.52) |
— | 7.69 (6.34,1.35) |
11.05 (8.82,2.23) |
7.35 (5.93,1.42) |
87.87 (70.33,17.54) |
| COAL | 9.34 (8.56,0.78) |
9.48 (8.69,0.79) |
9.17 (8.4,0.77) |
9.31 (8.53,0.78) |
9.61 (8.81,0.8) |
10.34 (9.47,0.87) |
9.53 (8.78,0.75) |
— | 9.66 (8.91,0.75) |
8.93 (8.21,0.72) |
85.38 (78.37,7.01) |
| NG | 9.49 (7.63,1.86) |
9.7 (7.96,1.74) |
8.84 (7.18,1.66) |
9.95 (8.23,1.72) |
11.05 (8.8,2.25) |
11.92 (9.68,2.24) |
11.37 (9.3,2.07) |
8.1 (6.78,1.32) |
— | 7.54 (6.26,1.28) |
87.95 (71.82,16.13) |
| XAU | 9.03 (7.26,1.77) |
9.2 (7.36,1.84) |
9.49 (7.54,1.95) |
9.61 (7.59,2.02) |
9.54 (7.5,2.04) |
10.03 (8.01,2.02) |
9.45 (7.47,1.98) |
9.13 (7.55,1.58) |
9.55 (7.64,1.91) |
— | 85.01 (67.91,17.1) |
| TO | 85.89 (69.6,16.29) |
88.71 (72.45,16.26) |
81.34 (65.33,16.01) |
85.31 (68.8,16.51) |
94.27 (75.37,18.9) |
101.43 (82.39,19.04) |
94.89 (77.01,17.88) |
73.39 (60.23,13.16) |
92.79 (74.89,17.9) |
70.47 (57.34,13.13) |
TCI |
| NET | -1.18 (3.24,-4.42) |
1.95 (1.79,0.16) |
-5.57 (-5.27,-0.3) |
-1.57 (-3.98,2.41) |
6.72 (9.32,-2.6) |
14.33 (13.85,0.48) |
7.02 (6.68,0.34) |
-11.99 (-18.14,6.15) |
4.84 (3.07,1.77) |
-14.53 (-10.56,-3.97) |
868.49 (703.41,165.07) |
Table 4.
Static spillovers under extreme upside market conditions (τ = 0.95).
| Receiver | ESG | NESE | NE | HYDRO | NEV | PV | WP | COAL | NG | XAU | FROM |
| ESG | — | 10.66 (9.59,1.07) |
10.19 (9,1.19) |
9.86 (8.68,1.18) |
10 (9.05,0.95) |
10.4 (9.3,1.1) |
9.73 (8.78,0.95) |
8.27 (7.49,0.78) |
9.88 (8.82,1.06) |
7.55 (6.65,0.9) |
86.55 (77.37,9.18) |
| NESE | 10.19 (8.97,1.22) |
— | 9.55 (8.33,1.22) |
9.99 (8.56,1.43) |
10.48 (9.32,1.16) |
11.13 (9.8,1.33) |
10.08 (8.96,1.12) |
8.14 (7.26,0.88) |
9.65 (8.4,1.25) |
7.9 (6.88,1.02) |
87.11 (76.47,10.64) |
| NE | 10.2 (8.75,1.45) |
9.85 (8.6,1.25) |
— | 10.9 (9.13,1.77) |
9.16 (8.05,1.11) |
9.79 (8.47,1.32) |
9.34 (8.16,1.18) |
8.64 (7.61,1.03) |
9.86 (8.39,1.47) |
8.2 (6.95,1.25) |
85.94 (74.11,11.83) |
| HYDRO | 9.44 (7.74,1.7) |
9.75 (8.08,1.67) |
10.22 (8.05,2.17) |
— | 9.08 (7.6,1.48) |
10.02 (8.34,1.68) |
9.96 (8.33,1.63) |
8.36 (7,1.36) |
10.64 (8.54,2.1) |
8.36 (6.77,1.59) |
85.88 (70.47,15.41) |
| NEV | 9.72 (8.66,1.06) |
10.7 (9.46,1.24) |
9.1 (7.93,1.17) |
9.92 (8.53,1.39) |
— | 11.84 (10.51,1.33) |
10.94 (9.8,1.14) |
7.69 (6.83,0.86) |
10.64 (9.44,1.2) |
7.27 (6.36,0.91) |
87.8 (77.51,10.29) |
| PV | 9.58 (8.46,1.12) |
10.82 (9.64,1.18) |
9.42 (8.15,1.27) |
10.49 (9.02,1.47) |
11.08 (10,1.08) |
— | 11.01 (9.88,1.13) |
7.58 (6.84,0.74) |
10.69 (9.44,1.25) |
7.24 (6.34,0.9) |
87.92 (77.77,10.15) |
| WP | 9.48 (8.49,0.99) |
10.28 (9.23,1.05) |
9.52 (8.3,1.22) |
10.83 (9.35,1.48) |
10.76 (9.82,0.94) |
11.54 (10.42,1.12) |
— | 7.67 (6.92,0.75) |
11.06 (9.85,1.21) |
7.34 (6.43,0.91) |
88.48 (78.8,9.68) |
| COAL | 9.76 (8.49,1.27) |
9.87 (8.61,1.26) |
10.27 (8.86,1.41) |
10.15 (8.7,1.45) |
9.12 (8.02,1.1) |
9.52 (8.33,1.19) |
8.98 (7.92,1.06) |
— | 9.73 (8.44,1.29) |
8.34 (7.28,1.06) |
85.73 (74.64,11.09) |
| NG | 9.62 (8.41,1.21) |
9.7 (8.47,1.23) |
9.53 (8.18,1.35) |
10.87 (9.34,1.53) |
10.56 (9.33,1.23) |
11.18 (9.82,1.36) |
10.91 (9.62,1.29) |
7.95 (7,0.95) |
— | 7.26 (6.29,0.97) |
87.56 (76.46,11.1) |
| XAU | 9.08 (7.92,1.16) |
9.75 (8.51,1.24) |
9.76 (8.38,1.38) |
10.15 (8.45,1.7) |
8.92 (7.81,1.11) |
9.23 (7.96,1.27) |
8.7 (7.54,1.16) |
9.11 (8.11,1) |
8.96 (7.64,1.32) |
— | 83.68 (72.33,11.35) |
| TO | 87.07 (75.9,11.17) |
91.41 (80.21,11.2) |
87.56 (75.17,12.39) |
93.17 (79.76,13.41) |
89.18 (79.01,10.17) |
94.65 (82.94,11.71) |
89.66 (78.99,10.67) |
73.41 (65.06,8.35) |
91.1 (78.95,12.15) |
69.45 (59.94,9.51) |
TCI |
| NET | 0.52 (-1.47,1.99) |
4.3 (3.74,0.56) |
1.62 (1.06,0.56) |
7.31 (9.3,-1.99) |
1.38 (1.5,-0.12) |
6.72 (5.17,1.55) |
1.18 (0.19,0.99) |
-12.32 (-9.58,-2.74) |
3.54 (2.49,1.05) |
-14.23 (-12.39,-1.84) |
866.86 (755.93,110.74) |
Table 5.
Static spillovers under normal market conditions with a 100-day rolling window.
| Receiver | ESG | NESE | NE | HYDRO | NEV | PV | WP | COAL | NG | XAU | FROM |
| ESG | — | 11.71 (10.76,0.95) |
7.26 (6.59,0.67) |
4.65 (4.18,0.47) |
10.78 (9.95,0.83) |
10.79 (9.94,0.85) |
9.76 (8.99,0.77) |
1.95 (1.75,0.2) |
8.87 (8.13,0.74) |
1.02 (0.93,0.09) |
66.8 (61.23,5.57) |
| NESE | 10.67 (9.81,0.86) |
— | 3.54 (3.28,0.26) |
4.3 (3.97,0.33) |
13.27 (12.33,0.94) |
15.97 (14.82,1.15) |
12.86 (11.97,0.89) |
1.54 (1.39,0.15) |
7.75 (7.22,0.53) |
1.05 (0.98,0.07) |
70.95 (65.77,5.18) |
| NE | 9.67 (8.87,0.8) |
5.29 (4.75,0.54) |
— | 7.5 (6.74,0.76) |
5.43 (4.92,0.51) |
6.5 (5.88,0.62) |
8.19 (7.43,0.76) |
2.84 (2.62,0.22) |
7.82 (7.1,0.72) |
1.64 (1.51,0.13) |
54.88 (49.83,5.05) |
| HYDRO | 4.79 (4.42,0.37) |
4.76 (4.29,0.47) |
5.94 (5.44,0.5) |
— | 6.99 (6.25,0.74) |
10.06 (9.03,1.03) |
14.05 (12.67,1.38) |
1.8 (1.63,0.17) |
14.42 (13.03,1.39) |
1.18 (1.06,0.12) |
64 (57.83,6.17) |
| NEV | 7.81 (7.21,0.6) |
10.88 (9.99,0.89) |
2.87 (2.68,0.19) |
5.2 (4.77,0.43) |
— | 18.98 (17.36,1.62) |
16.82 (15.44,1.38) |
1.28 (1.16,0.12) |
12.44 (11.43,1.01) |
0.86 (0.8,0.06) |
77.13 (70.83,6.3) |
| PV | 7.34 (6.8,0.54) |
11.72 (10.72,1) |
3.28 (3.07,0.21) |
6.7 (6.14,0.56) |
17.17 (15.72,1.45) |
— | 18.01 (16.56,1.45) |
1.14 (1.04,0.1) |
13 (11.96,1.04) |
0.85 (0.78,0.07) |
79.21 (72.8,6.41) |
| WP | 6.71 (6.26,0.45) |
9.34 (8.57,0.77) |
3.97 (3.73,0.24) |
9.2 (8.49,0.71) |
15.28 (14,1.28) |
17.98 (16.47,1.51) |
— | 1.15 (1.06,0.09) |
14.61 (13.47,1.14) |
0.83 (0.76,0.07) |
79.07 (72.81,6.26) |
| COAL | 4.33 (3.95,0.38) |
3.86 (3.4,0.46) |
4.03 (3.71,0.32) |
3.17 (2.91,0.26) |
3.64 (3.34,0.3) |
3.85 (3.52,0.33) |
3.58 (3.28,0.3) |
— | 4.49 (4.11,0.38) |
2.27 (2.03,0.24) |
33.22 (30.25,2.97) |
| NG | 6.82 (6.29,0.53) |
6.53 (5.98,0.55) |
4.39 (4.06,0.33) |
10.65 (9.69,0.96) |
13 (11.86,1.14) |
14.91 (13.6,1.31) |
16.77 (15.27,1.5) |
1.66 (1.51,0.15) |
— | 0.84 (0.77,0.07) |
75.57 (69.02,6.55) |
| XAU | 2.34 (2.16,0.18) |
2.33 (2.15,0.18) |
2.88 (2.66,0.22) |
2.56 (2.38,0.18) |
2.12 (1.92,0.2) |
2.31 (2.12,0.19) |
2.55 (2.36,0.19) |
2.28 (2.02,0.26) |
2.26 (2.06,0.2) |
— | 21.64 (19.84,1.8) |
| TO | 60.49 (55.78,4.71) |
66.4 (60.6,5.8) |
38.17 (35.23,2.94) |
53.92 (49.27,4.65) |
87.68 (80.29,7.39) |
101.37 (92.75,8.62) |
102.59 (93.97,8.62) |
15.66 (14.19,1.47) |
85.65 (78.51,7.14) |
10.54 (9.61,0.93) |
TCI |
| NET | -6.32 (-5.45,-0.87) |
-4.55 (-5.17,0.62) |
-16.71 (-14.6,-2.11) |
-10.07 (-8.55,-1.52) |
10.55 (9.46,1.09) |
22.15 (19.95,2.2) |
23.51 (21.15,2.36) |
-17.57 (-16.06,-1.51) |
10.1 (9.5,0.6) |
-11.09 (-10.22,-0.87) |
622.47 (570.21,52.26) |
Table 6.
Static spillovers under normal market conditions with a 300-day rolling window.
| Receiver | ESG | NESE | NE | HYDRO | NEV | PV | WP | COAL | NG | XAU | FROM |
| ESG | — | 12.41 (11.37,1.04) |
7.12 (6.47,0.65) |
4.06 (3.67,0.39) |
11.08 (10.28,0.8) |
11.15 (10.3,0.85) |
9.9 (9.12,0.78) |
1.42 (1.28,0.14) |
9.15 (8.41,0.74) |
0.3 (0.27,0.03) |
66.58 (61.16,5.42) |
| NESE | 11.22 (10.31,0.91) |
— | 2.92 (2.71,0.21) |
3.45 (3.19,0.26) |
13.76 (12.77,0.99) |
16.73 (15.5,1.23) |
13.08 (12.16,0.92) |
1.05 (0.95,0.1) |
7.58 (7.07,0.51) |
0.34 (0.33,0.01) |
70.14 (64.99,5.15) |
| NE | 9.86 (9,0.86) |
4.62 (4.15,0.47) |
— | 8 (7.22,0.78) |
5.21 (4.74,0.47) |
6.78 (6.16,0.62) |
8.62 (7.83,0.79) |
1.96 (1.83,0.13) |
8.45 (7.67,0.78) |
0.31 (0.28,0.03) |
53.8 (48.89,4.91) |
| HYDRO | 4.11 (3.81,0.3) |
3.99 (3.6,0.39) |
6.16 (5.64,0.52) |
— | 7 (6.32,0.68) |
10.76 (9.75,1.01) |
15.21 (13.83,1.38) |
1.07 (1.01,0.06) |
15.51 (14.1,1.41) |
0.45 (0.42,0.03) |
64.26 (58.47,5.79) |
| NEV | 7.62 (6.93,0.69) |
10.7 (9.77,0.93) |
2.58 (2.4,0.18) |
4.88 (4.52,0.36) |
— | 19.6 (17.88,1.72) |
17.41 (15.93,1.48) |
0.84 (0.8,0.04) |
13.45 (12.33,1.12) |
0.23 (0.22,0.01) |
77.33 (70.78,6.55) |
| PV | 7 (6.44,0.56) |
11.66 (10.65,1.01) |
3.07 (2.85,0.22) |
6.72 (6.23,0.49) |
17.69 (16.16,1.53) |
— | 18.46 (16.97,1.49) |
0.82 (0.77,0.05) |
13.77 (12.69,1.08) |
0.26 (0.25,0.01) |
79.44 (73.01,6.43) |
| WP | 6.32 (5.85,0.47) |
9.12 (8.35,0.77) |
3.96 (3.7,0.26) |
9.46 (8.77,0.69) |
15.72 (14.37,1.35) |
18.42 (16.88,1.54) |
— | 0.78 (0.74,0.04) |
15.25 (14.09,1.16) |
0.25 (0.24,0.01) |
79.24 (72.96,6.28) |
| COAL | 3.32 (3.11,0.21) |
2.69 (2.44,0.25) |
3.24 (3.07,0.17) |
2.14 (2.02,0.12) |
2.74 (2.6,0.14) |
3.01 (2.84,0.17) |
2.81 (2.65,0.16) |
— | 4.09 (3.86,0.23) |
0.82 (0.72,0.1) |
24.88 (23.33,1.55) |
| NG | 6.64 (6.12,0.52) |
6.08 (5.57,0.51) |
4.41 (4.12,0.29) |
10.73 (9.84,0.89) |
13.91 (12.68,1.23) |
15.66 (14.31,1.35) |
17.28 (15.83,1.45) |
1.26 (1.16,0.1) |
— | 0.19 (0.18,0.01) |
76.17 (69.81,6.36) |
| XAU | 0.66 (0.64,0.02) |
0.8 (0.77,0.03) |
0.73 (0.68,0.05) |
1.06 (0.98,0.08) |
0.7 (0.65,0.05) |
0.67 (0.62,0.05) |
0.87 (0.79,0.08) |
0.83 (0.73,0.1) |
0.64 (0.57,0.07) |
— | 6.93 (6.41,0.52) |
| TO | 56.73 (52.2,4.53) |
62.06 (56.66,5.4) |
34.19 (31.63,2.56) |
50.48 (46.43,4.05) |
87.79 (80.57,7.22) |
102.81 (94.25,8.56) |
103.64 (95.11,8.53) |
10.02 (9.27,0.75) |
87.88 (80.78,7.1) |
3.17 (2.91,0.26) |
TCI |
| NET | -9.85 (-8.96,-0.89) |
-8.08 (-8.33,0.25) |
-19.61 (-17.26,-2.35) |
-13.78 (-12.04,-1.74) |
10.46 (9.79,0.67) |
23.37 (21.24,2.13) |
24.41 (22.15,2.26) |
-14.86 (-14.05,-0.81) |
11.71 (10.97,0.74) |
-3.76 (-3.5,-0.26) |
598.77 (549.83,48.96) |
Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content. |
© 2026 by the authors. Licensee MDPI, Basel, Switzerland. This article is an open access article distributed under the terms and conditions of the Creative Commons Attribution (CC BY) license.
Copyright: This open access article is published under a Creative Commons CC BY 4.0 license, which permit the free download, distribution, and reuse, provided that the author and preprint are cited in any reuse.