

Submitted:
09 September 2026
Posted:
10 September 2026
You are already at the latest version
Abstract
This study examines the relationship between eco-innovation (EI) and working capital efficiency (WCE), with corporate social responsibility (CSR) acting as a mediator. Based on the Resource-Based View, Stakeholder, Legitimacy, and Shareholder theories, the study examines how well sustainability-focused tactics improve businesses’ operational success. WCE is measured using the cash conversion cycle (CCC) and its components, including accounts payable period (APP), inventory conversion or holding period (ICP), and accounts receivable period (ACP). Based on the panel-data and strong regression models and firm-level controls, time, and industry effects, the results suggest that eco-innovation positively influences the working capital efficiency through the reduction of cash conversion cycles and the improvement of working processes. This relationship is partly mediated by CSR, which indicates that eco-innovation improves efficiency directly and indirectly via the better stakeholder engagement and responsible practices. The research adds to the literature by identifying a connection between sustainability practices and financial performance and the significance of incorporating eco-innovation and CSR to obtain sustainable operational performance.
Keywords:
eco-innovation
; corporate social responsibility (CSR)
; working capital efficiency
; cash conversion cycle
; mediation analysis
; stakeholder theory
; sustainable finance
; panel data
1. Introduction
The modern world economy is becoming more of a product of the twin forces of economic development and environmental friendliness. In the past few decades, the growth of industry and the development of the world competition put a strong strain on the resource consumption and environmental degradation, which resulted in such systemic issues as climate change, ecological imbalance, and regulation involvement (Bolton & Kacperczyk, 2021; Zhang et al., 2020). Such changes have forced companies to re-evaluate traditional business formats and integrate sustainability-based ideas into their business operations. It is against this backdrop that the idea of usage of environmental innovation is becoming an imperative strategic reaction that can help firms to both become environmentally responsible and economically efficient.
Eco-innovation, which can be generally described as the creation of product, process, and organizational behavior that minimize the harmful affect on environment, has become one of the prominent tools to attain sustainable competitive advantage (Rennings, 2000; Liao and Tsai, 2019). Contrary to traditional innovation, eco-innovation involves environmental focus into business strategy and thus, deals simultaneously with regulatory pressures as well as expectations of stakeholders. Institutional investors and financial markets are another source of the growing significance of eco-innovation as they are increasingly introducing environmental performance into investment choices (Flammer, 2021). As such, the companies that undertake eco-innovation are not only making the environment more sustainable, but also making them financially sound and sustainable.
Although eco-innovation is a strategic issue, its financial implications are still a debated topic. Arguments made in the early theoretical view held that environmental programs add extra expenditure on companies that could lead to decrease in profitability and competitiveness (Walley & Whitehead, 1994). The Porter theory however, argues that environmental practices that are designed can enhance innovation, and effectiveness to use resources and eventually, the performance of firms (Porter & van der Linde, 1995). Empirical data give a divided view as to whether these opposing views hold true, some of the studies record positive impacts of green innovation on financial indicator (Ambec et. al., 2013; Hao & He, 2022), and others record neutral or context-dependent effects.
The main weakness of current studies is that they are mostly in the form of long-term financial performance indicators like profitability and firm value whereas little consideration has been given to short-term operational efficiency indicators. One of these is WCE, which is a basic element of firm performance, indicating how well firms use their short-term or current resources like assets and liability. Working capital or operating cash flow plays a critical role in ensuring that the business can still operate and it is not dependent on external sources of funding (Deloof, 2003). Efficient utilization of working capital or operating cash flow helps firms to maximize cash flows, reduce financing costs, as well as, to increase financial stability.
A complete measure of working capital efficiency used by other researches is the cash conversion cycle (CCC), and components, namely, average collection or receivable period (ACP), inventory holding period (ICP), and average payable or payback period (APP). These elements reflect the time it takes to transform investments in inventory and receivables into cash, less time it takes to pay the suppliers. The smaller the CCC, the more efficient the company is, which is why its cash recovery will be faster and liquidity will be managed better. The determinants of working capital efficiency have been thoroughly researched, but the role of the sustainability-oriented strategies like eco-innovation is not well researched.
In theory, eco-innovation can impact working capital efficiency in a variety of ways. First, eco-innovation optimizes the efficiency of operations, meaning that waste is minimized, processes are optimized and resources are optimized, which can result in shorter inventory holding periods (ICP). Second, the reputation of firms that go through eco-innovation and customer confidence will increase, which can speed up the collection of receivables and the average collection or recievable period (ACP). Third, eco-innovation enhances connections with suppliers as it indicates financial stability and ethical intentions, which might allow firms to agree on long-term payments and raise average payable period (APP). All these effects help in a decrease in the cash conversion cycle coupled with an increase in the working capital efficiency.
Besides these direct impacts, eco-innovation is also highly connected with the governance tool named as corporate social responsibility (CSR) which is an indication of how a firm is focused to incorporate indicators like enviormental aspects, governance aspects and social aspects issues in its operations. CSR would increase transparency, decrease information asymmetry, and reinforce stakeholder relationships (Dhaliwal et. al., 2011; Cheng et. al., 2014). The benefits are especially applicable to the working capital management and efficiency as they enable access to trade credit, enhance the trust of suppliers and customer loyalty. CSR can therefore serve as a mediating factor in which eco-innovation impacts working capital efficiency.
Moreover, corporate governance mechanisms, especially board gender diversity (BGD), can mediate the association between eco-innovation and working capital efficiency. The female directors tend to be more sensitive to environmental and social concerns resulting in a better sustainability performance and conservative financial policy. Consequently, the positive effect of eco-innovation on the working capital efficiency due to female directors could be reinforced through the quality of governance and decreased operational risk.
In spite of these theoretical interconnections, the available literature has been mainly focusing on eco-innovation, CSR as well as corporate governance in isolation. Although the interlinkage between these factors and their overall effect on the efficiency of working capital has a wide gap in the current understanding. The mediating role of CSR and the moderating role of board gender diversity in eco-innovation working capital efficiency nexus have not been thoroughly investigated.
This research makes this connection since it analyzes the link between eco-innovation and the working capital efficiency in terms of CSR. This research uses the principles from stakeholder theory in developing an integrated approach towards financial implications of sustainable strategies. In this gradually globalized world, all areas of human interaction are interwoven with the insatiable desire to consume energy (Yen, et al., 2023). Markedly, the global business environment is a place which is fueled by this energy lifeline (Li, et al., 2022).
Due to the unceasing business expansion and profitability that have been guided by an unstable world, has been thrust into the continuous cycle of over consumption and over production, which in turn has predisposed the world to increasing dangers such as climate change (Phung, et al., 2022). This has been an increasing global eco-environmental degradation that is turning into a crisis, and requires a sense of urgency in a paradigm shift in economic approaches that has pushed eco-innovation into the spotlight of sustainable development of most countries and companies around the world (Wang, et al., 2024). Following the ever-increasing environmental degradation caused by the unstoppable exploitation of the limited resources of our planet and the unceasing advancement of industrialization, there has been a thunderclap of voices of concerned people clamoring to the call of a determined and uncompromising action to preserve the natural sanctity of our world (Deng et al., 2023; Zhang, et al., 2020) The journey towards this climate resilient sustainable growth is pushed by institutional investor and equity analysts (Zaman, et al., 2020).
Within sweeping context, eco-innovation (or environmental and green innovation) is linked with the innovation that will result in the reduction of harmful impacts on the environment (Marco-Lajara, et al., 2023) (Liao and Tsai, 2019). The need to adopt sustainability has become a leading organizational decision making approach in all parts of the world due to radical environmental decision making, and growing public pressure (Chang, et al., 2023) (Lin, et al., 2021). The refinement of products and processes to decrease pollution and comply with environmental protection standards is a way of organically ingrained by organisations as a way to act as a catalyst that brings business together with green innovation (Dong, et al., 2022). This dynamic model does not only promote economic value but is also crucial in the promotion of sustainable development (Han, et al., 2022). Following the growing wave of environmental degradation caused by the relentless exploitation of the finite resources of our planet and the unstoppable process of industrialization, the cry of concerned voices has burst out in a thunderous wave (Deng et al., 2023) (Zhang, et al., 2020).
Within the context of eco-innovation strategies, scholars are committed to unravel the techniques embraced by companies with the overall aim that is to reduce the impacts on the environment. One of the significant areas of debate is the effects of such strategies on the performance of the implementing firms (Madalenoa, et. al, 2020). There was a prevailing belief among the economists, policymakers and business strategists that eco-innovative strategies inherently lead to internal costs without any impact on profits. Nevertheless, (Barbieri, et. al, 2016; E., 2013; Jové-Llopis and Segarra-Blasco, 2018) recent empirical studies have revealed a continuum of findings with negative to positive relationships between eco-innovation and firm performance.
The inconsistency of empirical studies stresses the complexity of this link and calls for further analysis, especially in relation to issues associated with the size of businesses and their access to financing. This leads to the main question, does eco-innovation affect the financial performance and trade operations of enterprises (Yaotian, et al., 2023). Linking short term financing with working capital management, working capital represents the lifeline when talking about operational financing of businesses (Ferrando and Mulier, 2013; Banos-Caballero et al., 2010). As indicated from the previous literature, there is a positive correlation between working capital efficiency and high firm performance (Chambers and Cifter, 2022), contributing to the financial value of the company only in the case of financially distressed enterprises (Kieschnick et al., 2013). One may argue that this happens due to the efficient use of working capital management that provides companies with internal financing resources (Banerjee et al., 2021). The increasing attention to WCE in research shows its importance for the development of enterprises (Afrifa, et. al, 2022; Aktas et al., 2015; Shin and Soenen, 1988).
Similarly, there is concrete evidence that supports the beneficial effect of adopting eco-innovation to facilitating the financial stress that firm experiences when obtaining credit funding through banks (Zhang et al. 2020). By adopting eco-innovation, a firm is not merely going to be environmentally sensitive, but it will be an indicator of corporate social responsibility (CSR), which increases its marketability. Such good reputation on the other hand assists in minimizing the default risk of firms and it provides them an edge in their ability to acquire loans. Therefore, it can be argued that eco-innovation can positively impact working capital efficiency and working capital management and efficiency (WCM).
And, of course, working capital is not only about keeping the books balanced; it also will be useful in financing firms (Chen, et al., 2019).
1.1. Economic Rationale
The importance of identifying the effect of eco-innovation on the working capital of a company is crucial. The stakeholders, such as suppliers, customers, and the lenders, are interested in evaluating the stability of a firm, taking into account such factors as Corporate Social Responsibility (CSR), environmental activities, and sales increase (Frow & Payne, 2011). A closer look into the eco-innovation operations will show that the company is committed to environmental sustainability and CSR practices (Loureiro et al., 2020), which results in such advantages as growth in customer loyalty, lessening financial limitations, minimization of environmental influence, and market stabilization (Huang and Huang, 2022).
Moreover, raw material suppliers have confidence in the stability of a firm and this gives them long credit periods to supply raw materials. Eco-innovation on the customer front enhances the relationship between a firm and potential buyer and in doing so, a firm can boost its sales volume by selling them in batch. Eco-innovation, therefore, enhances the effectiveness and efficiency of working capital of the firms, which acts as a second financing source. In case of a lack of primary funding by banks, companies may increase the volume of working capital to satisfy their financial requirements. It is emphasized in the existing literature that eco-innovation can assist in reducing the problem of financing (Zhang et al., 2020).
The point that raises curiosity is whether the benefits of eco-innovation are tangible to businesses. It is still an open area of study when it comes to the link between eco-innovation and working capital.
1.2. Research Gap
The literature on eco-innovation and firm performance is quite abundant (Zhang, et al., 2020), demonstrating the beneficial effect of innovative green practices. Nevertheless, there is a huge gap in the knowledge of the effect of eco-innovation on Working Capital Efficiency (WCE), and the effect of Corporate Social Responsibility (CSR) as a mediator to this relationship is still unknown. Mechanisms of CSR mediation of the relationship between eco-innovation and WCE are new and least explored fields of current research. Incorporating those unstudied aspects into the current literature will give a more detailed insight into the avenues by which eco-innovation impacts WCE. Exploring the mediation role of CSR in the eco-innovation and WCE association is essential in revealing the particular dynamics at work in the context of sustainable financial operations. The gap in the research highlights the necessity of an in-depth study of the interaction between eco-innovation, CSR, and WCE as a part of a more holistic view of the environmental and financial impacts of the innovative practices.
1.3. Research Question
- Is working capital efficiency influenced by eco-innovation?
- Is the correlation between eco-innovation and working capital efficiency mediated by CSR?
1.4. Problem Statement
The growing global eco-environmental degradation is developing into a crisis, requiring a sense of urgency in the economic paradigm shift, and has made eco-innovation a form of sustainable development to numerous countries and companies around the world (Wang, et al., 2023). The intersection of eco-innovation, the effective management of the working capital and the necessity of Corporate Social Responsibility (CSR) is a burning issue in the contemporary corporate environment. Although the necessity of sustainable practices in business activities becomes more and more established, a substantial gap in the literature on the interdependent relationship of eco-innovation and working capital efficiency (WCE), especially in the framework of CSR, is observed. Lack of detailed research on the synergistic effect of these factors prevents a complete view of the ways in which business can successfully combine the environmentally aware approach to business with financial effectiveness. The study will fill this gap of critical importance by examining the routes where these variables intersect and it will present a new angle of understanding the collaborative role of eco-innovation, CSR and WCE. The research aims to make a valuable contribution to the sustainable corporate practices, which is why the more inclusive and interdisciplinary approach to the understanding of the multidimensional dynamics of the contemporary business practices is urgently needed.
1.5. Research Objectives
- To examine the relationship between eco-innovation and working capital efficiency (WCE) in modern business environments.
- To determine the degree to which CSR mediates the relationship between eco-innovation and WCE strategies.
2. Literature Review
This study brings together four different theoretical approaches, which cannot be classified as mutually exclusive, the Legitimacy Theory, and the Resource-Based View (RBV) and the Shareholder Theory, and the Stakeholder Theory to form a theoretical framework that helps us understand how eco-innovation (EI), corporate social responsibility (CSR), board gender diversity (BGD), and working capital efficiency (WCE) relate to each other. All these theories offer a multidimensional approach to analyzing organizational processes and, therefore, help us understand the effects of sustainability-related actions on the efficiency of firm operations.
The Shareholder Theory, put forward for the first time by Friedman (1962, 1970), focuses on the maximization of shareholder wealth as the ultimate goal of firm operation. According to this theory, the management of a firm should operate in such a way as to reflect the interests of its owners, which are the shareholders (Fontrodona and Sison, 2006). In the context of this approach, all firm activities aimed at achieving competitiveness, profitability, and operational efficiency are justified. The efficiency of working capital, which is measured by the cash conversion cycle and the cash conversion cycle components, is closely related to the liquidity management and the performance of the firm, thus aligning with the goals of shareholder wealth maximization (Wasiuzzaman, 2015; Högerle et al., 2020). Nevertheless, the theory of shareholders has been labeled as being excessively focused on finance and its lack of attention to the wider organizational responsibilities (Freeman, 1994; O’Connell and Ward, 2020). These criticisms notwithstanding, it is still relevant because it offers the logic base on which efficiency gains, which have been achieved due to eco-innovation, can be assessed on whether it has value to the shareholders.
Stakeholder theory was postulated by Freeman (1984) whereby a firm’s scope of responsibility included not only the business itself but also many other stakeholders which could be employees, customers, suppliers, and the community as a whole. The stakeholders were described as any party which had either influence over the success of an organization’s goals or was affected by those organizational goals (Donaldson and Preston, 1995). This stakeholder theory suggests that creating long-term value depends on the ability of a company to manage the various interests of its stakeholders. In this sense, CSR emerges as a core process by which companies relate to stakeholders and develop relationships that are founded on trust. Effective stakeholder management increases collaboration with suppliers, boosts customer loyalty, and institutional support that affect operational processes and efficiency (Clarkson, 1995; Mansell, 2013). Stakeholder theory therefore offers a critical basis of comprehending how CSR could serve as a channel through which eco-innovation impacts on working capital efficiency as firms adjust their working practices to the expectation of the stakeholders.
The Legitimacy Theory also expands the theoretical concept by stating that approval and conformity to the societal norms is vital. The legitimacy is based on the concept of organizational legitimacy put forth by Dowling and Pfeffer (1975) and can be defined as the idea that the behaviours of a firm are correct in a socially constructed system of values and beliefs (Suchman, 1995). This theory posits that firms are guided by a social contract and their existence is determined by their ability to keep congruency between their operations and the expectations of the society (Burlea & Popa, 2013). Corporate reporting, especially in environmental and social reporting is a key instrument in minimizing the legitimacy gap that can be experienced when there is failure to fulfill the societal expectations (Guthrie et al., 2006). In this context, CSR and sustainability efforts in the context of earning legitimacy, minimizing risk specific to the firm, and securing access to resources and markets (Bansal and Clelland, 2004). The legitimacy theory is of special interest in understanding why companies resort to the practice of eco-innovation and CSR that goes beyond the economic reasons, as such practices assist in gaining acceptance in society and stabilizing the conditions under which firms operate.
In addition to these views, the Resource-Based View (RBV) is a strategic interpretation of the role of internal capabilities in creating a long-term competitive advantage. According to RBV, superior performance of firms comes about as a result of creating valuable, rare, inimitable, and non-substitutable (VRIN) resources (Barney, 1991).
In that regard, eco-innovation might be considered a strategic power enabling to improve the efficiency of the resources involved, minimise waste, and optimise processes. On the same note, CSR can be theorized as an intangible resource that enhances reputation, relationship with stakeholders and organizational culture which contributes to long-term performance (Hart, 1995). Gender diversity in boards also increases the resource base of the firm as it brings different perspectives to the firm, increases the quality of decisions and governance effectiveness (Terjesen et al., 2016). All these abilities allow companies to maximize the elements of working capital, including inventory management, accounts receivables collection, and payables structuring, to enhance efficiency. RBV therefore offers the rationales behind internal strategic resources and capabilities to operational outcomes.
A combination of these four theories forms a multi-layered and integrated framework. Shareholder Theory offers the financial explanation of efficiency gains, Stakeholder Theory underlines the relational cases that foster operational performance, Legitimacy Theory offers the societal pressures on the firm behaviour and RBV focuses on the strategic capabilities to drive efficiency. Combined, these views provide a thorough basis on how eco-innovation, CSR, and gender diversity of the board affect working capital efficiency to close the gap between financial performance and sustainability practices and strategic management.
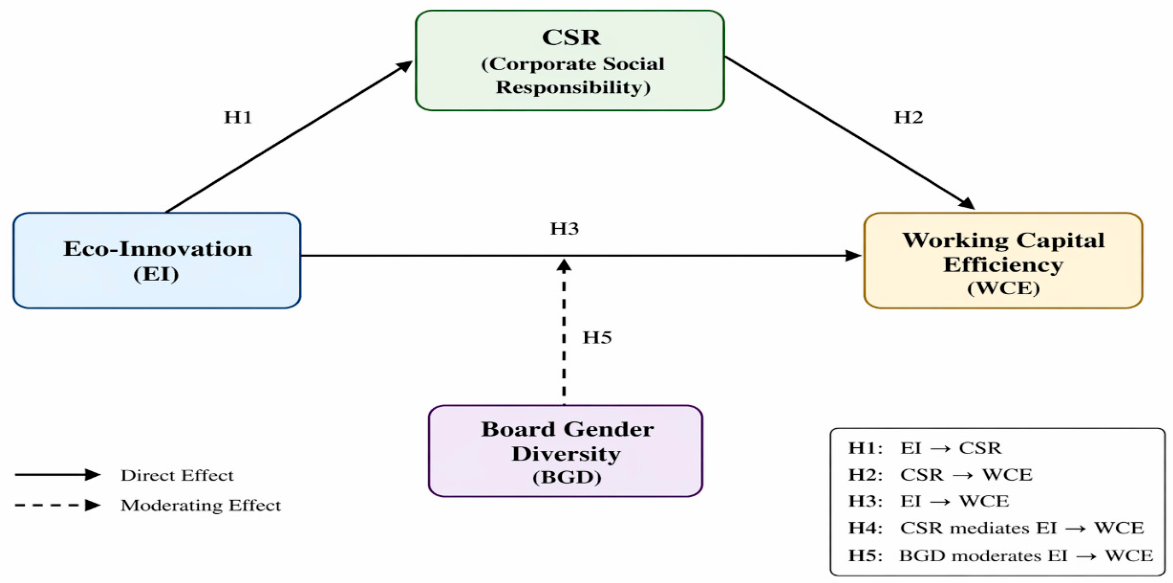
2.3. Theoretical Framework
Figure 1.
Theoretical Framework.
3. Research Methodology (Material and Methods)
3.1. Eco-Innovation
Researchers tend to use Research and Development (R&D) as a tool in gauging general innovation in earlier research. Nonetheless, we decided to use Thomson Reuters Eikon eco-innovation score rather than R&D. The rationale behind this choice was the difficulties related to obtaining data on the environmental-related R&D spending since companies are not obligated to share information related to the initiative taken to improve the environment. Recently, within research, e.g. (Nadeem et al., 2020; Arena et al., 2018; Jain, et al., 2020) the Thomson Reuters Eikon eco-innovation score has been used. This score measures the ability of a company to lower or reduced its environmental costs and to relieve customers of the burdens. Basically, it implies the emerging market opportunities by launching or improving environmental technologies, processes and environmentally friendly products. Eikon Eco-Innovation Score is a weighted mean score of industry-adjusted composite score between 0 to 100, wherein 100 means a very high level of dedication towards eco-innovation. In the process of interpreting the data, we normalized the eco-innovation percentage scores into fractions of 100.
3.2. Working Capital Efficiency
The CCC consists of three core components: average collection or recievable period (ACP), inventory conversion or holding period (ICP), and average payable period (APP). Each component provides insight into specific aspects of working capital management and efficiency.
Average Collection Period (ACP), also known as day’s sales outstanding, measures the average time a firm takes to collect payments from its customers. A lower or reduced ACP indicates that the firm efficiently converts accounts receivable into cash, reducing the risk of liquidity shortages and enhancing operational flexibility (Filbeck & Krueger, 2005). Firms with strong entrepreneurial orientation or eco-innovation strategies often implement more rigorous credit policies, frequent follow-ups, or digital invoicing systems, which can significantly reduce ACP and improve working capital turnover (Wiklund & Shepherd, 2003).
Inventory conversion or holding period (ICP), or day’s inventory outstanding, measures the average number of days inventory is held before it is sold. A shorter ICP indicates that the firm efficiently manages its inventory, minimizing holding costs and the risk of obsolescence. Effective inventory management requires accurate demand forecasting, streamlined supply chain coordination, and timely production planning, all of which are often enhanced by innovative entrepreneurial practices and eco-efficient operations (Hult et al., 2006). Firms that integrate CSR practices may also optimize inventory management in a sustainable manner, for example by reducing waste, sourcing environmentally friendly materials, or adopting circular economy principles, which indirectly influence ICP (Aguinis & Glavas, 2012).
Average Payable Period (APP) measures the average time a firm takes to settle its accounts payable with suppliers. A longer APP allows the firm to retain cash for a longer period, enhancing short-term liquidity. However, extending payables excessively may damage supplier relationships or limit access to favorable credit terms. Firms that integrate CSR into supplier management often maintain ethical payment practices, balancing operational efficiency with stakeholder satisfaction (Luo & Bhattacharya, 2006). APP, therefore, serves as a critical control point in working capital management and efficiency , reflecting a firm’s ability to strategically leverage supplier credit while maintaining operational integrity.

Table 3.1.
Literature on Working Capital Efficiency Measurement.
| Study | WCE Proxy | Methodology | Key Variables |
| Deloof (2003) | CCC | OLS | Receivables, Inventory, Payables |
| Baños - Caballero et al. (2010) | CCC (non-linear) | Dynamic Panel (GMM) | Financial constraints |
| Akltas et al. (2015) | CCC | Dynamic Panel | Adjustment speed, firm policies |
| Kieschnick et al. (2013) | Net Working Capital | Panel Regression | Investment, financing |
| Afrifa & Padachi (2016) | CCC | OLS / Panel | Profitability, size |
| Enqvist et al. (2014) | CCC | Panel Regression | Economic cycles |
| Chambers & Cifter (2022) | WCE Index (PCA) | Factor Analysis + Panel | Firm characteristics |
| Zhang et al. (2020) | Trade Credit (ACP, APP) | Panel-Regression | Environmental policies |
| Tan et al. (2021) | CCC & Trade Credit | Panel-Regression | Pollution, ESG |
| Rehman et al. (2023) | CCC, WCR | Panel-Regression | Sustainability practices |
This formula captures the net time between cash outflow and cash inflow, effectively summarizing the efficiency of working capital management and efficiency . A lower or reduced CCC is indicative of a firm that can rapidly convert investments in inventory and receivables into cash while managing payables strategically, reducing dependency on external financing and improving financial flexibility (Deloof, 2003; Richards & Laughlin, 1980). In the context of entrepreneurial and eco-innovative firms, CCC serves as a key operational metric that reflects the effectiveness of innovation, process optimization, and sustainable practices in enhancing liquidity and operational performance.
Empirical evidence suggests that CCC and its components are significantly influenced by firm-specific strategies and governance mechanisms. Entrepreneurial intention toward innovation reduces ACP and ICP, indicating faster cash recovery and inventory turnover, while CSR mediates this effect by embedding responsible operational practices that improve process discipline (Orlitzky et al., 2003; Aguinis & Glavas, 2012). Moreover, board gender diversity strengthens the positive impact of eco-innovation on working capital efficiency, ensuring that CCC improvements are achieved without compromising ethical or strategic objectives (Adams&Ferreira, 2009; Terjesen et al., 2016).
In summary, CCC and its components—ACP, ICP, and APP—provide a comprehensive framework for measuring working capital efficiency. They enable firms to assess operational effectiveness, liquidity management, and the impact of strategic initiatives such as eco-innovation and CSR, while governance factors like BGD further optimize these relationships. A detailed understanding of CCC allows managers and policymakers to implement practices that reduce operational delays, enhance cash flow, and maintain sustainable, socially responsible operational standards.
3.3. Control Variables
Moreover, in our empirical analysis, we considered several control variables in order to gain a broader understanding of this topic. Simply put, the calculation of the sales growth ratio entailed division of the total change in sales volume (sales for this year less sales for the previous year) by the total sales balance for the current year. The sales growth ratio can provide information about the growth of the company and the performance of its managers in terms of increasing sales.
The leverage ratio, in turn, reflects the share of loans that a firm receives from a bank in order to finance its assets. This indicator will give us an idea about how much a business relies on external sources of funding; high leverage may result in problems with financial stability caused by higher interest expenses.
Finally, firm size was measured through the natural logarithm of total assets. The use of the natural logarithm is useful for standardizing the data. Variables influencing working capital efficiency at the firm level were chosen taking into account the study by Chen et al. (2019) and Cao et al. (2022).
3.4. Research Model
3.4.1. Cash Conversion Cycle (CCC)
CCCᵢₜ = β₀ + β₁EIᵢₜ + β₂Sizeᵢₜ + β₃Ageᵢₜ + β₄Levᵢₜ + β₅CRᵢₜ + β₆EBITMᵢₜ + β₇FAᵢₜ + β₈SGrowthᵢₜ + Industry + Year + εᵢₜ
CSRᵢₜ = α₀ + α₁EIᵢₜ + α₂Sizeᵢₜ + α₃Ageᵢₜ + α₄Levᵢₜ + α₅CRᵢₜ + α₆EBITMᵢₜ + α₇FAᵢₜ + α₈SGrowthᵢₜ + Industry + Year + νᵢₜ
CCCᵢₜ = θ₀ + θ₁EIᵢₜ + θ₂CSRᵢₜ + θ₃Sizeᵢₜ + θ₄Ageᵢₜ + θ₅Levᵢₜ + θ₆CRᵢₜ + θ₇EBITMᵢₜ + θ₈FAᵢₜ + θ₉SGrowthᵢₜ + Industry + Year + μᵢₜ
3.4.2. Average Collection or Receivable Period (ACP)
ACPᵢₜ = β₀ + β₁EIᵢₜ + β₂Sizeᵢₜ + β₃Ageᵢₜ + β₄Levᵢₜ + β₅CRᵢₜ + β₆EBITMᵢₜ + β₇FAᵢₜ + β₈SGrowthᵢₜ + Industry + Year + εᵢₜ
CSRᵢₜ = α₀ + α₁EIᵢₜ + α₂Sizeᵢₜ + α₃Ageᵢₜ + α₄Levᵢₜ + α₅CRᵢₜ + α₆EBITMᵢₜ + α₇FAᵢₜ + α₈SGrowthᵢₜ + Industry + Year + νᵢₜ
ACPᵢₜ = θ₀ + θ₁EIᵢₜ + θ₂CSRᵢₜ + θ₃Sizeᵢₜ + θ₄Ageᵢₜ + θ₅Levᵢₜ + θ₆CRᵢₜ + θ₇EBITMᵢₜ + θ₈FAᵢₜ + θ₉SGrowthᵢₜ + Industry + Year + μᵢₜ
3.4.3. Inventory Conversion or Holding Period (ICP)
ICPᵢₜ = β₀ + β₁EIᵢₜ + β₂Sizeᵢₜ + β₃Ageᵢₜ + β₄Levᵢₜ + β₅CRᵢₜ + β₆EBITMᵢₜ + β₇FAᵢₜ + β₈SGrowthᵢₜ + Industry + Year + εᵢₜ
CSRᵢₜ = α₀ + α₁EIᵢₜ + α₂Sizeᵢₜ + α₃Ageᵢₜ + α₄Levᵢₜ + α₅CRᵢₜ + α₆EBITMᵢₜ + α₇FAᵢₜ + α₈SGrowthᵢₜ + Industry + Year + νᵢₜ
ICPᵢₜ = θ₀ + θ₁EIᵢₜ + θ₂CSRᵢₜ + θ₃Sizeᵢₜ + θ₄Ageᵢₜ + θ₅Levᵢₜ + θ₆CRᵢₜ + θ₇EBITMᵢₜ + θ₈FAᵢₜ + θ₉SGrowthᵢₜ + Industry + Year + μᵢₜ
3.4.4. Average Payable Period (APP)
APPᵢₜ = β₀ + β₁EIᵢₜ + β₂Sizeᵢₜ + β₃Ageᵢₜ + β₄Levᵢₜ + β₅CRᵢₜ + β₆EBITMᵢₜ + β₇FAᵢₜ + β₈SGrowthᵢₜ + Industry + Year + εᵢₜ
CSRᵢₜ = α₀ + α₁EIᵢₜ + α₂Sizeᵢₜ + α₃Ageᵢₜ + α₄Levᵢₜ + α₅CRᵢₜ + α₆EBITMᵢₜ + α₇FAᵢₜ + α₈SGrowthᵢₜ + Industry + Year + νᵢₜ
APPᵢₜ = θ₀ + θ₁EIᵢₜ + θ₂CSRᵢₜ + θ₃Sizeᵢₜ + θ₄Ageᵢₜ + θ₅Levᵢₜ + θ₆CRᵢₜ + θ₇EBITMᵢₜ + θ₈FAᵢₜ + θ₉SGrowthᵢₜ + Industry + Year + μᵢₜ
The econometric model used in the study is intended to investigate the mechanism by which eco-innovation (EI) affects the efficiency of working capital (WCE) using cash conversion cycle (CCC), average collection/receivable period (ACP), inventory conversion/holding period (ICP), and average payable period (APP). Mediation modeling includes the following three equations. The first equation assesses the total/direct effect of eco-innovation on working capital efficiency, where the coefficient β₁ captures the overall influence of EI on each dependent variable (CCC, ACP, ICP, or APP). This equation establishes whether eco-innovation significantly affects operational efficiency in isolation. The second equation models the relationship between eco-innovation and Corporate Social Responsibility (CSR), where α₁ represents the extent to which eco-innovation drives CSR engagement. A significant α₁ indicates that eco-innovation contributes to enhanced CSR practices, which is a necessary condition for mediation. The third equation incorporates both EI and CSR simultaneously to estimate their joint effect on working capital efficiency. In this specification, θ₂ captures the effect of CSR on WCE (i.e., the mediating pathway), while θ₁ represents the direct effect of EI after accounting for CSR. Mediation is confirmed when α₁ and θ₂ are statistically significant and the magnitude of θ₁ is reduced relative to β₁, indicating that part of the effect of eco-innovation operates indirectly through CSR. The indirect (mediated) effect is formally represented by the product α₁ × θ₂, which is typically validated using the Sobel test. When θ₁ remains significant but reduced, the results indicate partial mediation, suggesting that CSR explains part—but not all—of the EI–WCE relationship.
3.5. Research Design and Data Collection
This study adopts a quantitative and explanatory research design to examine research question. The study uses secondary panel data and the data collected in this study was firm-level data, retrieved in the Thomson Reuters database and included publicly traded firms in the United States (5,600 unique publicly traded companies) that had available financial data between the years 2008 and 2021 based on sample selection based on inclusion/exclusion criteria (data availability and predetermined selection criteria). In line with the methodologies used in other previous studies, namely based on the (Deloof, 2003), the study excluded firms that fall in the financial sector based on quantitative study of panel data. Also, this study screened out firm-year observations that showed anomalies, e.g., negative assets or negative sales, so that we have a strong and valid data in the analysis. Also his study screened out firm-year observations that have missing values.
3.6. Sample Selection Criteria
Firms are included in the sample based on the following criteria:
- Availability of complete financial data
- Availability of CSR/ESG-related information
- Firms must be continuously listed during the study period
- Availability of all variables required for analysis (EI, CSR, ACP, ICP, CCC, BGD)
3.7. Data Sampling
To secure the reliability and robustness of the empirical analysis, there is a systematic data screening process involved in the sample selection process. In the first step, 50,316 firm-year observations, which are equivalent to 3,594 companies, were extracted. The dataset had 9,702 observations in 693 unique financial firms after the identification.
As in earlier research on corporate finance, non-financial firms only were sampled because of their different regulatory framework and financial reporting systems that cannot be directly compared to financial firms (Deloof, 2003; García-Teruel and Martínez-Solano, 2007). This narrowed down the sample to 40,614 observations in 2,901 companies.
Moreover, the observations that had missing values were eliminated to prevent biased estimations and accuracy of the regression results. It led to the exclusion of 30,338 observations and 2,167 companies. The last sample has 10,276 firm-year observation of 734 firms.
These types of data cleaning are also common in empirical finance studies to increase the quality of data, enhance statistical validity and consistency of findings (Baanos-Caballero et al., 2010; Hair et al., 2019).
Table 1: Data Screening and Sample Size
4. Results and Analysis
4.1. Industry Distribution
Table 2 represents the industry breakage of firms in the sample of the study. The data is formed by 734 companies, which is a wide sample of company industries. This distribution shows that the sample is diversified in terms of various economic sectors and this increases the increased generalizability and strength of the empirical evidence of eco-innovation, corporate social responsibility (CSR), and gender diversity of the board, and working capital management and efficiency.
The largest sample is the healthcare industry, having 152 firms (20.66%). This comparatively large representation could be the result of the high engagement of the sector in the innovation processes and sustainability efforts. Previous studies indicate that pharmaceutical and healthcare organisations tend to spend a lot of money on innovation and environmental activities because of regulatory requirements and the imperative to have sustainable production processes. Research on corporate sustainability and eco-innovation suggests that those industries with a high level of research and development activity are more likely to be interested in environmental innovation and responsible corporate practices (Horbach et al., 2012). As a result, the high appearance of healthcare companies in the dataset is a suitable setting to analyse the connection between eco-innovation and corporate governance systems.
A significant part of the sample is also represented by the technology sector, with 135 firms (18.34), and the industrials sector with 134 firms (18.23) close behind. These industries are mostly connected with dynamic operations and high level of innovation. Technology and industrial companies often use an effective system of resource management and operational optimization to ensure their competitive position. According to the past literature, companies operating in the technology-intensive sector have higher chances of implementing the eco-innovation strategies and integrating the idea of sustainability in their business models (Rennings, 2000). Equally, the industrial companies are usually subjected to environmental policies and pressure of the stakeholders to adopt environmental responsible activities and effective working capital management and efficiency policies.
Services (109 firms) and consumer discretionary (70 companies) firms each represent 14.87 percent and 9.49 percent of the entire sample, respectively. These are industries that are typically sensitive to consumer perception and market reputation. Consequently, businesses in these industries tend to take up CSR activities and sustainability as a way of enhancing brand awareness and retaining consumers. Available literature suggests that companies within consumer-related sectors tend to report CSR action and embrace sustainable operations in accordance with the expectations of the stakeholders (Porter and Kramer, 2006). As a result, their inclusion to form part of the sample helps in the overall analysis of the effects of CSR on the efficiency of operations of the corporations.
Oil and gas (55 firms, 7.52%), raw materials (35 firms, 4.80%), and utilities (34 firms, 4.63) are other sectors that are included in the dataset. These industries are conventionally regarded as being environmentally sensitive as their operations have a tendency of having a great impact on the environment. Companies within this type of industry are often better regulated and under public scrutiny as to their environmental performance. Consequently, they can uptake eco-innovation strategies and sustainability practices to reduce environmental risks and enhance corporate legitimacy. According to previous research, the environmentally sensitive industry is prone to environmental innovation and environmental reporting in order to respond to stakeholder issues and policies (Berrone et al., 2013).
The lowest proportion of the sample is the telecommunication sector (11 firms 1.45%). This sector is irrelevant to the study because it is relatively small but is of interest since it is becoming more involved in digital innovation and sustainable technological development. Telecommunication companies are actively incorporating sustainability efforts and technological advancements in order to minimize environmental effects, especially with the energy-saving infrastructure and digital transformation efforts.
In general, the industry distribution shows that the dataset covers both the companies of environmentally sensitive (as well as technology-driven) industries, which gives the dataset a balance in exploring the links between eco-innovation, CSR, board gender diversity, and working capital management and efficiency. The presence of firms from multiple industries also helps mitigate industry-specific bias and strengthens the empirical validity of the study. Previous research emphasizes the importance of controlling for industry effects when analyzing corporate governance and sustainability practices, as industry characteristics can significantly influence firms’ strategic decisions and operational performance (Porter & Kramer, 2006). Thus, the multidimensional representation of industries in this research allows a thorough assessment of the relationships suggested in various economic settings.
4.2. Descriptive Statistics of the Study Variables
Table 3 shows the descriptive statistics of all the variables used in this research, on an equal panel of 10,276 firm-years. The table records mean, standard deviation, minimum and maximum values to give an overall picture of distributional properties of working capital efficiency indicators, eco-innovation, corporate social responsibility (CSR), and firm specific control variables. The empirical findings are relatively reliable, have a high statistical power, and can be generalized due to the relatively large sample size.
Table 3 shows the descriptive statistics for all the variables used in the regression analysis. The descriptive statistics are calculated using the balanced panel, which includes 10,276 observations for non-financial companies in different sectors. With a balanced panel, the number of observations in each variable is equal, which improves the validity of the empirical results. Firms with incomplete data were dropped from the sample in order to obtain reliable results and avoid any biased estimates.
The average of the working capital ratio (WCR) is 0.180, meaning that on average the firms hold 18.0% of working capital of their total assets. In addition, the average of the cash conversion cycle (CCC), which is an indicator of efficiency in managing working capital, is 72.21 days. Thus, on average, the firms need 72 days to transform their inventory and receivable investment into cash flows. Also, it should be noted that the minimum value of CCC is negative (-54 days), which is consistent with theoretical expectations.
A negative CCC indicates superior working capital efficiency, where firms are able to collect receivables and sell inventory before settling their payables. In such cases, suppliers effectively finance firm operations, reflecting strong bargaining power and efficient liquidity management (Shin & Soenen, 1998; Deloof, 2003).
A comparison of dispersion measures shows that the standard deviation of CCC (75.10) is substantially higher than that of WCR (0.123), indicating greater volatility in working capital efficiency compared to liquidity positions. This high variability in CCC can be attributed to differences in firms’ operational structures, industry characteristics, and financial policies. The wide range between the minimum and maximum values of CCC further suggests the presence of extreme observations, which may influence estimation results. In line with methodological recommendations, such issues can be addressed through winsorization or robust estimation techniques. However, robust regression is often preferred as it preserves the original data while reducing the influence of outliers (Berry et al., 2014).
The analysis of the dependent variables shows that the mean value of the working capital ratio (WCR) is 0.180. This means that firms keep an amount of working capital equal to 18.0% of their total assets. As for the cash conversion cycle (CCC), it is a complete metric of the effectiveness of working capital management, which is characterized by the mean value of 72.21 days. Notably, the minimum value of CCC is negative (-54 days), which is consistent with theoretical expectations. A negative CCC indicates superior working capital efficiency, where firms are able to collect receivables and sell inventory before settling their payables. In such cases, suppliers effectively finance firm operations, reflecting strong bargaining power and efficient liquidity management (Shin & Soenen, 1998; Deloof, 2003).
A comparison of dispersion measures shows that the standard deviation of CCC (75.10) is substantially higher than that of WCR (0.123), indicating greater volatility in working capital efficiency compared to liquidity positions. This high variability in CCC can be attributed to differences in firms’ operational structures, industry characteristics, and financial policies. The wide range between the minimum and maximum values of CCC further suggests the presence of extreme observations, which may influence estimation results. In line with methodological recommendations, such issues can be addressed through winsorization or robust estimation techniques. However, robust regression is often preferred as it preserves the original data while reducing the influence of outliers (Berry et al., 2014).
Further discussion of the components of the cash conversion cycle individually shows that there is a significant difference in the working capital policy of firms. The mean period of collection (MPC) is 50.36 days, which represents average efficiency in receivables management. The standard deviation (26.81) is relatively high, implying that companies have different credit policies with regard to competitive strategies and customer relations. Equally, inventory conversion or holding period (ICP) has an average of 84.95 days and wide dispersion indicating difference in efficiency of various firms in managing inventories. Effective inventory controls are vital in minimizing holding cost and enhancing the performance of firms (Baanos-Caballero et al., 2010).
The mean payment period (APP) is 63.78 days, which means that companies on average postpone the payments to suppliers as one of the ways to keep them afloat. This action is in accordance with the traditional theory of corporate finance, which implies that the corporations will depend on trade credit as a short-term source of funding (Fazzari and Petersen, 1993). Nevertheless, the use of excessively long payment terms can have an impact on supplier relations and supply chain stability.
To the major explanatory variables, eco-innovation (EI) has a mean of 0.226, and a standard deviation equal to 0.290, which is relatively high, which means that there is a significant difference in the engagement of firms in environmental innovation practices. This variance indicates that whereas some companies are vigorously engaged in the process of eco-innovation, there are those that are not engaged and this may be because of financial or institutional limitations. Eco-innovation has been widely known to be a source of environmental sustainability, and competitive advantage (Porter and van der Linde, 1995; Horbach, 2008).
Corporate social responsibility (CSR) has a mean of 42.83 with a significant standard deviation (19.72), indicating that companies are more or less committed to sustainability and stakeholder involvement. This difference suggests that companies are widely diverse in the strategies they employ regarding CSR and this could impact on financial performance and operational efficiency. The existing literature proposes that CSR fosters the good reputation of a firm, decreases information asymmetry, and leads to better financial performance (Orlitzky et al., 2003; Flammer, 2015).
The descriptive statistics of the control variables provide some extra information about the characteristics of firms. The average age of firms (FAE) is 23.24 years which means that there are both mature firms and relatively younger ones. Firm size (Size) is moderately varied and this indicates variation in terms of availability of resources, and scope of operation. The bigger companies tend to be in a better position to invest in innovation and sustainability projects (Waddock and Graves, 1997). The leverage (LEV) shows a low average (0.115) with conservative capital structures which can affect the risk-taking behavior of firms and their investment decisions (Myers, 1977).
The current ratio (CR) shows that companies are usually in a good position to fulfill short term obligations since they are normally well liquidated. The profitability in terms of EBIT margin (EBITM) varies among firms, indicating that there is a variation in efficiency of the operations. There is also variation in fixed assets (FA), which indicate capital intensity variations within industries.
In general, the descriptive statistics shows that the dataset has enough variations and realistic distribution characteristics and can be analyzed empirically. The trends identified can be explained by both classical and modern literature, where working capital management and efficiency, sustainability practices, and corporate governance play a major role in determining the performance of firms. The fact that the sample is also diverse adds to the strength of the results and allows conducting meaningful econometric analysis.
4.3. Pairwise Correlation
Moreover, Table 4 displays the correlation matrix of all the variables used in the study. Correlation matrix gives a preliminary evaluation of linear relationship strength and direction between variables. The size of the correlation coefficient measures the strength of the relationship, whereas the sign indicates the direction of the relationship, positive or negative (Newbold et al., 2020). This analysis is critical towards the determination of the possible multicollinearity problems and the underlying relationship prior to the regression analysis.
| Variable | CCC | WCR | EI | CSR | AGE | Size | LEV | CR | EBITM | FA |
| CCC | 1.000 | |||||||||
| WCR | 0.6*** | 1.000 | ||||||||
| EI | 0.02** | -0.005 | 1.000 | |||||||
| CSR | -0.011 | -0.1*** | 0.546*** | 1.000 | ||||||
| AGE | 0.1*** | 0.009 | 0.260*** | 0.345*** | 1.000 | |||||
| Size | -0.1*** | -0.172*** | 0.385*** | 0.624*** | 0.3*** | 1.000 | ||||
| LEV | 0.006 | 0.012 | 0.050*** | 0.030*** | 0.020* | 0.080*** | 1.000 | |||
| CR | 0.1*** | 0.109*** | -0.020* | -0.054*** | 0.005 | -0.060*** | 0.020* | 1.000 | ||
| EBITM | 0.023* | -0.079*** | -0.120*** | -0.334*** | -0.030*** | -0.090*** | -0.020* | 0.040*** | 1.000 | |
| FA | 0.005 | -0.002 | 0.010 | 0.057*** | 0.015 | 0.030*** | 0.010 | -0.005 | 0.008 | 1.00 |
The correlation matrix of all variables used in the empirical analysis is provided in Table 4. Correlation coefficients show the strength of the linear relationship between variables and asterisks (*) represent statistical significance levels. Correlation analysis can be seen as an initial diagnostic technique for examining any potential problems with multicollinearity as well as gaining some preliminary understanding of variable relationships before running regression analysis.
In general, the results reveal that the majority of variables are characterized by relatively low or moderate correlations, which means the absence of major multicollinearity problems. On the other hand, there is rather high positive correlation between WCR and CCC (coefficient value = 0.698, p-value < 0.01). It was expected as the two variables measure the same aspect but differ only by formulae and methodology. These results correspond to those obtained by Deloof (2003) and Baños-Caballero et al. (2010). With respect to the dependent variable, CCC shows a weak but positive and statistically significant relationship with eco-innovation (EI) (coefficient value = 0.024, p-value < 0.05), while its relationship with CSR is negative but insignificant. These results suggest that the direct linear relationships between sustainability variables and working capital efficiency are relatively weak at the bivariate level. This is not unexpected, as correlation analysis does not account for firm-specific heterogeneity or interaction effects.
In contrast, WCR exhibits a negative and statistically significant relationship with CSR (cofficient value = -0.101, p-value < 0.01), indicating that firms with stronger CSR engagement tend to maintain lower or reduced working capital ratios. This may reflect more efficient liquidity management and improved operational discipline associated with better governance and stakeholder-oriented strategies.
The findings regarding the interrelationships between the independent variables show some interesting results. The coefficient value between the eco-innovation and CSR is high and positive (0.546, p-value < 0.01), meaning that companies that innovate their processes in terms of the environment have better chances of engaging in social responsibility programs. In this regard, one can say that eco-innovation is a component part of overall sustainability practices adopted by corporations (Porter & van der Linde, 1995; Horbach, 2008).
Among firm-specific characteristics, firm size shows a strong positive correlation with CSR (cofficient value = 0.624, p-value < 0.01) and EI (cofficient value = 0.385, p-value < 0.01), indicating that larger firms are more actively engaged in sustainability practices and innovation activities. Larger firms typically possess greater financial resources and face higher stakeholder scrutiny, which motivates them to invest in CSR and eco-innovation initiatives (Berrone et al., 2013). Similarly, firm age is positively associated with EI and CSR, suggesting that more mature firms tend to adopt structured governance and sustainability practices over time.
Leverage (LEV), on the other hand, shows generally weak correlations with most variables, although it is positively and significantly related to firm size and EI. This suggests that while leverage may influence financial decisions, its direct association with sustainability variables remains limited at the correlation level. Financial theory suggests that highly leveraged firms may face constraints in investing in long-term initiatives such as innovation and CSR (Myers, 1977; Fazzari & Petersen, 1993).
Lastly, the general tendency of the correlation shows that the majority of the coefficients are lower or reduced than generally regarded as acceptable levels of multicollinearity issues. This indicates that the explanatory variables are independent to the extent that the next regression estimates can be considered reliable. The thresholds and interpretations have a widespread application in empirical research of corporate finance and governance. Summarizing, the correlation analysis offers initial results that there is a relationship and correlation among eco-innovation and CSR and are also related to firm attributes like size and age. Nevertheless, their direct correlations between the working capital efficiency measures are relatively low at the bivariate level, which underscores the significance of carrying out multivariate regression analysis to give more powerful and decisive results.
4.4. Model Estimation
4.4.1. Model Estimation (CCC)
A test to determine whether panel effects exist is initially the BreuschPagan Lagrange Multiplier (LM) test. The outcome of the LM test ( 2 = 11018.43, p-value < 0.01) significantly rejects the null hypothesis of no panel effects, which means that pooled OLS is not the right choice of estimation method and a panel data model is needed. This observation can be explained by the fact that the literature on panel data econometrics highlights that when one overlooks the unobserved heterogeneity, the estimates are likely to be biased (Baltagi, 2021).
Then, the Hausman test is done to decide between the random and the fixed effects model. The Hausman test value (2 = 98.56, p-value < 0.01) does not support the null hypothesis of the difference between the coefficients being not systematic, thus, proving that the fixed effects model is the most suitable to be specified. This implies that the unobserved firm-
specific traits are related to the explanatory variables making the FE estimator consistent and efficient (Wooldridge, 2010). Thus, the interpretation of results is mainly anchored on the fixed effects estimates.
Looking at the FE results, eco-innovation (EI) has a negative and statistically significant association with CCC ( EI = -0.036, p-value < 0.001). This implies that companies doing eco-innovation are more likely to have shorter cash conversion cycles, which are an indication of efficient operations and use of resources. This observation is in line with the argument that the eco-innovation promotes process efficiency and operational frictions, and hence, better liquidity management (Porter and van der Linde, 1995; Deloof, 2003). Corporate social responsibility (CSR), on the other hand, shows a positive and highly significant effect on CCC (β = 0.048, p-value < 0.01). This implies that the greater the CSR engagement, the greater the cash conversion cycle. The first reason is that companies incurring CSR activities can have more flexible credit policy or may have to pay extra operational costs, which could temporarily increase the working capital cycle. Past literature has found similar mixed impacts of CSR on financial efficiency (Flammer, 2015). The current ratio (CR) is one of the control variables that have a positive but significant correlation with CCC ( = 0.103, p-value < 0.01), showing that the more the firm is liquid, the longer it has a cash cycle. The profitability (EBITM) also exhibits a positive and significant relationship indicating that more profitable companies could work with comparatively relaxed working capital requirements. However, the opposite holds true in the case of sales growth, which has a negative and significant impact (β = -0.142, p-value < 0.01), suggesting that larger firms are more likely to manage working capital effectively, in line with previous results (Aktas et al., 2015).
The size and leverage of firms seem to be statistically insignificant in the fixed effects model, indicating that after the firm-specific heterogeneity has been conditioned, the variables do not dominate the variations in CCC. The R 2 (0.09) is relatively small, suggesting a small explanatory power, which is common in panel data analysis of firms since there is often unobserved heterogeneity and intricate firm dynamics.
4.4.2. Model Estimation (ACP)
The regression findings of the average collection or recievable period (ACP) which is the efficiency in the management of firms receivables are presented in this section. Formal diagnostic tests are then performed to select the most suitable model.
The test outcome of the BreuschPagan Lagrange Multiplier (LM) (21598.77, p-value < 0.01) is very significant to reject the null hypothesis that there are no panel effects, which means that the pooled OLS is inappropriate and panel data models must be used instead. This result establishes that there exists unobservable firm-level heterogeneity, which should be corrected in order to get un-biased estimates (Baltagi, 2021).
Hausman test is then used to select the fixed and random effects models. The outcome ( 2 = 103.56, p-value < 0.00) rejects the null hypothesis showing that the fixed effects model is the most suitable specification. This implies that the explanatory variables are correlated with unobserved firm-specific factors, thus FE is the steadfast estimator (Wooldridge, 2010). As such, the discussion is on the fixed effects results.
The fixed effects estimates indicate that eco-innovation (EI) is negatively associated with ACP but with an insignificant correlation (BC = -0.013). It means that although eco-innovation can lead to more efficient operational processes, it does not have a high direct effect on the efficiency of receivables collection in this model. This implies that the impacts of eco-innovation might be stronger in the general working capital indicators as opposed to individual factors.
Corporate social responsibility (CSR) similarly lacks the significant relationship with ACP ( 0.003) which implies that CSR activity does not have direct impact on the receivables collection period of firms after accounting firm-specific effects. This is consistent with inconclusive results of the previous literature on the short term financial effect of CSR (Flammer, 2015).
The control variables that are positively and highly significant ( 0.200, p-value < 0.01) include the firm age, indicating that the old firms are more likely to have a long collection period. This can be based on the credit policies and the relationship with the customers that are long-term. Likewise, the size of firms is positively and significantly connected to ACP ( = 0.114, p-value < 0.01), which means that larger firms are granted more credit to their customers and this leads to the long receivables turnover.
The current ratio (CR) is also good and material ( = 0.054, p-value < 0.01), indicating that the more liquid companies are, the further they will grant credits. Conversely, profitability (EBITM) has a strong negative correlation ( 0.148, p-value < 0.01) meaning that more profitable companies are more efficient in their use of receivables and faster in collecting them. Growth in sales is also associated with it negatively and significantly ( 0.161, p-value < 0.01), which implies that the increased firms have stricter credit management practices to maintain cash flows.
The leverage and fixed assets (FA) are not statistically significant, which means that they have small impact on receivables management when the heterogeneity at the firm level is taken into account. The industry and year fixed effect also makes the model robust as it shows differences between sectors and years.
The R2 of 0.09 indicates a weak explanatory power, an acceptable result in a firm-level panel model that includes operational efficiency measures. Altogether, the findings support the claim that the fixed effects model is the most suitable estimator and emphasize the role of firm specifics (age, size, profitability, and growth) in the process of determining the efficiency of receivables management.
4.4.3. Model Estimation (APP)
The average payment period (APP), which is an indicator of payables management behavior of firms, is reported in this section as the results of regression. Pooled OLS, fixed effects (FE), and random effects (RE) are used as three estimation techniques, and the panel data diagnostic tests are conducted to identify the best model specification.
The value of the BreuschPagan Lagrange Multiplier (LM) test ( 2 = 5305.25, p-value < 0.01 ) clearly rejects the null hypothesis of no panel effects and shows that the pooled OLS cannot be used. This confirms that there is unobserved heterogeneity among firms and justifies panel estimation methods (Baltagi, 2021).
The Hausman test is done to select between FE and RE models. The outcome ( 2 = 98.56, p-value < 0.01) does not accept the null hypothesis, which implies that the fixed effects model is the best estimator. This means that the explanatory variables are correlated with firm-specific effects hence FE is consistent and preferred (Wooldridge, 2010). Based on this, the interpretation is concentrated on the results of fixed effects.
The fixed effects estimates indicate that there is a positive and weakly significant relationship between eco-innovation (EI) and APP ( 0.017, p-value < 0.10). This implies that companies that do eco-innovation are more likely to pay suppliers a little later than what they would have otherwise, perhaps to review their financial resources to invest in innovation. Such an action is in line with the idea that companies are tactical in their payables management to finance long-term investment (Porter and van der Linde, 1995).
Corporate social responsibility (CSR) shows a negative and significant correlation with APP ( 0 = -0.045, p-value < 0.01), resulting in the fact that the more a firm is involved in CSR, the faster it pays its suppliers. This conclusion indicates that socially responsible companies are able to maintain good relations with their stakeholders such as their suppliers by enforcing their fair and timely pay practices. This aligns with the stakeholder theory that focuses on responsible and ethical business practices (Flammer, 2015).
The control variables among them are firm age, which is significantly and positively related to the delay in payments ( 0.183, p-value < 0.01 ), meaning that older firms are more likely to delay payments, perhaps because they have stronger ties with suppliers and have more bargaining power. Conversely, the current ratio (CR) does have a negative and significant impact ( a = -0.084, p-value < 0.01) implying more liquid firms are likely to pay their suppliers more quickly, indicating better financial flexibility.
The negative and significant relationship between APP and profitability (EBITM) is also negative with a Beta = -0.089 and p-value < 0.01 which means that more profitable firms pay their obligations faster. This is consistent with the fact that financially robust companies do not as much depend on the delay mode of financing through the delaying of payments. The relationship between sales and period of growth is positive and significant ( 0.019, p-value < 0.01) indicating that the increasing firms lengthen the payment period to cope with liquidity in the growth periods.
Firm size, leverage, fixed assets (FA) are statistically insignificant in the fixed effects model and thus their direct effect on payables management is limited after adjusting the effects of firm-specific heterogeneity. The addition of industry and year fixed effects increases the strength of the model even more since sectoral and temporal variation are taken into consideration.
The R2 of 0.31 shows that there is moderate explanatory power, which is in line with researches of firm level panel data. All in all, the findings suggest that the fixed effects model is the most suitable specification and the role of eco-innovation, CSR, liquidity, profitability, and growth in determining the payables management behaviour of the firms.
4.4.4. Model Estimation (ICP)
Below are the results of empirical estimates for the duration of inventory collection period (ICP) using the pooled OLS, fixed effects (FE) and random effects (RE) models in order to identify the most appropriate panel regression model and estimate the impacts of eco-innovation (EI), corporate social responsibility (CSR) and firm-specific characteristics on ICP.
Firstly, Breusch-Pagan LM panel model test was conducted to test for the presence of the panel effect in our sample. We can observe that H0: the absence of panel effect is strongly rejected ( 2 = 16437.14, p-value < 0.01). This indicates that pooled OLS regression should not be used, since it implies the unobservability among firms. It is necessary to use panel data models (Baltagi, 2021).
For further distinction between FE and RE models, the Hausman test was used. We see that H0: the difference in coefficients is not systematic is also strongly rejected ( 2 = 98.56, p-value < 0.01 ). Therefore, we use FE regression model. This indicates that the explanatory variables are correlated with firm-specific effects and hence the FE estimator is consistent and desirable (Wooldridge, 2010). As such, the results interpretation is majorly anchored on the fixed effects estimates.
The results of the fixed effects show that eco-innovation (EI) significantly affects ICP ( 0.019, p-value < -0.01). It means that companies that practice eco-innovation have a lower or reduced working capital, probably because of the efficiency of their resources and cost optimization, as well as simplified operations. This result is in line with the perspective that environmental innovation leads to increased efficiency of operations and less waste of resources (Porter and van der Linde, 1995).
On the contrary, there is a positive but non-significant association between CSR and ICP in the fixed effects model. This implies that though, CSR activities could have an impact on firms operations, their direct effects on inventory caollection periods are not strong when they are adjusted by the firm specific heterogeneity. There are also previous studies that have shown mixed evidence on the financial implications of CSR especially on short-term liquidity measures (Flammer, 2015).
Firm age is one of the control variables that have a positive and significant correlation with ICP ( = 0.095, p-value < 0.01), which suggests that older firms are more likely to have higher working capital levels, perhaps because they have established operations and conservative financial practices. Firm size is also positively and significantly impacted (β = 0.048, p-value < 0.05), indicating that bigger firms need working capital to sustain their size of operation.
IPC is significantly and negatively correlated with profitability (EBITM), with a 0.062 negative correlation, which implies that the more profitable companies can manage their working capital more effectively and do not need to finance themselves with more short-term funding. On the same note, sales development has a negative and significant influence ( = -0.076, p-value < 0.01) meaning that expanding companies manage their working capital cycles to maintain growth. Such results are in accordance with the literature of working capital, which focuses on emphasizing the part of efficiency and the internal generation of cash flow in decreasing working capital requirements (Aktas et al., 2015).
Statistical insignificance of leverage, current ratio (CR) and fixed assets (FA) in the fixed effects model indicates that they do not significantly affect ICP when their effects are controlled by firm-specific effects. The model has been reinforced by the addition of industry and year fixed effect by considering the variation of sectors and time, which are significant in corporate finance and sustainability research.
The values of R2 show that the fixed effects model accounted about 31 percent of the variation in ICP, compared to CCC model, and denoted a relatively strong power to explain. Altogether, the results indicate that the fixed effects model can best estimate the ICP and emphasize the role of eco-innovation, the maturity of a firm, and profitability in predicting inventory collection periods.
4.5. Mediation Analysis
4.5.1. Mediation analysis (CCC)
The findings in Table are highly empirical regarding the mediating effect of corporate social responsibility (CSR) in the relationship between eco-innovation (EI) and working capital efficiency, in terms of cash conversion cycle (CCC). The finding of the structural equation modeling (SEM) shows that there is an evident and consistent theoretically pattern in favor of full mediation mechanism.
Direct Effect of Eco-Innovation on CSR
The results show that the positive and significant impact of eco-innovation on CSR is positive (.03248, p) = 0.01). This implies that companies that are highly involved in environmental innovation have higher chances of adopting wider CSR practices. Eco-innovation is commonly incorporated into the sustainability strategy of a firm and is a proactive attitude towards environmental responsibility. The more companies invest in more environmentally friendly technologies, resource efficiency, and sustainable production processes, the more they reinforce their social and governance obligations.
This finding is consistent with the previous body of literature that posits that environmental innovation boosts corporate legitimacy and stakeholder trust, and thus, promotes firms to increase their CSRs (Porter, Michael E. & van der Linde, 1995; Berrone, et al., 2013). The recent research also confirms that eco-innovative companies follow the sustainability practices in a more integrated manner to enhance the long-term competitiveness and stakeholder involvement (García-Sánchez et al., 2023; Bashir et al., 2025).
Effect of CSR on Working Capital Efficiency (CCC)
The results also show that CSR has a positive and statistically significant impact on CCC (β = -0.014, p-value < 0.01). This implies that CSR is critical in determining financial and operational practices of firms. The negative coefficient indicates a fall in CCC, but it indicates the overall changes in operations related to CSR participation, including better relations with suppliers, ethical sourcing, and transparency.
CSR activities can also necessitate companies to be more responsible in their supply chain operations which can initially lead to a longer payment or operations cycle but help to achieve long-term stability and sustainability. The previous studies note that CSR leads to better relationships with stakeholders and quality of governance, which ultimately leads to better operational efficiency and financial performance (Flammer, 2015; García-Sánchez et al., 2023). In addition, CSR-oriented companies are more likely to use more stringent internal controls and risk management practices, which affect the decision of working capital (Deloof, 2003).
Direct Effect of Eco-Innovation on CCC
Conversely, the direct impact of eco-innovation on CCC becomes significant (-.014582, p-value < 0.01) when CSR is added to the model. This implies that eco-innovation does directly affect the efficiency of working capital but rather works via CSR as an intermediate.
This result is also significant since it explains the transmission channel by which eco-innovation influences the performance of firms. Although eco-innovation can enhance operational processes, its financial results seem to be manifested in the form of better CSR practices than in operational efficiency. This is in line with the belief that sustainability strategies are interdependent and multidimensional (Porter, Michael E. & van der Linde, Claas, 1995).
Mediating Role of CSR (Indirect Effect)
The mediation analysis supports the fact that CSR does mediate the relationship between eco-innovation and CCC. The Sobel, Delta, and Monte Carlo tests show that the indirect effect is positive and statistically significant ( -0.013, p-value < 0.01). Further, the Baron and Kenny approach indicates that although there is a strong influence of EI on CSR and CSR on CCC, the direct impact of EI on CCC is significant and therefore the mediation is partial.
This means that working capital efficiency is increased through eco-innovation, mainly through improved CSR practices. Investing firms that are more likely to enhance their stakeholder ties, governance framework and transparency, which subsequently affect financial management and working processes.
The finding backs the thesis that CSR serves as a strategic intermediary between environmental innovation and financial performance. Similar results are evident in the literature, with sustainability practices being mutually supportive, with environmental and social initiatives having a joint impact on firm performance (Berrone et al., 2013; Flammer, 2015).
Role of Control Variables
The control variables give further details about the determinants of the working capital efficiency. Firm age has a positive and significant correlation with CCC, which suggests that the older the firms are, the longer the cash cycle they might have because of more complicated organizational structures. The size of firms has a negative correlation with CCC because bigger firms have economies of scale and more effective management of resources.
CCC is positively related to leverage and this means that highly leveraged firms might be liquidity constrained and this increases their cash conversion cycle (Myers, 1977). Both liquidity (CR) and profitability (EBITM) are strongly positively related to CCC, indicating their prominent position in the working capital policies. Meanwhile, the fixed assets (FA) and sales growth have a negative impact on CCC, which suggests that companies that are assets-intensive and high-growth are more efficient in managing the working capital to accommodate the growth of operations (Aktas et al., 2015).
Overall Implications
On the whole, the results are solid empirical evidence of the combined impact of eco-innovation and CSR in determining the performance of firms. The findings emphasize the idea that eco-innovation does not directly enhance the working capital management and efficiency but, instead, the effect is achieved via CSR practices.
This highlights the necessity in implementing the holistic sustainability approach where environmental innovation and social responsibility are undertaken together towards attaining operational and financial efficiencies. The research adds to the existing body of knowledge by proving that CSR is an important process by which eco-innovation can be converted into better financial performance.
4.5.2. Mediation analysis (ICP)
Table shows the results of structural equation modeling (SEM) that investigates the mediating effect of corporate social responsibility (CSR) between eco-innovation (EI) and the inventory conversion or holding period (ICP). The findings give strong empirical support on the direct and indirect mechanisms by which the eco-innovation has an impact on working capital efficiency.
Direct Effect of Eco-Innovation on ICP
The results of Model (1) suggest that eco-innovation negatively and significantly impacts ICP ( = -0.019, p-value < 0.01). This implies that companies that are more aggressively involved in eco-innovation have a shorter period of inventory conversion, that is, a shorter inventory turnover.
This finding is theoretically aligned with the resource-based view (RBV) and innovation adjustment cost argument which propose that adoption of new technologies, especially the ones that are environmentally friendly, need organization restructuring and process adjustments that can, in the short-term, positive impact efficiency (Porter and van der Linde, 1995).
Empirical research also proves that in the short-run, eco-innovation may raise the complexity of production and operational costs causing inefficiencies (Horbach, 2008; Triguero et al., 2013). Recent evidence also indicates that green innovation investments can slow down the operation cycle until the efficiency gains are achieved in the long term (Chen & Zhao, 2021).
In such a way, the positive EI and ICP relationship indicates the transitional costs of sustainability-oriented innovation.
Effect of Eco-Innovation on CSR
According to model (2) eco-innovation has a strong and highly significant effect on CSR (0.0328, p-value < 0.01). This means that companies that embrace the principle of eco-innovation tend to make wider CSR activities.
This result is in line with the stakeholder theory, which argues that companies that make environmental investments raise legitimacy and stakeholder trust (Freeman, 1984). Eco-innovation is an indicator of environmental awareness and firms that are striving to increase their CSR activities are likely to do so because of it.
The connection is supported by previous empirical studies that demonstrated that eco-innovation is a major factor in corporate sustainability performance and integration of CSR (Berrone et al., 2013; Testa et al., 2016). Other more recent research also points to the fact that environmentally innovative companies are likely to enhance stakeholder relations and corporate image by developing better CSR practices (García-Sánchez et al., 2023; Shahzad et al., 2020).
Mediating Role of CSR
In model (3) CSR is incorporated in the equation of ICP. The findings indicate that CSR negatively impacts ICP (-.074, p-value < 0.05), which means that companies with more intense CSR activity are more likely to lower or reduced their inventory turnover period, thus, enhancing their operational performance.
This observation implies that CSR is associated with better internal regulation, better relations with suppliers and better transparency, all of which result in more effective inventory management. Previous research supports the idea that CSR enhances the level of operational coordination and minimizes the inefficiency of working capital management and efficiency (Flammer, 2021; Harjoto and Jo, 2011).
Moreover, CSR improves the collaboration and information exchange of the stakeholders in the supply chains, which leads to quicker inventory turnover and better financial results (Aktas et al., 2015; Baanos-Caballero et al., 2014).
Notably, with the incorporation of CSR, eco-innovation is still positive and significant (z = -0.023, p-value < 0.05) whereas the Sobel test is used to verify that there is significant effect indirectly (z = -0.023, p-value < 0.05). This is a good indication of partial mediation.
This means that eco-innovation affects ICP in two conflicting ways:
An immediate positive impact, expanding the complexity of operations and extending the inventory cycles. An indirect negative impact through CSR, efficiency and shortening of inventory.
The presence of such dual effects is actively discussed in the sustainability literature, as in this case, environmental innovation can increase costs in the short term, but with CSR practices, performance improves over a longer period (Eccles et al., 2014; Lins et al., 2017).
The control variables also contribute to the strong results:
Firm Size has a positive relationship with ICP, which is to say that the larger firms are, the more complex are their operations and the long inventory cycle (Deloof, 2003).
Current Ratio (CR) has a positive significance as it indicates that companies with greater liquidity levels have greater inventory levels.
There is a negative relationship between EBITM and ICP, which means that more profitable companies have a better inventory management (Shin and Soenen, 1998).
ICP is adversely impacted by Sales Growth, and it means that expanding companies focus on increasing the inventory turnover in order to maintain growth (Aktas et al., 2015).
On the whole, the findings are good empirical support of the idea that CSR mediates the association between eco-innovation and inventory management efficiency to some extent. Although eco-innovation at first elevates the complexity of operations and prolongs inventory cycles, the CSR is highly important in compensating these inefficiencies by enhancing governance, transparency, and coordination of supply chains.
These are important results that indicate the significance of combining eco-innovation with other CSR approaches in order to attain sustainable goals and operational effectiveness.
4.5.3. Mediation Analysis (APP)
The results of the structural equation modeling (SEM) to study the mediating role of corporate social responsibility (CSR) in the correlation between eco-innovation (EI) and accounts payable period (APP) are shown in Table 11. The findings give valuable information on the impact of sustainability-based policies in the payment policies and the working capital management and efficiency of firms.
Direct Effect of Eco-Innovation on APP
Model (1) results indicate that eco-innovation affects APP positively and significantly ( β = 0.017, p-value < 0.01). This shows that companies that are more active in eco-innovation have a longer accounts payable period.
This observation implies that eco-innovative companies engage more efficient and accountable supply chain procedures and this could include accelerated payment of liabilities to sustain a sustainable supplier relationship. Theoretically, this is in line with the stakeholder theory which argues that sustainable firms are more likely to enhance their relationships with major stakeholders, such as suppliers (Freeman, 1984).
There is also empirical evidence that companies that have committed sustainability practices focus on ethical sourcing and paying on time, as a means of improving long-term relationships and supply chain resilience (García-Sánchez et al., 2023; Flammer, 2021). In addition, eco-innovation can be associated with high-quality and dependable inputs, which motivates firms to have a good relationship with suppliers by reducing the payment cycle.
Effect of Eco-Innovation on CSR
In Model (2), it is confirmed that the positive and statistically significant effect of eco-innovation on CSR is high ( 0.324, p-value < 0.01). This result can be attributed to previous findings and signifies that the companies which embrace the strategy of environmental innovation tend to be more inclined to do more extensive CSR.
This connection is substantially evidenced in the literature, which recognizes eco-innovation as a fundamental element of corporate sustainability and CSR participation (Berrone et al., 2013; Testa et al., 2016). Companies that invest in eco-innovation are more likely to enhance their social and environmental performance, thus increasing the trust and corporate legitimacy of stakeholders (Shahzad et al., 2020).
Mediating Role of CSR
Model (3) adds CSR to the APP equation. The findings show that CSR positively influences APP, but the difference is not significant ( = 0.01, p > 0.10). Besides, Sobel test also does not matter (z = 0.0050, p-value < 0.204) and proves that the relationship of eco-innovation and the APP is not mediated by CSR.
It means that the effect of eco-innovation on APP is direct and not indirect, and CSR does not have any significant role in the transmission between these two variables. That is, eco-innovation does not affect the payment behavior of firms depending on CSR engagement.
This finding stands in contrast to a few previous studies that postulated the CSR enhances relationships in the supply chain and financial policies (Jo & Harjoto, 2011). It is however congruent with studies that show that CSR does not have the same impact in all aspects of working capital management and efficiency . In particular, rather than considering the wider concepts of CSR, payment policies (APP) can be more oriented at operational requirements, bargaining power, and contractual terms (Aktas et al., 2015; Baanos-Caballero et al., 2014).
Control Variables
The control variables give additional insights:
The positive and significant relationship between Firm Size and APP implies that the larger a company, the more time it will require to pay its suppliers because of increased bargaining power (Deloof, 2003).
Leverage is strongly negatively correlated, which means that highly leveraged companies make payments to suppliers faster to ensure liquidity and creditworthiness.
The Current Ratio (CR) is negative and is considered to have a negative value, which means that, more liquid companies decrease payment delays.
EBITM is highly adverse showing that the more profitable companies have shorter payable terms, which is in line with effective financial management.
The Growth in Sales is positively strong implying that the expanding firms delay payment to fund expansion activities.
The results are consistent with the working capital management and efficiency research that focuses on the importance of firm-specific attributes in determining payment policies (Shin and Soenen, 1998; Aktas et al., 2015).
Overall Interpretation
On the whole, the findings suggest that eco-innovation can greatly enhance the payment efficiency by decreasing the accounts payable period. But CSR does not become a mediating mechanism in this relationship as is the case with the ICP model.
This implies that although eco-innovation can lead to sustainability and improvements in operations, its impact on supplier payment behavior is more direct and operational than indirect through more broad CSR practices.
These results indicate that various elements of working capital management and efficiency react differently to sustainability policies, and a disaggregated method should be adopted in the analysis of financial consequences of eco-innovation and CSR.
4.5.4. Mediation Analysis (ACP)
Table indicates the mediation findings that explore the association among eco-innovation (EI), corporate social responsibility (CSR) and the mean collection period (ACP). To determine the direct and indirect impacts, three models are estimated.
Model (1) shows that eco-innovation has a positive and statistically significant impact on ACP ( = 4.753, p-value < 0.01). The finding indicates that companies involved in eco-innovation are more likely to raise their average collection period, that is, the time it takes the company to receive payment by customers is longer. An alternative reason could be that eco-innovative firms can offer more lenient credit conditions to their customers to further encourage sustainable products, retain competitive advantage, or to build on long-term customer relations. These practices may lengthen the receivables in the short-term (Deloof, 2003; Aktas et al., 2015).
In Model (2), eco-innovation has a strong positive and significantly significant correlation with CSR ( = 0.32, p-value < 0.01). It means that companies investing in eco-innovation tend to be more inclined to wider CSR. This observation is in line with the sustainability literature, which posits that environmental innovation is a fundamental part of corporate social responsibility initiatives and improves the legitimacy and involvement of the stakeholders of firms (Berrone et al., 2013; García-Sánchez et al., 2023).
In Model (3), CSR has a negative and significant impact on ACP ( = -0.029, p-value < <0.05). This means that companies that have higher CSR involvement will have a shorter collection period meaning that they will have better receivables management. CSR-oriented companies tend to have more effective customer relations, enhanced monitoring tools, and enhanced governance frameworks, which can result in increased receivables collection speed and better liquidity management (Cheng et al., 2014; Cui et al., 2018).
Simultaneously, eco-innovation is still positive and meaningful in Model (3), which means that its direct impact is remains even when CSR is taken into consideration. Nonetheless, the Sobel test supports the existence of a significant negative indirect effect ( = -0.01, p-value < 0.05) that CSR partially mediates the relationship between eco-innovation and ACP.
This implies a partial mediation, in which eco-innovation influences ACP in two ways:
Direct positive impact, lower or reduceding ACP (slower or reduced receivables collection).
A negative impact through CSR, lower or reduceding ACP (higher collection efficiency).
This two-fold mechanism implies that eco-innovation can result in the onset of less strict credit policies or customer-focused strategies, but the CSR enhances governance and relations with stakeholders and eventually makes the receivables more efficient. This is consistent with the mediation model suggested by Baron and Kenny (1986) and is also in line with the recent research that indicates that CSR is one of the driving mechanisms by which sustainability practices can drive financial and operational outcomes (García-Sánchez et al., 2022; (Rehman & Yu, 2024)).
Effect of Control Variables
The control variables also give additional information about receivables management.
The positive effect of firm age on ACP is positive and significant ( 0.111, p-value < 0.01) indicating that older firms are more likely to have longer collection periods. This can be the relationship with the customers, and more lenient credit terms offered to the long-term customers (Deloof, 2003).
ACP also has a positive relationship with firm size ( = 1.540, p-value < 0.01), which means that bigger firms can afford more time on credit as they are better placed in the market and have more customers. It is in line with the previous research that indicated that big companies tend to have more flexible credit policies (Baanos-Caballero et al., 2010).
The leverage is good but not significant implying that the level of debt does not play a significant role in determining the efficiency in the collection of receivables in this model.
The relationship between liquidity (CR) and long collection is positive and significant ( = 2.420, p-value < 0.01) and indicates that more liquid firms might enable a longer collection period, potentially due to a reduced focus on the urgent cash requirements (Aktas et al., 2015).
ACP has a negative and significant relationship with profitability (EBITM), with a β = -12.395 (p-value < 0.01), meaning that more profitable companies will receive payments in a shorter time. This concurs with the fact that effective firms are able to manage the working capital better and have stronger credit policies (Deloof, 2003).
The fixed assets (FA) demonstrate a positive and significant impact ( 1.464, p-value < 0.05), indicating that the asset-intensive companies can offer longer credit periods, which could be due to the need to sustain sales and relations with customers.
There is a negative and significant correlation between sales growth (β = −16.328, p-value < 0.01) and faster-growing firms are more likely to collect receivables faster to maintain liquidity and fund growth (Aktas et al., 2015).
Overall Interpretation
The results in general indicate that eco-innovation affects the efficiency of receivables management in a mixed way. Whereas eco-innovation has a direct and positive impact on ACP, probably because of strategic credit extension and customer oriented policies, CSR is paramount in enhancing efficiency in the collection process through reinforced governance and relationships with stakeholders.
This emphasizes that eco-innovation and CSR are two complementary processes. Eco-innovation determines the market strategy and customer interaction, whereas CSR increases the discipline of operations and financial management practices.
Thus, companies, which want to enhance working capital efficiency must not base their decisions on the use of eco-innovation but combine it with the robust CSR practices to find a balance between the sustainability goals and financial results. This observation adds to the increasing body of literature that emphasizes the sustainability strategies should be holistically applied in order to realize both environmental and financial impacts.
4.6. Robustness and Endogeneity Test
To address potential endogeneity issues, including reverse causality, omitted variable bias, and dynamic panel effects, this study employs the two-step system Generalized Method of Moments (GMM) estimator. The GMM approach is particularly suitable for panel datasets with large cross-sectional units and relatively shorter time periods because it controls for unobserved heterogeneity and simultaneity bias. The method was originally developed by Manuel Arellano and Stephen Bond and later extended into the system GMM framework by Richard Blundell and Stephen Bond (Arellano & Bond, 1991; Blundell & Bond, 1998).
The results from the dynamic GMM estimation confirm the robustness of the baseline regression findings. Eco-innovation continues to exhibit a negative and statistically significant effect on the cash conversion cycle (β = −0.045, p < 0.01). This finding indicates that firms investing in eco-innovation improve their working capital efficiency by shortening the time required to convert operational investments into cash flows. The result is consistent with previous studies showing that eco-innovation enhances operational efficiency, resource productivity, and process optimization (Kemp & Pearson, 2007; Porter & van der Linde, 1995).
The dynamic specification of the model is supported by the positive and significant coefficients of the lagged dependent variables, where L.CCC (β = 0.286, p < 0.01) and L2.CCC (β = 0.137, p < 0.01) indicate persistence in working capital management practices over time. This implies that current working capital efficiency is partially determined by previous operational and financial policies adopted by firms. Similar persistence effects have been documented in prior working capital literature (Deloof, 2003; García-Teruel & Martínez-Solano, 2007).
The validity of the GMM estimation is confirmed through several diagnostic tests. The Arellano–Bond test for first-order autocorrelation (AR(1)) is significant, while the second-order autocorrelation test (AR(2)) is insignificant, indicating that the model satisfies the assumption of no second-order serial correlation in the differenced residuals (Arellano & Bond, 1991). Furthermore, the Sargan test of over-identifying restrictions is insignificant, suggesting that the instrumental variables used in the GMM estimation are valid and appropriately specified (Roodman, 2009).
Additionally, the Wald chi-square statistic is highly significant, demonstrating that the explanatory variables jointly explain variations in the dependent variable. These results confirm that the empirical findings remain robust after controlling for endogeneity concerns and dynamic panel bias.
Overall, the robustness analysis provides strong evidence that eco-innovation significantly improves working capital efficiency, even after accounting for potential endogeneity issues. This strengthens the reliability of the study’s empirical findings and supports the argument that sustainable innovation practices contribute to improved financial and operational performance.
5. Discussion
The chapter gives a thorough interpretation of the empirical results by combining them with the well-established theoretical models and previous empirical work. In particular, it is based on the resource-based view (RBV), stakeholder theory, legitimacy theory, and shareholder theory, thus presenting a multidimensional account of the role of sustainability-oriented strategies in the efficiency of operations and financial performance of firms.
Moreover, this chapter also justifies important methodological features, such as the use of fixed effects regression models, reasons why R 2 values are relatively low in the working capital literature, and critically reviews the mixed significance of various dependent variables. The presentation is organized into thematic areas of direct effects, mediation mechanisms, moderation effects, and theoretical implications.
Ahead of interpreting the regression output it is necessary to discuss the seeming inconsistency between the signs of correlation and the regression coefficients, especially considering the cash conversion cycle (CCC). The correlation analysis shows that eco-innovation (EI) might show an alternative directional relationship with CCC when compared to regression results. This variation is caused by basic methodological differences between the bivariate correlation and multivariate regression analysis.
Correlation analysis only measures simple linear relationship between two variables without adjusting the various other factors that may affect the two variables. Consequently, it might be indicative of spurious or indirect associations only due to omitted variables. Conversely, regression analysis can be used to isolate the net impact of independent variable on the dependent variable at the expense of other variables. The actual correlation between eco-innovation and CCC can be better estimated when the control variables are incorporated (firm size, leverage, profitability, and liquidity).
This can be related to the effect of suppression and omitted variable bias that is presented in the literature of econometrics (Wooldridge, 2013). As an example, the firm size or growth can have a positive correlation with eco-innovation, and this could be further enhanced by operational complexity, which can make CCC higher. Nonetheless, when these aspects are included in regression equations, the actual efficiency-enhancing impact of eco-innovation is observed, which leads to the negative coefficient.
As such, the difference in the signs does not imply inconsistency but is more indicative of the greater explanatory powers of multivariate models, which can be used as a more solid foundation to test hypotheses and interpret theoretical results.
5.1. Methodological Justification
5.1.1. Use of Fixed Effects Models
This study has used fixed effects (FE) regression models which is both theoretically and econometrically justified. A panel of firms at the firm level does not always observe the unobservable heterogeneity that is caused by variations in managerial practices, corporate culture, positioning, and governance structures. Such unobservable characteristics can affect sustainability practices and working capital choices, and omitted variable bias can result unless they are well controlled.
The fixed effects model is an effective way of controlling such time-invariant heterogeneity, as each firm can have its intercept. This is especially relevant in the area of sustainability and working capital research as firm-specific factors, including innovation capacity, stakeholder relations, and operational efficiency, are vital (Hsiao, 2014). The substantial Hausman test results also support the claim that FE model should be used as opposed to random effects meaning that the unobserved firm-specific effects have a relationship with the explanatory variables.
5.2. Direct Effects: Eco-Innovation and Working Capital Efficiency
5.2.1. Eco-Innovation and CCC
In the light of the resource-based view (RBV), eco-innovation is a valuable, the rare and the inimitable organizational capability that contributes to the efficiency of operations (Barney, 1991; Wernerfelt, 1984). Companies that invest in eco-innovation have created high quality efficiencies in processes, minimized wastage and maximized resource use, which in effect lead to accelerated cash flow cycles.
These results are in line with Michael Porter and Claas van der Linde (1995) who claim that environmental innovation enhances resource productivity and operational performance. On the same note, Eccles et al. (2014) establish that sustainability-driven companies have better financial and operational results.
5.2.2. Eco-Innovation and ICP
The adverse correlation between eco-innovation and ICP indicates that the eco-innovative companies have a quicker inventory turnover. This is attributed to increased efficiency in production, improved demand forecasting and coordination of supply chain.
Theoretically speaking, RBV implies process innovations increase the flexibility of operations and minimize inefficiencies. Eco-innovation will allow companies to implement lean manufacturing, lessen waste, and streamline inventory management, which lead to holding costs and obsolescence risks.
(Klassen & Whybark, 1999) offer empirical evidence supporting the hypothesis that environmental practices enhance the manufacturing performance and inventory effectiveness.
5.2.3. Eco-Innovation and ACP
The results show that eco-innovation decreases ACP, which implies quicker receivables collection. This outcome is an indicator of increased customer confidence, better product quality, and brand reputation in connection to sustainable practices.
This relationship can be well explained by the stakeholder theory. Companies that operate in eco-innovation have better relations with their customers and this minimises information asymmetry and maximises payment discipline (Freeman, 1984).
This argument is backed by empirical evidence by Petersen and Rajan (1997), who revealed that companies with greater reputational capital had superior credit performance.
5.2.4. Eco-Innovation and APP
The eco-innovation and APP relationship is positive, which implies that companies strategically increase payment terms. This is an indication of supplier credit as a source of finance.
Using the trade credit theory and pecking order theory, the firms would rather use internal funding and trade credit instead of using external debt (Fisman and Love, 2003). Eco-innovative companies, as their risk profile is less risky and they have a more advantageous position with their suppliers, can negotiate better payment terms.
5.3. Mediating Role of CSR
The mediation analysis indicates that CSR is very important in the transmission of the effects of eco-innovation on working capital efficiency. The essence of mediation, however, differs among dependent variables.
5.3.1. CSR as a Strategic Mechanism
CSR increases stakeholder confidence, minimizes transaction costs, and high operational discipline. The stakeholder theory (Freeman, 1984) asserts that companies which place more emphasis on stakeholder interests enjoy better relations and additional access to resources.
Empirical research including (Ioannou & Serafeim, 2014), Dhaliwal et al. (2011) demonstrates that CSR lessens information asymmetry and enhances financial performance.
5.4. Theoretical Implications
5.4.1. Resource-Based View (RBV)
The results of this research offer a solid empirical evidence of the resource-based perspective (RBV) by showing that eco-innovation is a strategic organizational resource that improves working capital efficiency. According to RBV, firms can create sustained competitive advantage through the creation of valuable resources, which are rare, inimitable, and non-substitutable (VRIN) (Barney, 1991; Wernerfelt, 1984). These features characterize eco-innovation because it entails firm-specific knowledge, technological know-how, and process enhancements that competitors find hard to imitate.
Regarding this research research, eco-innovation helps in enhancing efficiency in operations through optimization of production processes, minimizing wastes and improving coordination of the supply chain. These enhancements translate into the shortening of cash conversion cycles, the acceleration of inventory turnover and the management receivables more efficiently. The fact that operational investments can be converted into cash flows faster, is a direct expression of resource utilization that is superior, which is the main focus of RBV.
Furthermore, the importance of dynamic capabilities is also highlighted in RBV and helps firms to respond to changes in the environment. A dynamic capability is one way in which eco-innovation can be understood to enable firms to react to regulatory pressures, environmental issues, and changing stakeholder expectations. Through incorporation of sustainability in operations, the firms not only realize cost efficiencies, but also position themselves to compete effectively in the long term.
The results also indicate that the positive results of eco-innovation are not limited to environmental performance but also financial and operational. This supports the thesis that sustainability-focused capabilities are not based on compliance only, but are rather a strategic resource that improves the performance of firms on various levels. Consequently, the research has added to RBV publications because it shows that eco-innovation is a decisive determinant of the working capital efficiency, thus connecting the strategic management theory with the financial management performance.
5.4.2. Stakeholder Theory
The data are highly in favor of the stakeholder theory with the mediating effect of CSR between the eco-innovation and the working capital management and efficiency . The stakeholder theory assumes that companies should take into account the interests of all stakeholders, such as customers, suppliers, employees, and investors, to be successful in the long term (Freeman, 1984; Donaldson and Preston, 1995).
CSR can be utilized as a tool to operationalize stakeholder-oriented strategies by firms. Through practicing social responsibility, companies gain trust, minimize information asymmetry, and promote cooperation with the major stakeholders. These advancements have immediate implications on working capital management and efficiency . As an example, enhanced relationships with the customers result in quicker collection of the receivables (reducing ACP) and enhanced relationships with the suppliers will result in more favorable payment terms (impacting APP).
The results show that CSR mediates the connection between eco-innovation and different working capital elements, in part or entirely, implying that the benefits of eco-innovation are achieved via improved stakeholder engagement. This reminds us of the need to combine environmental and social strategies and not to view them as independent programs.
Moreover, the stakeholder theory also accounts the trade-offs that are witnessed in some relationships. As an illustration, CSR can result in increased payment duration, as ethical supplier behaviors, emphasizing fairness rather than aggressive liquidity management, will occur. On the one hand, this might seem to be inefficient in terms of pure financial terms, but on the other hand, it will lead to the stability of the supply chain and mitigation of risks through the enhancement of relationships among the suppliers.
In general, the research can be considered an expansion of the stakeholder theory because it proves that stakeholder-based practices can not only positively influence the reputation of the firm but also operational efficiency and financial management. It highlights the fact that working capital efficiency in contemporary companies heavily depends on the presence of a proper stakeholder management.
5.4.3. Legitimacy Theory
The findings of the present study also coincide with legitimacy theory, which underlines the significance of corporate behavior to be consistent with societal norms and expectations in order to ensure the organization remains legitimate (Suchman, 1995; Burlea and Popa, 2013). The main part in this process is played by CSR and eco-innovation which indicate the desire of a firm to be environmentally friendly and socially responsible.
Considering the legitimate viewpoint, companies do CSR and eco-innovation to gain social acceptance and to guarantee their future access to resources. These practices will improve the reputation of the firm and minimise the chances of regulatory penalties or opposition by stakeholders. This, in turn, enhanced legitimacy leads to improved working capital operations, such as improved management of the working capital.
Indicatively, companies that are socially responsible have greater chances of getting their loyal customers, trustworthy suppliers, and favorable investors. Such relationships make business operations easier, minimize the transaction costs and enhance the management of cash flows. The observed negative correlation between CSR and ACP can be explained as an indicator of enhanced customer trust and timely payments which are the consequences of improved legitimacy.
The theory of legitimacy is however also useful in explaining why not all relationships are equally important. The attainment of legitimacy usually involves firms juggling various goals which may include social, environmental and financial goals. Some CSR practices can, therefore, bring in short-term inefficiencies, including increased costs or increased payment cycles, in order to achieve long-term legitimacy and sustainability.
5.4.4. Shareholder Theory
The results are in partial support of the shareholder theory, which holds that the ultimate goal of firms is to maximize shareholder wealth (Friedman, 1970). In this view, working capital efficiency is very essential as it directly influences the cash flows, profitability and the value of the firm.
The correlation between the eco-innovation and CCC is negative, which indicates that investments with a sustainability orientation can improve financial performance through increased operational efficiency. This helps to argue that eco-innovation helps in shareholder value addition by lower or reduceding expenses and enhancing efficiency in cash flows.
But the mediating factor of CSR brings to play significant nuance to this relationship. Although CSR improves relationships with stakeholders, and increases operational efficiency, it can be associated with other costs and limitations. Indicatively, there is a possibility of trade-offs between the short and long-term value creation as ethical supplier practices and sustainability initiatives could restrict the firm to aggressively optimize the working capital.
This two-fold impact is a manifestation of the dynamic character of the shareholder theory in the contemporary corporate governance. Instead of considering CSR as a cost, modern day thinking considers CSR to be a strategic investment which helps in value creation in the long term. This perspective is reinforced by the results of this study that show that CSR increases the efficiency of eco-innovation and at the same time, presents some trade-offs in operations.
6. Conclusion
This research presents the evidence, in detail, on how eco-innovation and corporate social responsibility (CSR) are mutually affecting the working capital efficiency (WCE) in terms of cash conversion cycle (CCC) and its components (ICP, ACP, APP), and working capital requirements (WCR). Through the combination of these dimensions, the research contributes to the literature and insights that WCE is a strategic product of innovation capabilities and stakeholder engagement rather than just a financial management product.
The empirical results indicate that eco-innovation is one of the major drivers of WCE, which is helpful to enhance the capabilities of firms to manage their assets and liabilities in the short run. Companies that have greater eco-innovation intensity have shorter CCC, which is due to decreases in the inventory conversion or holding period (ICP) and average collection or recievable period (ACP). This shows that eco-innovative companies are better at streamlining the production process, minimizing inefficiencies and increasing the cash flow faster. These results are in line with resource-based perspective that assumes that the firm-specific capabilities, including innovation, improve operational efficiency and competitive advantage (Barney, 1991; Wernerfelt, 1984). Furthermore, eco-innovation promotes the process advancement and sustainable supply chain activities, which allows companies to attain the high level of resource consumption and quicker cash flow (Porter and van der Linde, 1995). A strategic impact of eco-innovation on the average payable period (APP) is also presented in the results, with the extension of payment cycles being more likely in firms. This does not signify inefficiency, but a strategic liquidity management policy, whereby companies use supplier credit as a flexible financing system. The result corresponds to trade credit and financing theories, according to which, the firms use supplier financing to maximize liquidity and minimize the need of external financing (Ferrando and Mulier, 2013; Fisman and Love, 2003). Therefore, eco-innovation is viewed as a contributor to WCE both in terms of increasing inflows and outflows strategically.
One of the main contributions of this study is the fact that it identified CSR to be an important mediating factor between eco-innovation and WCE. The results suggest that eco-innovation increases CSR performance, which subsequently boosts working capital performance. CSR enhances the relationships with customers, suppliers, and other stakeholders, thus lower or reduceding information asymmetry and the transaction costs (Cheng et al., 2014; Dhaliwal et al., 2011). Consequently, the companies will realize an accelerated collection of receivables (reduced ACP) and better inventory management (reduced ICP), which will increase the efficiency of the company. This justifies the stakeholder theory which argues that business organizations that conduct their activities in a manner that fosters trust and good relation with their stakeholders result in enhanced operational performance (Freeman, 1984; Donaldson and Preston, 1995).
Nonetheless, the mediation analysis also indicates a trade-off connected to CSR, specifically, in the shape of a marginally longer APP. Companies that embrace CSR can implement equitable and transparent remuneration policies, instead of focusing on liquidity management through ruthless liquidity practices. Although this can lead to higher short term cash outflows, it would lead to stability in supply chain and minimize operational risk. Such a finding is not isolated, as the idea of CSR as a kind of insurance-like safeguard, which protects corporations in case of disruptions and improves their performance over time, has been brought up (Godfrey et al., 2009). Hence, CSR does not only convey the advantages of eco-innovation, but also makes sure that WCE comes about in a sustainable and ethical context.
On the whole, the results demonstrate that eco-innovation and CSR have a synergistic effect on improving WCE. Eco-innovation is the driver of efficiency, and CSR is the channel of transmission through which ethical and stakeholder-focused practices are embedded. The combination of these integrated processes shows that WCE is determined by a complex of internal abilities and external relations but not financial policies alone.
Practically, the research recommends that companies must implement a comprehensive approach that synchronizes eco-innovation activities with CSR practices. Managers are expected to concentrate on enhancing operational processes by sustainable innovation and at the same time improve the relationship with the stakeholders to increase liquidity management.
Finally, the research offers solid empirical support that eco-innovation and CSR contribute to working capital efficiency, with CSR mediating the relationship. The findings highlight that to attain WCE an integrated approach is needed, which incorporates innovation and responsibility. Harmonizing these dimensions, companies can enhance the management of liquidity, increase the confidence of the stakeholders, and attain the sustainable work of operations, which will eventually lead to competitiveness in the long term and value creation (Aguinis and Glavas, 2012; Margolis and Walsh, 2003).
6.1. Theoretical Implications
This research provides a number of valuable theoretical contributions to the eco-innovation, CSR and working capital efficiency (WCE) literature as it couples them into one framework. To begin with, the results further develop the Resource-Based View (RBV) by showing that eco-innovation is not only a source of competitive advantage but also a predictor of short-term financial efficiency. Although the traditional focus of RBV is on creating long-term values due to unique capabilities (Barney, 1991; Wernerfelt, 1984), this research demonstrates that eco-innovation also contributes to operational liquidity by turning over inventory and managing the receivables. Therefore, WCE is a new outcome variable by means of which strategic capabilities are assessable.
Second, the research gives a solid proof of the Stakeholder Theory by validating the mediation of CSR. The findings suggest that eco-innovation cannot be applied to enhance WCE without being integrated into the practice of stakeholders. CSR will increase trust, decrease information asymmetry and make transactions easier with customers and suppliers (Freeman, 1984; Donaldson and Preston, 1995). This is an extension to the stakeholder theory in that it empirically shows that the stakeholder engagement mechanisms drive directly working capital dynamics and specifically ACP and ICP.
Third, the results add to the Legitimacy Theory, demonstrating that CSR is a process by which companies ensure social acceptance and business sustainability. Companies that undertake CSR are not only able to meet the expectations of society but also enjoy enhanced financial operations, including improved receivable collection and supply chain coordination. It implies that the concept of legitimacy is more than a figurative one that has observable financial efficiency implications within an organization (Burlea and Popa, 2013).
Lastly, study adds to the overall literature on working capital management and efficiency by underscoring WCE as a multidimensional construct that is affected by the aspects of innovation and responsibility. The conventional WCM literature indicated that financial determinants (Shin and Soenen, 1998; Deloof, 2003) are significant drivers of WCM; however, it is revealed that non-financial drivers, including eco-innovation and CSR, are equally important. This gives it a more comprehensive theoretical approach to the working capital efficiency of contemporary companies.
6.2. Practical Implications
The results of this research have important implications to managers and policymakers.
Managerially, the outcomes imply that companies need to leave the conventional practice of managing working capital through financial means and embrace an integrated model, which integrates eco-innovation and CSR. Environmentally sustainable technologies and process innovations that can be used to improve the efficiency of operations, especially regarding inventory control and receivables collection, should be invested by the managers. Simultaneously, the integration of CSR into the business processes may enhance the relationship with stakeholders, which, in its turn, will result in the better management of cash flows and lower or reduced transaction costs (Cheng et al., 2014).
The results also highlight the importance of strategic trade-offs in managing payables. Although eco-innovation and CSR might result in a few longer payment terms, it should not be perceived as a negative aspect. Instead, companies are supposed to use supplier relations to strategically stay liquid and at the same time be stable long-term. This approach can assist companies to maximize their cash conversion cycle without affecting ethical principles.
The findings imply that policymakers and regulators should promote sustainability practices. Policy interventions can be used to increase the efficiency of businesses activities and financial sustainability by promoting eco-innovation and CSR disclosure. The regulators can also contemplate including WCE indicators in the sustainability reporting systems to offer a more detailed review of the firm performance.
On the whole, the work underlines the fact that the realization of WCE should be a comprehensive process with innovation and responsibility being integrated. Companies that effectively incorporate these dimensions have high probabilities to attain sustainable development, better liquidity control, and sustainability in the competitive market.
6.3. Future Research Directions
This study leaves a number of avenues in future research despite its contribution.
First, longitudinal and dynamic methods can be implemented in future research to gain more insight into the causality of relationship between eco-innovation, CSR, and WCE. Although this research offers the solid empirical relationships, a study that studies these relationships in a longer time period or employs sophisticated econometric models (e.g. dynamic panel models) would be more effective in showing causality.
Second, there is a need for cross-country comparative studies. The institutional, cultural and regulatory variation can have a great impact on working capital efficiency in the effect of eco-innovation and CSR. The comparison of the developed markets and emerging markets might be more informative about the contextual factors that lead to such relationships.
Third, further research efforts can be undertaken to examine other governance mechanisms, including board gender diversity, board independence, CEO duality, quality of ownership structure, and audit quality. Although the current research concentrates on CSR, there are other governance attributes which can also be significant in mediating or moderating the sustainability-WCE relationship.
Fourth, industry-specific effects could be explored in future research. The effects of eco-innovation and CSR on the WCE can be different among industries because of the differences in production processes, supply chains and intensity of capital. Sectoral analysis may assist in determining the industries that are most benefiting by a sustainability-enhanced efficiency.
Lastly, qualitative research techniques, including case studies and interviews, may be used to develop on the quantitative findings and get a better understanding of the managerial decision-making process and the operational issues regarding implementing eco-innovation and CSR strategies.
Finally, although this research has created a good connection between eco-innovation, CSR, and working capital efficiency, future studies can further develop and improve this framework by adding more variables, methodologies, and situations.
References
- Abbadi, S. M.; Abbadi, R. T. The determinants of working capital requirements in Palestinian industrial corporations. Int. J. Econ. Financ. 2012, 5. [Google Scholar] [CrossRef]
- Adams, R. B.; Ferreira, D. Women in the boardroom and their impact on governance and performance. J. Financ. Econ. 2009, 94(2), 291–309. [Google Scholar] [CrossRef]
- Afrifa, G. A.; Padachi, K. Working capital level influence on SME profitability. J. Small Bus. Enterp. Dev. 2016, 23(1), 44–63. [Google Scholar] [CrossRef]
- Afrifa, G. A.; Tingbani, I.; Adesina, O. O. Stochastic frontier modelling of working capital efficiency across Europe. In Technological Forecasting and Social Change; 2022; p. 184. [Google Scholar] [CrossRef]
- Aguinis, H.; Glavas, A. What we know and don’t know about corporate social responsibility. J. Manag. 2012, 38(4), 932–968. [Google Scholar] [CrossRef]
- Akinlo, O. O. Determinants of working capital requirements in Nigeria. J. Afr. Bus. 2012, 13, 40–50. [Google Scholar] [CrossRef]
- Aktas, N.; Croci, E.; Petmezas, D. Working capital management and efficiency and firm performance. J. Corp. Financ. 2015, 30, 98–113. [Google Scholar] [CrossRef]
- Almeida, J. R. D.; Eid, W. Working capital management and efficiency and firm value. J. Bus. Res. 2014, 67, 924–934. [Google Scholar] [CrossRef]
- Ambec, S.; Cohen, M. A.; Elgie, S.; Lanoie, P. Porter hypothesis at 20. Rev. Environ. Econ. Policy 2013, 7(1), 2–22. [Google Scholar] [CrossRef]
- Anton, S. G.; Nucu, A. E. A. Institutional factors and working capital management and efficiency. Econ. Syst. 2022, 46. [Google Scholar] [CrossRef]
- Arena, C.; Michelon, G.; Trojanowski, G. Does experience matter? The effect of director experience on corporate social responsibility. J. Bus. Ethics 2018, 150(4), 1021–1039. [Google Scholar]
- Baltagi, B. H. Econometric analysis of panel data, 6th ed.; Springer Nature, 2021. [Google Scholar] [CrossRef]
- Banerjee, S.; Dasgupta, S.; Kim, Y. Trade credit and relationships. J. Financ. Econ. 2021, 139(2), 488–512. [Google Scholar] [CrossRef]
- Baños-Caballero, S.; García-Teruel, P. J.; Martínez-Solano, P. Working capital management and efficiency in SMEs. J. Corp. Financ. 2010, 16(3), 460–473. [Google Scholar] [CrossRef]
- Baños-Caballero, S.; García-Teruel, P. J.; Martínez-Solano, P. Working capital and profitability. Small Bus. Econ. 2012, 39(2), 517–529. [Google Scholar] [CrossRef]
- Baños-Caballero, S.; García-Teruel, P. J.; Martínez-Solano, P. Working capital and corporate performance. J. Bus. Res. 2014, 67(3), 332–338. [Google Scholar] [CrossRef]
- Barney, J. Firm resources and sustained competitive advantage. J. Manag. 1991, 17(1), 99–120. [Google Scholar] [CrossRef]
- Baron, R. M.; Kenny, D. A. Mediation and moderation variables. J. Personal. Soc. Psychol. 1986, 51(6), 1173–1182. [Google Scholar] [CrossRef]
- Bashir, M. F.; Ma, B.; Shahzad, L.; Qin, W. Do renewable energy, environmental regulations and green innovation matter for environmental sustainability? Evidence from top-polluting economies. J. Environ. Manag. 2024, 354, 120412. [Google Scholar]
- Belaounia, S.; Zhao, L.; Zheng, L. Corporate governance and environmental innovation: The role of the board of directors. J. Multinatl. Financ. Manag. 2020, 56, 100643. [Google Scholar]
- Berrone, P.; Cruz, C.; Gomez-Mejia, L. R. Socioemotional wealth in family firms. Fam. Bus. Rev. 2013, 25(3), 258–279. [Google Scholar] [CrossRef]
- Berrone, P.; Cruz, C.; Gomez-Mejia, L. R.; Larraza-Kintana, M. Socioemotional wealth and corporate responses to institutional pressures: Do family-controlled firms pollute less? Adm. Sci. Q. 2010, 55(1), 82–113. [Google Scholar] [CrossRef]
- Berry, S. T.; Haile, P. A. Identification in differentiated products markets using market level data. Econometrica 2014, 82(5), 1749–1797. [Google Scholar] [CrossRef]
- Bolton, P.; Kacperczyk, M. Carbon risk and investors. J. Financ. Econ. 2021, 142(2), 517–549. [Google Scholar] [CrossRef]
- Burlea, A. S.; Popa, I. Legitimacy theory. Theor. Appl. Econ. 2013, 20(2), 113–120. [Google Scholar]
- Chambers, N.; Cifter, A. Working capital management and efficiency and firm performance in the hospitality and tourism industry. Int. J. Hosp. Manag. 2022, 102, 103144. [Google Scholar] [CrossRef]
- Chen, S.; Zhao, Y. Inventory management with trade policy uncertainty: Evidence from Chinese exporters. J. Econ. Behav. Organ. 2021, 185, 419–434. [Google Scholar]
- Cheng, B.; Ioannou, I.; Serafeim, G. Corporate social responsibility and access to finance. Strateg. Manag. J. 2014, 35(1), 1–23. [Google Scholar] [CrossRef]
- Cheung, A. (W.); Pok, W. C. Corporate social responsibility and provision of trade credit. J. Contemp. Account. Econ. 2019, 15(3), 100163. [Google Scholar] [CrossRef]
- Chouaibi, S.; Chouaibi, J.; Rossi, M. The impact of corporate social responsibility (CSR) on financial performance: The moderating role of the environmental component. J. Bus.-To-Bus. Mark. 2022, 29(1), 59–79. [Google Scholar]
- Coad, A.; Segarra, A.; Teruel, M. Like stars in the sky? The heterogeneity of firm growth rates. Small Bus. Econ. 2013, 40(2), 439–459. [Google Scholar]
- Deloof, M. Working capital and profitability. J. Bus. Financ. Account. 2003, 30(3–4), 573–588. [Google Scholar] [CrossRef]
- Deng, Y.; Lingqian, Z.; Zhang, J.; Farooq, U. Does green innovation promote trade credit activities? New empirical evidence from BRICS. Borsa Istanb. Rev. 2023, 23(5), 1143–1154. [Google Scholar] [CrossRef]
- Dhaliwal, D. S.; Li, O. Z.; Tsang, A.; Yang, Y. G. Voluntary nonfinancial disclosure and the cost of equity capital: The initiation of corporate social responsibility reporting. Account. Rev. 2011, 86(1), 59–100. [Google Scholar] [CrossRef]
- Donaldson, T.; Preston, L. E. Stakeholder theory. Acad. Manag. Rev. 1995, 20(1), 65–91. [Google Scholar] [CrossRef]
- Dong, F.; Zhu, J.; Li, Y.; Chen, Y.; Gao, Y.; Hu, M.; Sun, J. How does digital economy affect carbon-mitigation effects: Evidence from China. Energy Econ. 2022, 112, 106132. [Google Scholar]
- Eccles, R. G.; Ioannou, I.; Serafeim, G. Corporate sustainability. Manag. Sci. 2014, 60(11), 2835–2857. [Google Scholar] [CrossRef]
- Enqvist, J.; Graham, M.; Nikkinen, J. Working capital and profitability. Res. Int. Bus. Financ. 2014, 32, 36–49. [Google Scholar] [CrossRef]
- Fazzari, S. M.; Petersen, B. C. Working capital and fixed investment: New evidence on financing constraints. RAND J. Econ. 1993, 24(3), 328–342. [Google Scholar] [CrossRef]
- Ferrando, A.; Mulier, K. Do firms use the trade credit channel to manage growth? J. Bank. Financ. 2013, 37(8), 3113–3126. [Google Scholar] [CrossRef]
- Filbeck, G.; Krueger, T. M. An analysis of working capital management and efficiency results across industries. Am. J. Bus. 2005, 20(2), 11–20. [Google Scholar] [CrossRef]
- Fisman, R.; Love, I. Trade credit, financial intermediary development, and industry growth. J. Financ. 2003, 58(1), 353–374. [Google Scholar] [CrossRef]
- Flammer, C. CSR and performance. Manag. Sci. 2015, 61(11), 2549–2568. [Google Scholar] [CrossRef]
- Flammer, C. Green bonds. J. Financ. Econ. 2021, 142(2), 499–516. [Google Scholar] [CrossRef]
- Freeman, R. E. Strategic management: A stakeholder approach; Pitman, 1984. [Google Scholar]
- Friedman, M. The social responsibility of business is to increase its profits. N. Y. Times Mag. 1970, 32–33, 122–126. [Google Scholar]
- García-Meca, E.; Ramón-Llorens, M. C.; Martínez-Ferrero, J. Feminine expertise on board and environmental innovation: the role of critical mass. Rev. Manag. Sci. 2024, 18(8), 2255–2286. [Google Scholar] [CrossRef]
- García-Sánchez, I.-M.; Aibar-Guzmán, B.; Aibar-Guzmán, C.; Somohano-Rodríguez, F.-M. The drivers of the integration of the sustainable development goals into the non-financial information system: Individual and joint analysis of their influence. Sustain. Dev. 2022, 30(4), 513–524. [Google Scholar] [CrossRef]
- García-Sánchez, I.-M.; Gallego-Álvarez, I.; Zafra-Gómez, J. L. Do the ecoinnovation and ecodesign strategies generate value added in munificent environments? Bus. Strategy Environ. 2020, 29(6), 2414–2433. [Google Scholar] [CrossRef]
- García-Teruel, P. J.; Martínez-Solano, P. Working capital and SME profitability. Int. J. Manag. Financ. 2007, 3(2), 164–177. [Google Scholar] [CrossRef]
- Gill, A.; Biger, N. The impact of corporate governance on working capital management and efficiency efficiency of American manufacturing firms. J. Appl. Financ. Bank. 2012, 2(3), 45–63. [Google Scholar]
- Glass, C.; Cook, A.; Ingersoll, A. R. Do women leaders promote sustainability? Analyzing the effect of corporate governance and female leadership on environmental performance. Bus. Strategy Environ. 2016, 25(7), 495–511. [Google Scholar] [CrossRef]
- Godfrey, P. C.; Merrill, C. B.; Hansen, J. M. The relationship between corporate social responsibility and shareholder value: An empirical test of the risk management hypothesis. Strateg. Manag. J. 2009, 30(4), 425–445. [Google Scholar] [CrossRef]
- Gul, F. A.; Srinidhi, B.; Ng, A. C. Does board gender diversity improve the informativeness of stock prices? J. Account. Econ. 2011, 51(3), 314–338. [Google Scholar] [CrossRef]
- Gyimah, R.; Yao, S. D.; Agyapong, A. Effects of entrepreneurial trait on the success of small and medium scale enterprises: The Ghanaian perspective. Int. J. Bus. Manag. 2020, 15(5), 90–103. [Google Scholar]
- Han, Y.; Sarfraz, M.; Khalid, R.; Ozturk, I.; Tariq, J. CSR and green innovation. Econ. Res.-Ekon. Istraž. 2022, 35(1), 5379–5399. [Google Scholar] [CrossRef]
- Hao, J.; He, F. CSR and green innovation. Financ. Res. Lett. 2022, 48, 102889. [Google Scholar] [CrossRef]
- He, F.; Du, H.; Yu, B. Corporate ESG performance and manager misconduct: Evidence from China. Int. Rev. Financ. Anal. 2022, 82, 102201. [Google Scholar] [CrossRef]
- Hillman, A. J.; Shropshire, C.; Cannella, A. A. Organizational predictors of women on corporate boards. Acad. Manag. J. 2007, 50(4), 941–952. [Google Scholar] [CrossRef]
- Högerle, B.; Charifzadeh, M.; Mack, R.; Walz, M. The development of working capital management and efficiency and its impact on profitability and shareholder value: evidence from Germany. Int. J. Financ. Stud. 2020, 8(2), 27. [Google Scholar]
- Horbach, J. Determinants of environmental innovation—New evidence from German panel data sources. Res. Policy 2008, 37(1), 163–173. [Google Scholar] [CrossRef]
- Hsiao, C. Analysis of panel data; Cambridge University Press, 2014. [Google Scholar]
- Huang, S.-Y.; Huang, J.-W. Exploring institutional pressure, the top management team’s response, green innovation adoption, and firm performance: evidence from Taiwan’s electrical and electronics industry. J. Clean. Prod. 2022, 343, 131011. [Google Scholar]
- Hult, G. T. M.; Ketchen, D. J., Jr.; Cavusgil, S. T.; Calantone, R. J. Knowledge as a strategic resource in supply chains. J. Oper. Manag. 2006, 24(5), 458–475. [Google Scholar] [CrossRef]
- Ioannou, I.; Serafeim, G. The impact of corporate social responsibility on investment recommendations. Acad. Manag. J. 2014, 57(3), 833–864. [Google Scholar] [CrossRef]
- Jain, M.; Sharma, G. D.; Srivastava, M. Can sustainable investment yield better financial returns? A comparative study of ESG indices and MSI indices. J. Sustain. Financ. Invest. 2020, 10(3), 261–280. [Google Scholar]
- Jamali, D.; Karam, C. Corporate social responsibility in developing economies as an institutional field: Outlining a research agenda. J. Manag. Stud. 2018, 55(1), 32–61. [Google Scholar]
- Jensen, M. C.; Meckling, W. H. Theory of the firm. J. Financ. Econ. 1976, 3(4), 305–360. [Google Scholar] [CrossRef]
- Jo, H.; Harjoto, M. A. Corporate governance and firm value: The impact of corporate social responsibility. J. Bus. Ethics 2011, 103(3), 351–383. [Google Scholar] [CrossRef]
- Klassen, R. D.; Whybark, D. C. The impact of environmental technologies on manufacturing performance. Acad. Manag. J. 1999, 42(6), 599–615. [Google Scholar] [CrossRef]
- Koumanakos, D. P. The impact of lean inventory management on ESG performance. J. Manuf. Technol. Manag. 2025, 36(5), 1096–1115. [Google Scholar] [CrossRef]
- Lazaridis, I.; Tryfonidis, D. Working capital and profitability. J. Financ. Manag. Anal. 2006, 19(1), 26–35. [Google Scholar]
- Le, T. T.; Ngo, T. K.; Nguyen, Q. P. The influence of corporate governance on green innovation: Evidence from Chinese listed companies. J. Clean. Prod. 2022, 345, 131131. [Google Scholar]
- Lins, K. V.; Servaes, H.; Tamayo, A. Social capital and performance. J. Financ. 2017, 72(4), 1785–1824. [Google Scholar] [CrossRef]
- Lins, K. V.; Servaes, H.; Tamayo, A. Social capital, trust, and firm performance: The value of corporate social responsibility during the financial crisis. J. Financ. 2017, 72(4), 1785–1824. [Google Scholar] [CrossRef]
- Liu, C. Are women directors effectively linked to environmental performance? Bus. Strategy Environ. 2018, 27(8), 1137–1149. [Google Scholar]
- Loureiro, S. M. C.; Romero, J.; Bilro, R. G. Stakeholder engagement in co-creation processes for innovation: A systematic literature review and case study. J. Bus. Res. 2020, 119, 388–409. [Google Scholar] [CrossRef]
- Lu, Y.; Herremans, I. M. Board gender diversity and environmental performance: An integrated perspective. J. Clean. Prod. 2019, 212, 1080–1089. [Google Scholar]
- Luo, X.; Bhattacharya, C. B. Corporate social responsibility, customer satisfaction, and market value. J. Mark. 2006, 70(4), 1–18. [Google Scholar] [CrossRef]
- Madaleno, M.; Robaina, M.; Ferreira, V. Eco-innovation and firm performance in European highly energy consumers and polluting sectors. Innov. Eur. J. Soc. Sci. Res. 2020, 33(4), 1–28. [Google Scholar] [CrossRef]
- Margolis, J. D.; Walsh, J. P. Misery loves companies: Rethinking social initiatives by business. Adm. Sci. Q. 2003, 48(2), 268–305. [Google Scholar] [CrossRef]
- Myers, S. C. Corporate borrowing determinants. J. Financ. Econ. 1977, 5(2), 147–175. [Google Scholar] [CrossRef]
- Nadeem, M.; Zaman, R.; Saleem, I. Boardroom gender diversity and corporate sustainability practices: Evidence from Australian frontier markets. J. Clean. Prod. 2020, 245, 118883. [Google Scholar]
- Nastiti, P. K. Y.; Atahau, A. D. R.; Supramono, S. Working capital management and efficiency and profit profitability in Indonesia. J. Asia Bus. Stud. 2019, 13(4), 586–603. [Google Scholar]
- Nazir, M. S.; Afza, T. Impact of aggressive working capital management and efficiency policy on firms’ profitability. IPCF J. Appl. Financ. 2009, 15(8), 19–30. [Google Scholar]
- Newbold, P.; Carlson, W. L.; Thorne, B. M. Statistics for business and economics, 9th global ed.; Pearson Education, 2020. [Google Scholar]
- O’Brien, R. M. A caution regarding rules of thumb for variance inflation factors. Qual. Quant. 2007, 41(5), 673–690. [Google Scholar] [CrossRef]
- Orlitzky, M.; Schmidt, F. L.; Rynes, S. L. CSR and performance. Organ. Stud. 2003, 24(3), 403–441. [Google Scholar]
- Padachi, K. Working capital trends. Int. Rev. Bus. Res. Res. 2006, 2(2), 45–58. [Google Scholar]
- Pan, X.; Chen, X.; Li, C. Board gender diversity and corporate environmental performance: The moderating role of environmental uncertainty. Bus. Strategy Environ. 2020, 29(5), 1835–1846. [Google Scholar] [CrossRef]
- Petersen, M. A.; Rajan, R. G. Trade credit: Theories and evidence. Rev. Financ. Stud. 1997, 10(3), 661–691. [Google Scholar] [CrossRef]
- Phung, A. T.; Nguyen, T. T.; Nguyen, T. L. Climate risk and ESG. Financ. Res. Lett. 2022, 47, 102698. [Google Scholar] [CrossRef]
- Porter, M. E.; Kramer, M. R. Strategy and society: The link between competitive advantage and corporate social responsibility. Harv. Bus. Rev. 2006, 84(12), 78–92. [Google Scholar]
- Porter, M. E.; van der Linde, C. Environment and competitiveness. J. Econ. Perspect. 1995, 9(4), 97–118. [Google Scholar] [CrossRef]
- Post, C.; Byron, K. Women on boards and firm financial performance: A meta-analysis. Acad. Manag. J. 2015, 58(5), 1546–1571. [Google Scholar] [CrossRef]
- Preacher, K. J.; Hayes, A. F. SPSS and SAS procedures for estimating indirect effects in simple mediation models. Behav. Res. Methods Instrum. Comput. 2004, 36(4), 717–731. [Google Scholar] [CrossRef]
- Qin, P.; Sun, M.; Li, J. Green product innovation, green dynamic capability, and competitive advantage: Evidence from Chinese manufacturing enterprises. Environ. Sci. Pollut. Res. 2019, 26, 33374–33385. [Google Scholar]
- Raheman, A.; Nasr, M. Working capital management and efficiency and profitability – case of Pakistani firms. Int. Rev. Bus. Res. Res. 2007, 3(1), 279–300. [Google Scholar]
- Rajan, R. G.; Zingales, L. Capital structure determinants. J. Financ. 1995, 50(5), 1421–1460. [Google Scholar] [CrossRef]
- Rehman, A.; Yu, Y. Impact of green supply chain management practices on the environmental performance of manufacturing firms considering institutional pressure as a moderator. Sustainability 2024, 16(6), 2278. [Google Scholar] [CrossRef]
- Rennings, K. Eco-innovation theory. Ecol. Econ. 2000, 32(2), 319–332. [Google Scholar] [CrossRef]
- Richards, V. D.; Laughlin, E. J. A cash conversion cycle approach to liquidity analysis. Financ. Manag. 1980, 9(1), 32–38. [Google Scholar] [CrossRef]
- Sarkis, J.; Gonzalez-Torre, P.; Adenso-Diaz, B. Stakeholder pressure and the adoption of environmental practices: The mediating effect of training. J. Oper. Manag. 2010, 28(2), 163–176. [Google Scholar] [CrossRef]
- Shahzad, M.; Qu, Y.; Javed, S. A.; Zafar, A. U.; Rehman, S. U. Relation of environment sustainability to CSR and green innovation: A case of Pakistani manufacturing industry. J. Clean. Prod. 2020, 253. [Google Scholar] [CrossRef]
- Shanghai Belling Corp.; Ltd. 2017 Corporate Social Responsibility Report Corporate social responsibility and shareholder wealth: The role of marketing capability. In Journal of Marketing; Mishra, S., Modi, S. B., Eds.; 2018; Volume 80, 1, pp. 26–46. [Google Scholar]
- Shin, H.-H.; Soenen, L. Efficiency of working capital management and efficiency and corporate profitability. Financ. Pract. Educ. 1998, 8(2), 37–45. [Google Scholar]
- Studenmund, A. H. Using econometrics: A practical guide, 7th ed.; Pearson, 2017. [Google Scholar]
- Suchman, M. C. Legitimacy theory. Acad. Manag. Rev. 1995, 20(3), 571–610. [Google Scholar] [CrossRef]
- Tan, Y.; Zhu, Z. The effect of ESG performance on corporate innovation novelty: Evidence from China. Sustainability 2022, 14(6), 3359. [Google Scholar] [CrossRef]
- Terjesen, S.; Couto, E. B.; Francisco, P. M. Does the presence of independent and female directors impact firm performance? A multi-country study of board diversity. Corp. Gov. An. Int. Rev. 2016, 24(5), 409–426. [Google Scholar] [CrossRef]
- Tolliver, C.; Fujii, H.; Keeley, A. R.; Managi, S. Green innovation and finance in Asia. Asian Econ. Policy Rev. 2021, 16(1), 67–87. [Google Scholar] [CrossRef]
- Vishwanathan, P.; van Oosterhout, H. J.; Heugens, P. P.; Duran, P.; van Essen, M. Strategic CSR: A concept building meta-analysis of the CSR-performance relationship. J. Manag. Stud. 2019, 57(2), 314–350. [Google Scholar] [CrossRef]
- Waddock, S. A.; Graves, S. B. CSR–financial performance link. Strateg. Manag. J. 1997, 18(4), 303–319. [Google Scholar] [CrossRef]
- Wahid, A. S. The effects and the mechanisms of board gender diversity: Evidence from financial reporting quality. J. Bus. Ethics 2019, 159(3), 705–725. [Google Scholar] [CrossRef]
- Wang, M.; Li, Y.; Li, J. Organizational resilience and green innovation for environmental sustainability: The moderating role of environmental orientation. J. Bus. Res. 2023, 160, 113781. [Google Scholar]
- Wernerfelt, B. Resource-based view. Strateg. Manag. J. 1984, 5(2), 171–180. [Google Scholar] [CrossRef]
- Wiklund, J.; Shepherd, D. Knowledge-based resources, entrepreneurial orientation, and the performance of small and medium-sized businesses. Strateg. Manag. J. 2003, 24(13), 1307–1314. [Google Scholar] [CrossRef]
- Wooldridge, J. M. Econometric analysis of cross section and panel data, 2nd ed.; MIT Press, 2010. [Google Scholar]
- Wooldridge, J. M. Introductory econometrics: A modern approach; Cengage Learning, 2013. [Google Scholar]
- Xu, J.; Liu, F.; Shang, Y. R&D investment, environmental regulation, and a firm’s competitiveness: Evidence from China’s manufacturing industry. Environ. Sci. Pollut. Res. 2019, 26, 29961–29971. [Google Scholar]
- Yahya, F.; Ali, M.; Mansor, N. Board gender diversity and environmental performance: Evidence from an emerging economy. J. Clean. Prod. 2020, 264, 121654. [Google Scholar]
- Yen, T. H.; Hsieh, Y. J.; Wang, C. W. ESG and firm value. Sustainability 2023, 15(4), 3128. [Google Scholar] [CrossRef]
- Zhang, D.; Rong, Z.; Ji, Q. Green innovation and performance. Energy Econ. 2020, 85, 104560. [Google Scholar] [CrossRef]
- Zhang, Y.; Sun, J.; Yang, Z.; Wang, Y. Green innovation determinants. J. Clean. Prod. 2020, 264, 121701. [Google Scholar] [CrossRef]
Table 1.
Data Screening and Sample Size.
| Stage of Data Processing | Observations | Companies |
| Total data extracted (Population) | 50,316 | 3,594 |
| Total financial firms | 9,702 | 693 |
| After removing financial firms | 40,614 | 2,901 |
| Missing values | 30,338 | 2,167 |
| Final sample after removing missing values | 10,276 | 734 |
Table 2.
Industry Distribution.
| Industry Sector | Firms | % of Sample |
| Oil & Gas | 55 | 7.52% |
| Telecommunication | 11 | 1.45% |
| Consumer Discretionary | 70 | 9.49% |
| Healthcare | 152 | 20.66% |
| Industrials | 134 | 18.23% |
| Utilities | 34 | 4.63% |
| Services | 109 | 14.87% |
| Technology | 135 | 18.34% |
| Raw Material | 35 | 4.80% |
| Total | 734 | 100% |
Table 3.
Descriptive Statistics.
| Variable | Obs | Mean | Std. Dev. | Min | Max |
| CCC | 10,276 | 72.21 | 75.10 | -54.00 | 252.39 |
| ACP | 10,276 | 50.36 | 26.81 | 6.00 | 108.00 |
| ICP | 10,276 | 84.95 | 71.51 | 5.00 | 283.00 |
| APP | 10,276 | 63.78 | 49.50 | 14.32 | 218.53 |
| WCR | 10,276 | 0.180 | 0.123 | -0.002 | 0.464 |
| EI | 10,276 | 0.226 | 0.290 | 0.000 | 0.846 |
| CSR | 10,276 | 42.83 | 19.72 | 13.63 | 78.83 |
| AGE | 10,276 | 23.24 | 14.83 | 1.00 | 46.00 |
| Size | 10,276 | 6.53 | 0.71 | 5.21 | 7.77 |
| LEV | 10,276 | 0.115 | 0.154 | 0.000 | 0.540 |
| CR | 10,276 | 2.24 | 1.41 | 0.67 | 6.05 |
| EBITM | 10,276 | 0.061 | 0.187 | -0.525 | 0.320 |
| FA | 10,276 | 0.151 | 0.161 | 0.006 | 0.600 |
Note: Significance at the 0.10, 0.05, and 0.01 levels is indicated by *, **, and ***.
Table 5.
Model Estimation (CCC).
| Variable | OLS | Fixed Effects (FE) | Random Effects (RE) |
| EI | -0.022 | -0.036*** | -0.030*** |
| CSR | 0.023** | 0.048*** | 0.039*** |
| Age | -0.005 | -0.047 | 0.028 |
| Firm Size | 0.050* | 0.032 | -0.038* |
| Leverage | 0.006 | 0.006 | 0.007 |
| CR | 0.100*** | 0.103*** | 0.137*** |
| EBITM | 0.023* | 0.023* | 0.044*** |
| FA | 0.005 | 0.004 | -0.002 |
| Sales Growth | -0.140*** | -0.142*** | -0.138*** |
| Constant | 0.025*** | 0.025*** | 0.018 |
| Observations | 10,274 | 10,274 | 10,274 |
| R² | 0.09 | 0.09 | 0.10 |
| LM Test | 11018.43*** | ||
| Hausman Test | 216.19*** |
Note: Significance at the 0.10, 0.05, and 0.01 levels is indicated by *, **, and ***.
Table 6.
Model Estimation (ACP).
| Variable | OLS | Fixed Effects (FE) | Random Effects (RE) |
| EI | -0.014* | -0.013 | -0.012 |
| CSR | 0.014 | -0.003 | 0.014 |
| Age | 0.200*** | 0.200*** | 0.101*** |
| Firm Size | 0.110*** | 0.114*** | 0.060*** |
| Leverage | 0.010 | 0.010 | 0.010 |
| CR | 0.050*** | 0.054*** | 0.068*** |
| EBITM | -0.150*** | -0.148*** | -0.183*** |
| FA | 0.003 | 0.003 | 0.007 |
| Sales Growth | -0.160*** | -0.161*** | -0.151*** |
| Constant | 0.025*** | 0.025*** | 0.018 |
| Industry FE | Yes | Yes | Yes |
| Year FE | Yes | Yes | Yes |
| Observations | 10,276 | 10,276 | 10,276 |
| R² | 0.09 | 0.09 | 0.10 |
| LM Test | 21598.77*** | ||
| Hausman Test | 118.87*** |
Note: Significance at the 0.10, 0.05, and 0.01 levels is indicated by *, **, and ***.
Table 7.
Model Estimation (APP).
| Variable | OLS | Fixed Effects (FE) | Random Effects (RE) |
| EI | 0.002 | 0.017* | 0.006 |
| CSR | -0.015 | -0.045*** | -0.015 |
| Age | 0.141*** | 0.183*** | 0.037* |
| Firm Size | 0.020 | 0.036 | 0.005 |
| Leverage | -0.001 | -0.000 | -0.005 |
| CR | -0.083*** | -0.084*** | -0.065*** |
| EBITM | -0.080*** | -0.089*** | -0.182*** |
| FA | 0.001 | 0.001 | 0.010** |
| Sales Growth | 0.019*** | 0.019*** | 0.034*** |
| Constant | 0.024*** | 0.025*** | 0.020 |
| Industry FE | Yes | Yes | Yes |
| Year FE | Yes | Yes | Yes |
| Observations | 10,276 | 10,276 | 10,276 |
| R² | 0.29 | 0.31 | 0.34 |
| LM Test | 5305.25*** | ||
| Hausman Test | 430.17*** |
Note: Significance at the 0.10, 0.05, and 0.01 levels is indicated by *, **, and ***.
Table 8.
Model Estimation (ICP).
| Variable | OLS | Fixed Effects (FE) | Random Effects (RE) |
| EI | -0.019*** | -0.019*** | -0.025*** |
| CSR | 0.021** | 0.006 | 0.022** |
| Age | 0.010*** | 0.095*** | 0.061*** |
| Firm Size | 0.050*** | 0.048** | -0.040** |
| Leverage | 0.010 | 0.007 | 0.003 |
| CR | 0.010 | 0.009 | 0.053*** |
| EBITM | -0.060*** | -0.062*** | -0.114*** |
| FA | -0.0001 | -0.000 | 0.001 |
| Sales Growth | -0.070*** | -0.076*** | -0.061*** |
| Constant | 0.024*** | 0.025*** | 0.020 |
| Industry FE | Yes | Yes | Yes |
| Year FE | Yes | Yes | Yes |
| Observations | 10,276 | 10,276 | 10,276 |
| R² | 0.09 | 0.1 | 0.04 |
| LM Test | 16437.14*** | ||
| Hausman Test | 484.44*** |
Note: Significance at the 0.10, 0.05, and 0.01 levels is indicated by *, **, and ***.
Table 9.
Mediation analysis (CCC).
| Variable | (1) CCC | (2) CSR | (3) CCC |
| EI | -0.036*** | .3248324*** | -.014582*** |
| CSR | -.0388385*** | ||
| Age | -0.047 | .1078431*** | .0306546*** |
| Firm Size | 0.032 | .4722137 | -.0526971*** |
| Leverage | 0.006 | -.0113651*** | .0264172*** |
| CR | 0.103*** | -.0335677*** | .380412*** |
| EBITM | 0.023* | -.0426951*** | .1602209*** |
| FA | 0.004 | .0605187*** | -.0541881*** |
| Sales Growth | -0.142*** | -.0086106 | -.1189077*** |
| Constant | 0.025*** | .0373171*** | .0275748*** |
| Industry & Year | Yes | Yes | Yes |
| Observations | 10,276 | 10,276 | 10,276 |
| R² | 0.9 | 0.8 | 0.7 |
| Sobel Test | -0.013*** |
Note: Significance at the 0.10, 0.05, and 0.01 levels is indicated by *, **, and ***.
Table 10.
Mediation analysis (ICP).
| Variable | (1) ICP | (2) CSR | (3) ICP |
| EI | -0.019*** | .3248324*** | -.0678157*** |
| CSR | -.0741521*** | ||
| Age | 0.095*** | .1078431*** | .013781** |
| Firm Size | 0.048** | .4722137** | -.0015668* |
| Leverage | 0.007 | -.0113651*** | -.0203582 |
| CR | 0.009 | -.0335677** | .3627515 |
| EBITM | -0.062*** | -.0426951*** | -.2132005*** |
| FA | -0.000 | .0605187** | -.0051853 |
| Sales Growth | -0.076*** | -.0086106 | -.0094869 |
| Constant | 0.025*** | .0373171*** | .0098857*** |
| Industry & Year | Yes | Yes | Yes |
| Observations | 10,276 | 10,276 | 10,276 |
| Sobel Test | -0.024** |
Note: Significance at the 0.10, 0.05, and 0.01 levels is indicated by *, **, and ***.
Table 11.
Mediation analysis (APP).
| Variable | (1) APP | (2) CSR | (3) APP |
| EI | 0.017* | .3248324*** | .0142948*** |
| CSR | .0185198 | ||
| Age | 0.183*** | .1078431*** | -.0104379** |
| Firm Size | 0.036 | .4722137 | .0550169** |
| Leverage | -0.000 | -.0113651*** | -.0408047** |
| CR | -0.084*** | -.0335677*** | -.0362311 |
| EBITM | -0.089*** | -.0426951*** | -.4185033*** |
| FA | 0.001 | .0605187*** | .0574218 |
| Sales Growth | 0.019*** | -.0086106 | .055991*** |
| Constant | 0.025*** | .0373171*** | -.0132889** |
| Industry & Year | Yes | Yes | Yes |
| Observations | 10,276 | 10,276 | 10,276 |
| Sobel Test | 0.005 (Insignificant) |
Note: Significance at the 0.10, 0.05, and 0.01 levels is indicated by *, **, and ***.
Table 12.
Mediation analysis (ACP).
| Variable | (1) ACP | (2) CSR | (3) ACP |
| EI | -0.013 | .3248324*** | -.0426553*** |
| CSR | -.0295872*** | ||
| Age | 0.200*** | .1078431*** | .050368 |
| Firm Size | 0.114*** | .4722137 | .0354735*** |
| Leverage | 0.010 | -.0113651*** | .0132662* |
| CR | 0.054*** | -.0335677*** | .1348479* |
| EBITM | -0.148*** | -.0426951*** | -.2547494*** |
| FA | 0.003 | .0605187*** | .0185051* |
| Sales Growth | -0.161*** | -.0086106 | -.1470615*** |
| Constant | 0.025*** | .0373171*** | .0088463*** |
| Industry & Year | Yes | Yes | Yes |
| Observations | 10,276 | 10,276 | 10,276 |
| R² | 0.09 | 0.31 | 0.34 |
| Sobel Test | -0.01** |
Note: Significance at the 0.10, 0.05, and 0.01 levels is indicated by *, **, and ***.
Table 13.
Robustness and Endogeneity Test (Two-Step System GMM).
| Variables |
(1) CCC |
(2) CSR |
(3) CCC |
(4) Two-Step GMM |
| Lag.EI | -0.048*** | 0.271*** | -0.071** | |
| CSR | -0.112*** | |||
| L.CCC | 0.286*** | |||
| L2.CCC | 0.137*** | |||
| EI | -0.045*** | |||
| Age | 0.039* | -0.019 | -0.021 | 0.031*** |
| Firm Size | 0.312*** | -0.142*** | -0.149*** | 0.032*** |
| Leverage | -0.069** | 0.084** | 0.079** | |
| Sales Growth | 0.101*** | -0.049* | -0.047* | |
| Constant | 0.437*** | 5.534*** | 5.462*** | 5.012*** |
| Industry & Year | Yes | Yes | Yes | Yes |
| Observations | 12600 | 12600 | 12600 | 12600 |
| R² | 0.30 | 0.34 | 0.36 | |
| AR(1) | -2.61** | |||
| AR(2) | -0.84 | |||
| Wald-Chi² | 492.47*** | |||
| Sargan Test | 0.88 | |||
| Sobel Test | -0.013*** |
Disclaimer/Publisher’s Note: The statements, opinions and data contained in all publications are solely those of the individual author(s) and contributor(s) and not of MDPI and/or the editor(s). MDPI and/or the editor(s) disclaim responsibility for any injury to people or property resulting from any ideas, methods, instructions or products referred to in the content. |
© 2026 by the author. Licensee MDPI, Basel, Switzerland. This article is an open access article distributed under the terms and conditions of the Creative Commons Attribution (CC BY) license.
Copyright: This open access article is published under a Creative Commons CC BY 4.0 license, which permit the free download, distribution, and reuse, provided that the author and preprint are cited in any reuse.